
Bitmine Immersion Technologies (BMNR) Announces ETH Holdings Reach 5.90 Million Tokens, and Total Crypto and Total Cash Holdings of $15.6 Billion
Source: PR Newswire
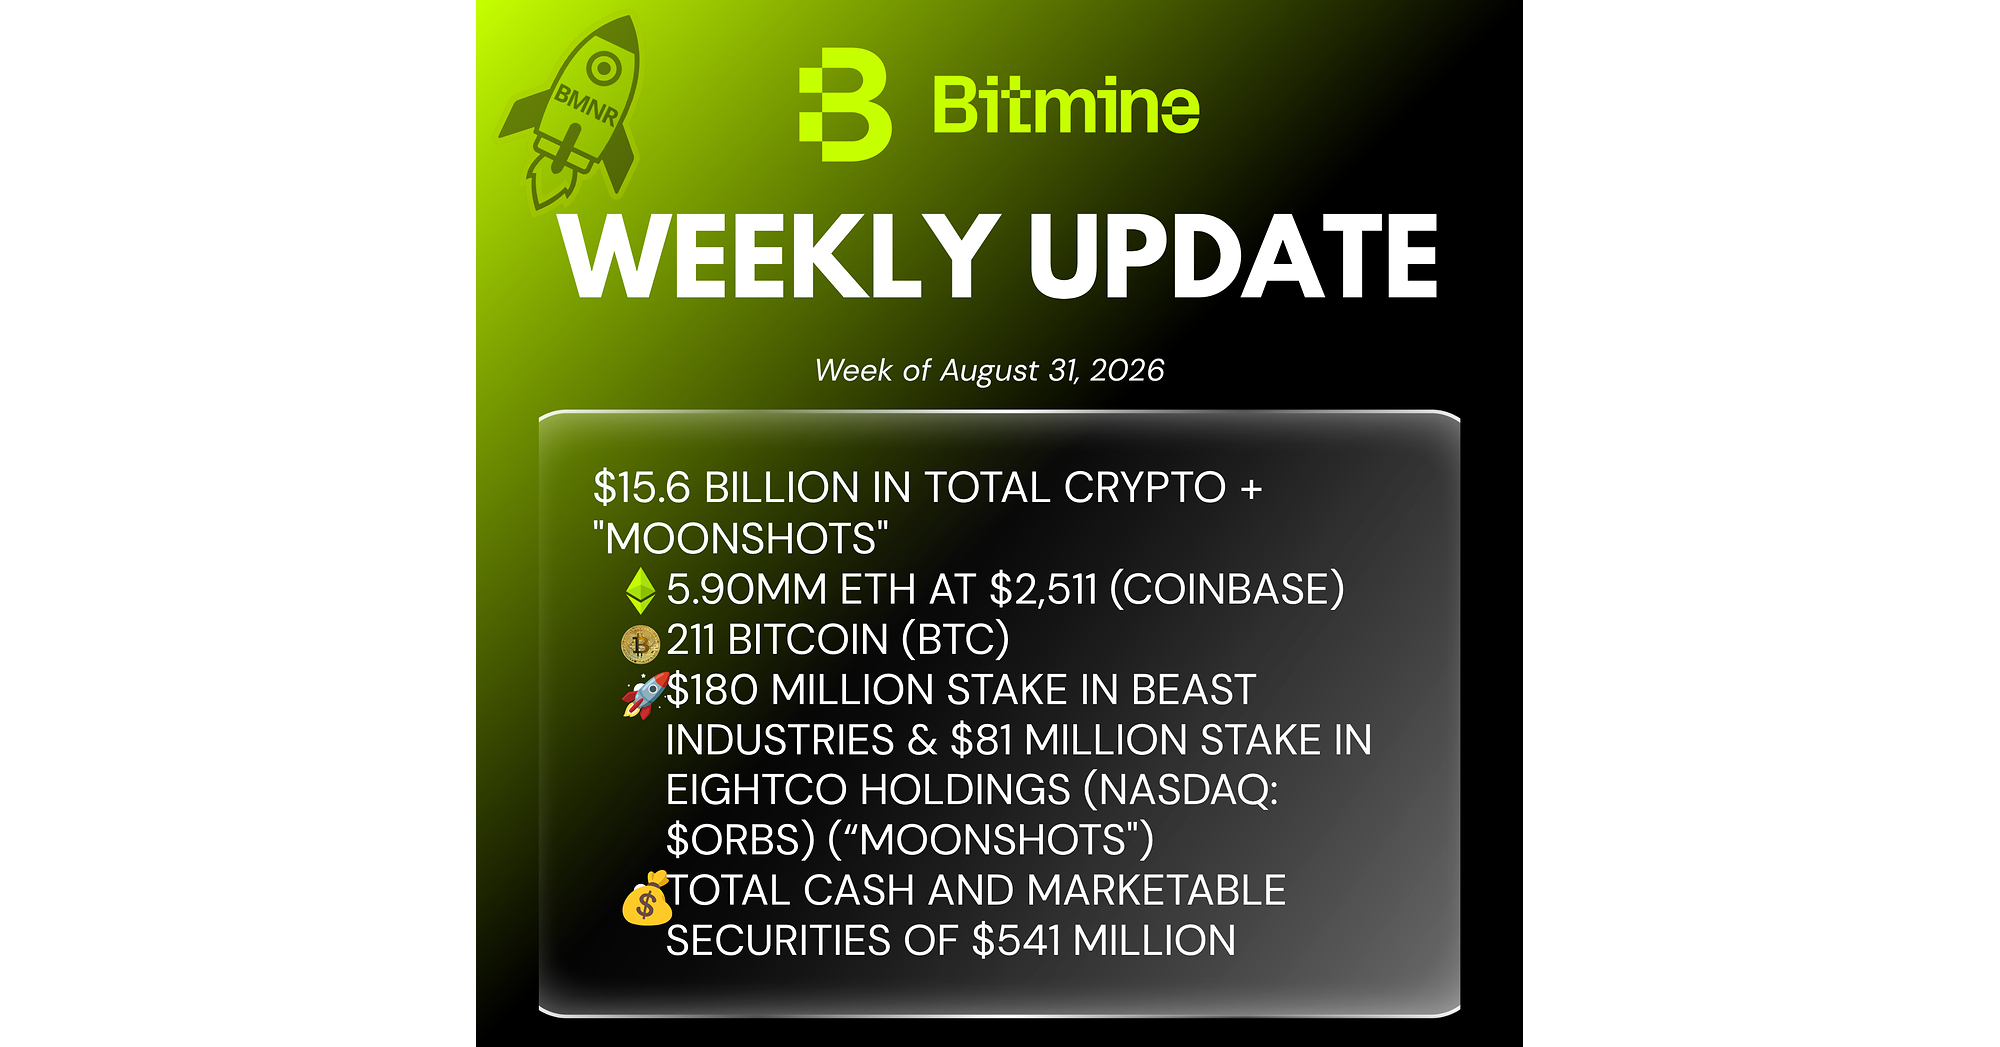
Bitmine (NYSE: BMNR) reports $15.6B in total crypto + total cash & marketable securities + “moonshots,” including 5.901M ETH (4.9% of the ~120.7M ETH supply) valued at $2,511/ETH, plus $541M in cash & marketables. The company says it acquired 53,501 ETH over the past week and has bought ETH every week since June 30, 2025, while 5.067M ETH is staked (about $12.7B) and projected annualized staking revenues are ~$335M (2.63% 7-day yield annualized). Management cites ETH outperforming in 3Q26 (outpacing the S&P 500 by 5,430 bps) and points to potential catalysts including a mid-September CLARITY Act vote; the news is largely asset-positioning and outlook rather than new financial results.
Analysis
This is less a fundamental update than a liquidity signal: BMNR is trying to convert a concentrated ETH balance sheet into a persistent public-market premium via staking yield and index inclusion. If that premium holds, it creates a reflexive funding loop where equity strength lowers capital costs and supports more ETH accumulation; if it breaks, the stock can de-rate quickly because the market is really paying for leverage to ETH plus a narrative premium, not for conventional operating earnings.
The second-order winner is the ETH ecosystem’s financing stack — staking, custody, and treasury-adjacent infrastructure — because a large public ETH holder normalizes the asset for allocators who can’t own spot directly. Relative loser is BTC-treasury exposure: if the market starts rewarding ETH’s yield and smart-contract optionality over pure digital-gold scarcity, MSTR’s multiple can lag even if crypto stays bid. ORBS reads as promotional optionality rather than durable value creation; these “moonshot” side stakes usually add volatility, not NAV credibility.
Catalyst path is two-tiered: days-to-weeks is driven by crypto spot beta and whether the market believes the Sept. regulatory event will de-risk staking/treasury structures; 1-3 months is about ETH/BTC relative performance and whether institutions follow the treasury trade; 6-18 months is whether staking yield is viewed as real distributable cash flow or just mark-to-market leverage. The contrarian risk is that this becomes crowded fast: if ETH stalls or the regulatory vote slips, BMNR’s premium can compress before NAV does. The thesis is falsified if ETH/BTC rolls over, BMNR loses its volume leadership, or staking/yield economics fail to translate into sustained equity demand.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- Pair trade: long BMNR / short MSTR for 1-3 months to express ETH-vs-BTC relative strength; target outperformance if ETH/BTC keeps trending higher, but cut if ETH/BTC retraces below the recent breakout level or if BMNR premium-to-NAV starts compressing.
- Tactical long BMNR only on a pullback, not on upside extension; use a 2-4 week horizon into the mid-Sept regulatory catalyst with a tight stop tied to ETH spot weakness, since the stock is effectively a high-beta ETH proxy.
- Watch-list GLXY as the lower-volatility infrastructure beneficiary; if staking/prime brokerage names start outperforming treasury vehicles, it signals the market is shifting from narrative exposure to picks-and-shovels exposure.
- Avoid or fade ORBS on strength; treat it as a sentiment amplifier rather than a fundamentals story unless there is verifiable revenue or balance-sheet disclosure that justifies a re-rate.
More News
- KeyBanc downgrades Cirrus Logic after Asia trip, sees memory and analog strength
- These Consumer Stocks Are Getting a Lift as Investors Rotate Out of Tech
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- Brian Sullivan: Why the 'real' price of oil is likely $30-$40 higher than where it is now
- Treasuries Soar as Tech Slump Threatens Growth
- Penske Automotive agrees to be taken private by Penske, Mitsui