
Speediance Names Cycling Legend Sir Mark Cavendish KBE Brand Ambassador and Launches "Build for Belief"
Source: PR Newswire
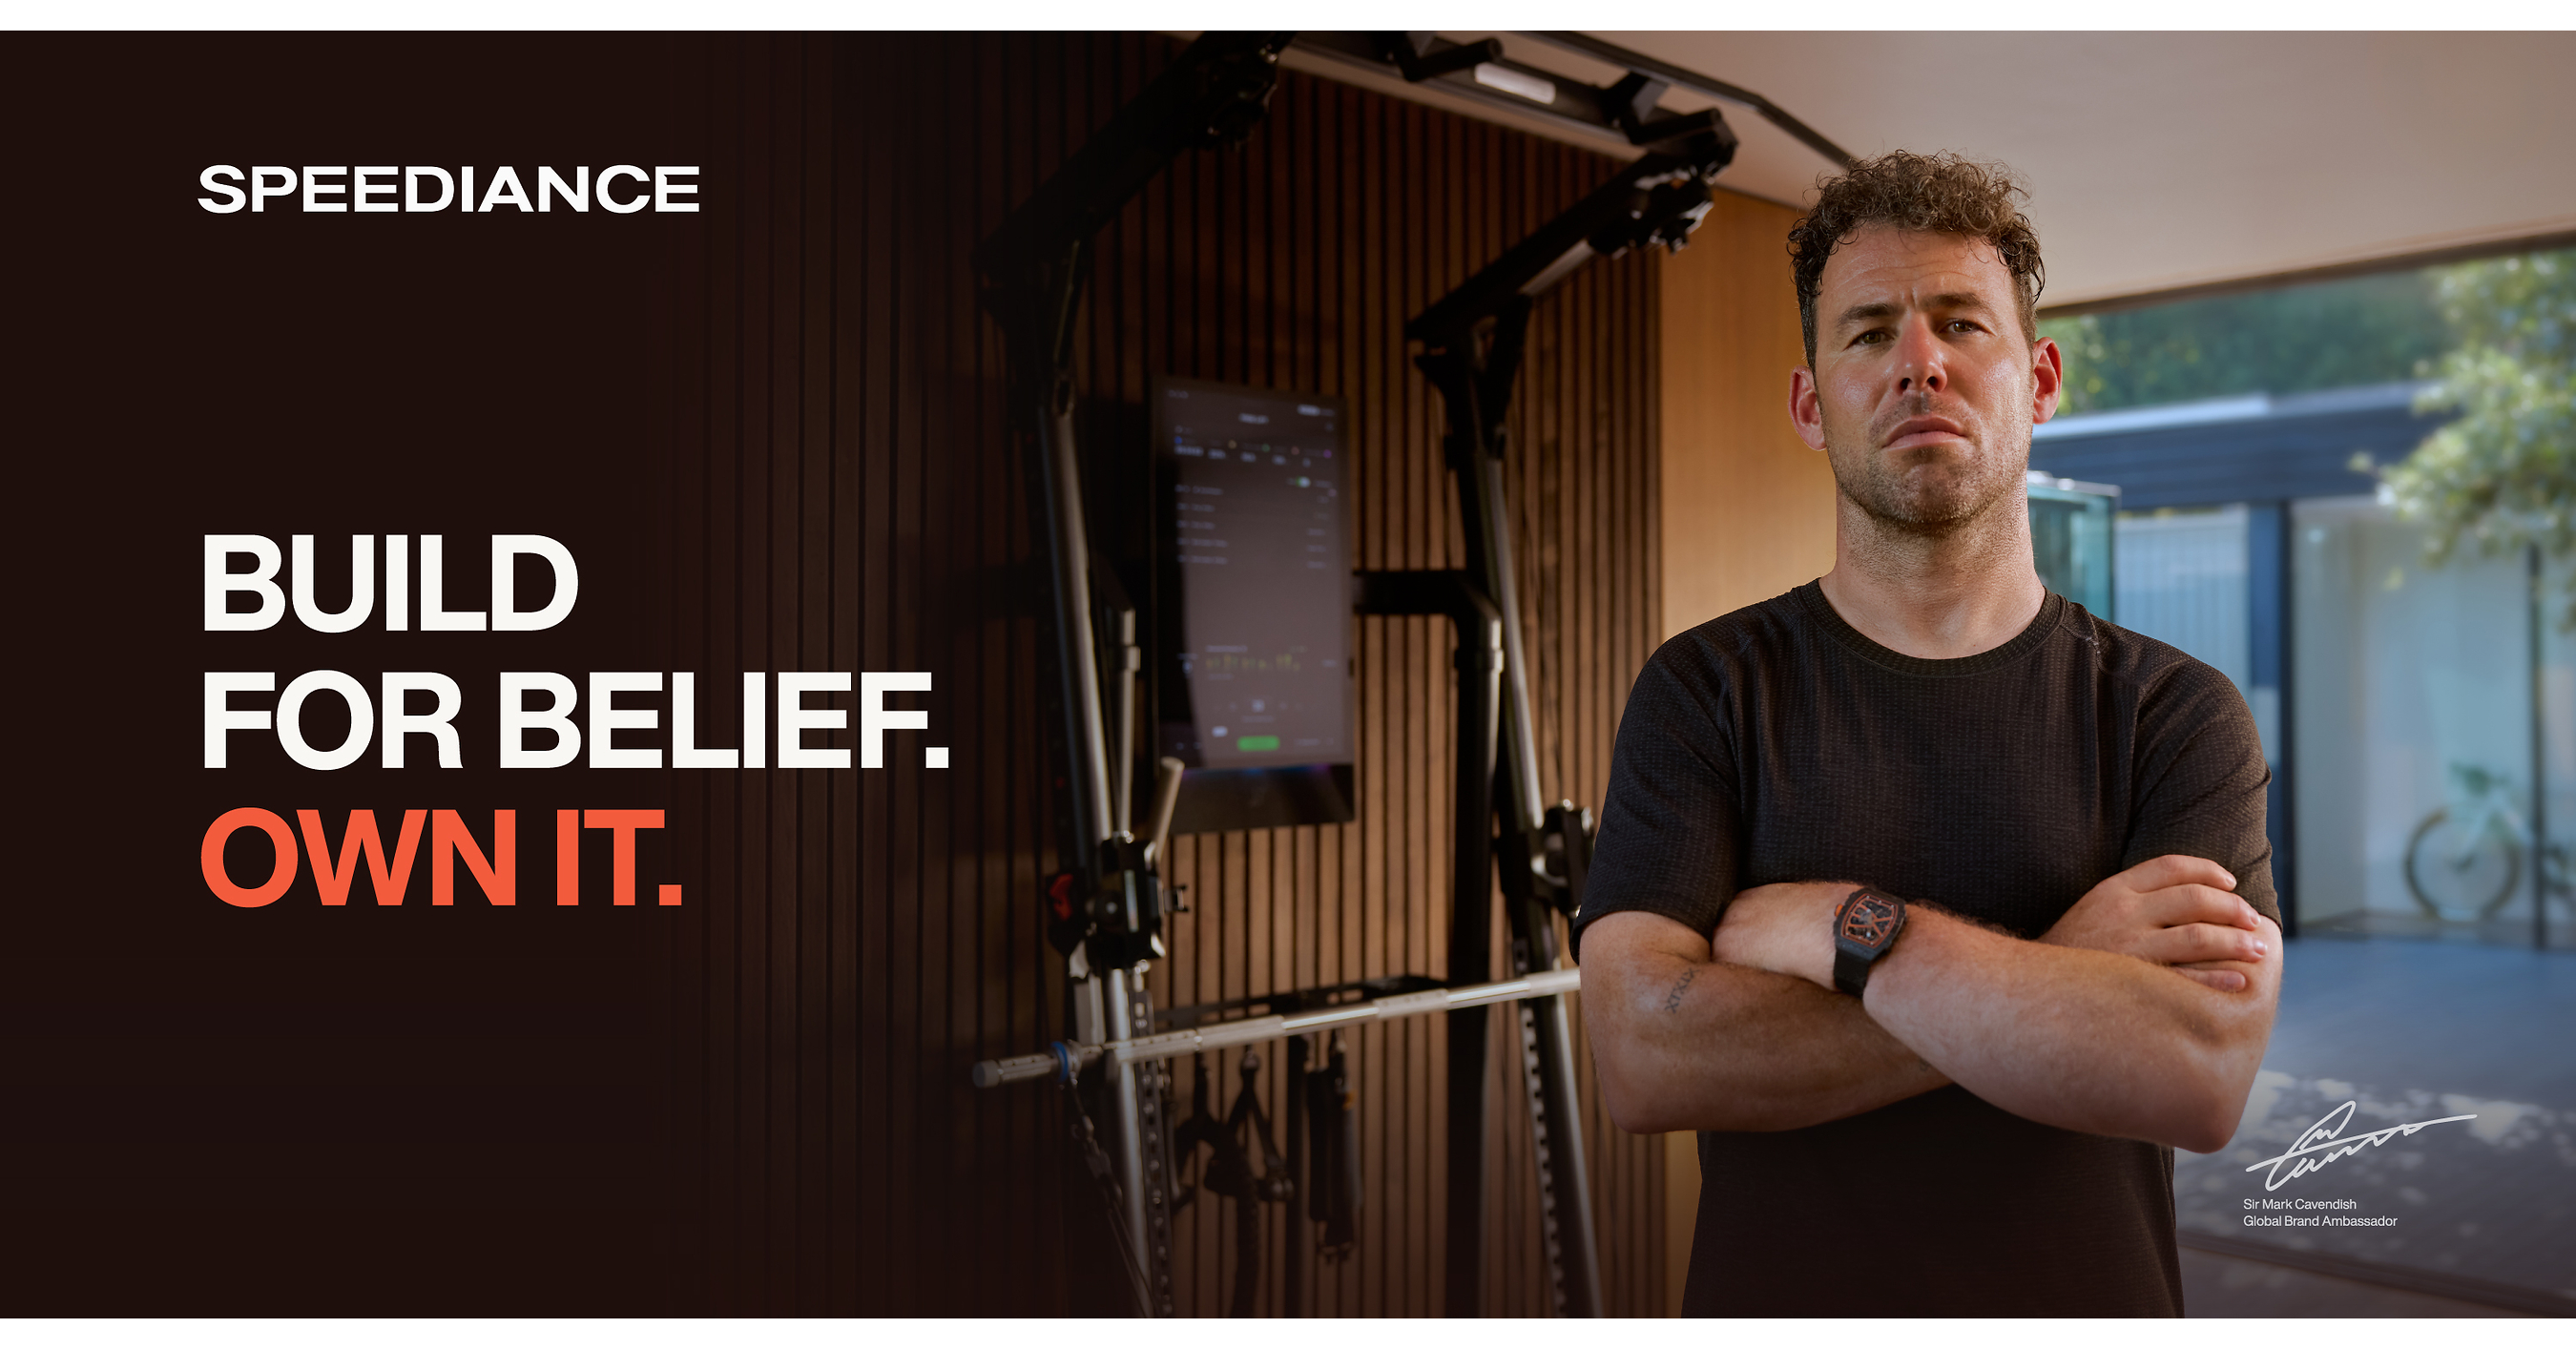
Speediance named Tour de France record holder Sir Mark Cavendish, who has 35 stage wins, as global brand ambassador and launched its "Build for Belief" marketing campaign. The initiative positions the connected-fitness company beyond hardware performance by linking its digital resistance and personalized-training products to global sporting culture and consumer identity. The announcement contains no financial metrics, sales outlook, or quantified commercial targets.
Analysis
This is not independently verifiable evidence of incremental demand, pricing power, or improved unit economics; it is a brand-marketing spend signal. The relevant read-through is modestly negative for publicly traded connected-fitness incumbents if it confirms that well-funded private hardware brands are shifting from product-led acquisition toward premium lifestyle positioning, raising customer-acquisition costs across the category. Peloton (PTON) is most exposed because it needs sustained subscriber and hardware demand while carrying limited room for marketing inefficiency; Garmin (GRMN) and Apple (AAPL) have diversified ecosystems that make any single-home-fitness challenger immaterial.
Near term, there is no listed security with direct exposure and no reason to trade on the announcement. Over 1-3 months, monitor whether Speediance expands retail distribution, discloses financing, or uses the campaign to support European/US price promotions; those would be more meaningful evidence of a land-grab strategy and could pressure premium connected-fitness hardware ASPs. The 6-18 month structural risk is category fragmentation: digital-resistance platforms may compete more directly with Peloton Strength and Tonal-style offerings than with cardio hardware, shifting consumer spending toward lower-footprint, multifunction equipment.
The contrarian view is that celebrity endorsements are often a symptom of weak organic awareness rather than a moat. Unless the campaign produces measurable search-share, retail sell-through, or subscription attach gains, marketing expenditure may simply worsen private-company cash burn; in that case it has no investable implication for listed peers. A PTON short thesis based on this development is falsified if Peloton reports improving paid connected-fitness subscriptions, declining CAC, and stable hardware gross margin despite elevated competitor promotion.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.22
Key Decisions for Investors
- No standalone trade: treat this as a competitive-intelligence watch item rather than a catalyst, given the absence of a listed issuer, disclosed spend, sales data, or distribution commitments.
- Maintain PTON as the listed read-through monitor; consider a tactical underweight only if channel checks show Speediance/Tonal-style strength products discounting aggressively into holiday 2026. Risk/reward requires evidence of PTON hardware ASP or subscription guidance pressure before initiating.
- Set alerts for Speediance US/EU retail partnerships, financing rounds, app-subscription pricing, and holiday promotions over the next 90 days. A meaningful retail rollout paired with sub-$3,000 promotional pricing would raise the probability of competitive pressure on PTON's strength and cross-training roadmap.
- Prefer GRMN or AAPL over pure-play connected-fitness exposure for any broader wellness-device allocation: diversified wearables, software ecosystems, and balance sheets limit sensitivity to escalating home-fitness acquisition costs.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- Microsoft's Big Bets on AI Start to Pay Off
- Google's Gemini 4 Carbon looks like a diamond in the rough
- China’s tech darlings are losing their shine. Here’s what’s behind the sell-off
- Microsoft’s strong quarter backs up its stock rebound. Here's our new price target