
Sandpiper Hospitality Accelerates Growth Across the Country
Source: PRWeb
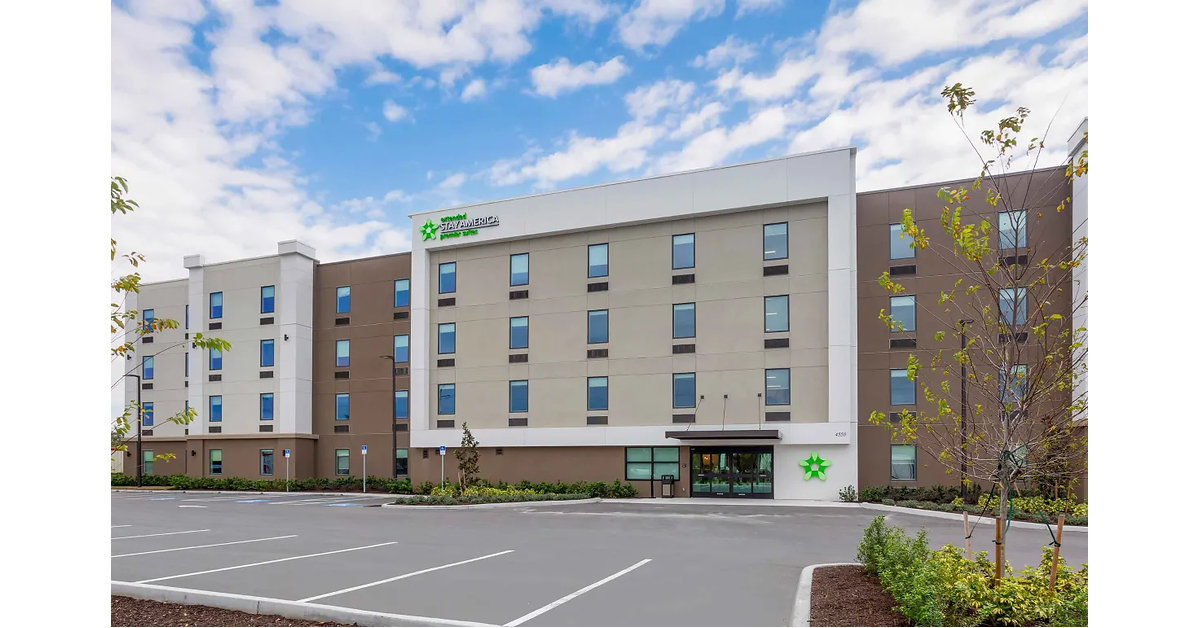
Sandpiper Hospitality plans to add more than a dozen hotels over the next 90 days, expanding into four brands new to its management portfolio: Homewood Suites, Hampton Inn, Fairfield Inn & Suites, and Holiday Inn Express. Most additions are in extended stay, and the company says its portfolio includes 75+ hotels open or under management. The release points to broader reach and client growth but gives no financial results or quantified return targets.
Analysis
The investable read-through is limited: Sandpiper is a hotel manager, and a larger managed portfolio does not by itself establish hotel ownership, incremental room supply, franchise commitments, or material revenue for the public brand companies. If the additions translate into newly affiliated rooms, Hilton (HLT), Marriott (MAR), IHG (IHG), and Choice Hotels (CHH) could each gain modest distribution and recurring franchise-related economics; the effect is likely diluted against their much larger systems. The more meaningful second-order question is whether third-party owners are increasingly outsourcing operations to specialist managers, which could intensify competition for management contracts and support operators with scalable extended-stay expertise. The release provides no room count, contract economics, opening schedule by property, or independently verified performance data, so claims of superior investor returns are not evidence of stronger hotel-level margins or demand.
Near term (days), this is not a fundamental catalyst for the mapped public tickers. Over 1–3 months, verify actual openings and brand affiliation through company room-addition disclosures; over 6–18 months, watch whether extended-stay supply growth pressures occupancy or pricing in affected markets. Contrarian view: portfolio growth sounds bullish but may primarily reflect contract wins or transfers of existing hotels, not net new industry demand. A thesis of material brand-company benefit would be falsified by no identifiable net room additions or by weaker extended-stay RevPAR and hotel-level returns.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- No trade on the announcement alone: the disclosed information does not establish a material earnings contribution for MAR, HLT, IHG, or CHH.
- Put the four brand companies on a verification watchlist; seek confirmed net room additions, opening dates, and whether properties are newly affiliated versus reflagged before revising estimates.
- Monitor extended-stay RevPAR, occupancy, and new room supply in the Southwest and Midwest over the next 1–3 months; weakening pricing alongside supply growth would challenge the segment-positive narrative.
- Treat continued outsourced-management wins as a longer-term competitive signal, not yet a listed-equity catalyst; reassess only if Sandpiper or owners disclose property-level economics, scale, or measurable operating results.
More News
- UBS reiterates Buy on Coca-Cola stock citing earnings visibility
- BlackRock, GIC among investors chasing Indian telecom major Jio's IPO as anchor bids top $26 billion
- Nscale, Anthropic Eye $45 Billion Cloud Deal as AI Trade Rebounds
- Gartner analyst behind tech rout: AI returns are not yet large enough to justify neocloud build-out
- Saudi Arabia cancels 2026 ‘Davos in the Desert’ amid Houthi attacks
- Walmart’s Flipkart is quietly building a food delivery challenger in India