
Parex Resources: License To Print Money Is Now Fully Active
Source: seekingalpha.com
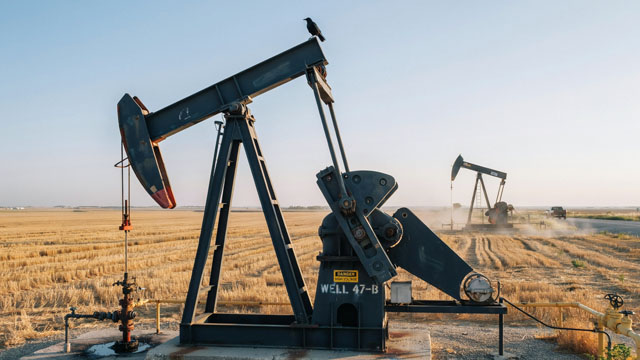
Parex Resources reported a $302 million gain from its Frontera acquisition, described as nonrecurring, while its stock is characterized as undervalued. The article expects strong commodity prices to support future earnings and says management has repaid $175 million of acquisition-related debt, with net debt expected to decline rapidly.
Analysis
The key valuation question is whether investors are treating the acquisition-related gain as repeatable earnings. If it is primarily an accounting gain rather than cash generated by operations, it should be excluded from normalized earnings and debt-paydown capacity; verify its cash-flow and purchase-accounting treatment before underwriting the apparent cheapness. The more durable upside case is operating cash flow funding lower net debt, which could reduce balance-sheet risk and support a better equity multiple—but only if production, realized prices, and investment needs leave a meaningful free-cash-flow surplus.
Near term, headline earnings may obscure the run rate. Over the next 1–3 months, focus on reported production, realized pricing versus benchmark crude, capex, and the cash bridge behind debt repayment. Over 6–18 months, sustained deleveraging could make PXT less vulnerable to a commodity downturn; it would not remove the underlying commodity exposure. Higher crude can lift cash generation, while weaker prices or adverse realized-price differentials can slow repayment and reverse the de-risking narrative. The contrarian risk is that investors capitalize a one-off gain and extrapolate strong prices into durable earnings. The thesis weakens if operating cash flow, excluding the gain, fails to cover capex and debt reduction, or management’s net-debt trajectory stalls. Treat the positive signal as conditional, not proof of undervaluation.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- PXT: consider a measured long only after reconciling the acquisition gain to operating cash flow and confirming that normalized free cash flow supports further net-debt reduction. Do not value the one-time gain as recurring earnings.
- For the next results and any guidance update, track production, realized prices/differentials, capex, and net debt—not headline net income alone. A shortfall in cash conversion or a stalled debt decline falsifies the deleveraging case.
- Avoid treating the reported debt repayment as evidence that leverage risk is resolved: monitor crude-price downside and any increase in investment needs. If commodity prices weaken while net debt stops falling, reassess or reduce the position.
- No forced FEC position: the supplied information does not establish a separate earnings or valuation implication for Frontera Energy Corporation beyond its connection to the acquisition.
More News
- BlackRock, GIC among investors chasing Indian telecom major Jio's IPO as anchor bids top $26 billion
- Copper Holds Drop as Traders Gauge Risks From US Tariff Policy
- Gartner analyst behind tech rout: AI returns are not yet large enough to justify neocloud build-out
- Walmart’s Flipkart is quietly building a food delivery challenger in India
- Credit stress is threatening to unwind the AI bull. All eyes are on Oracle to hold the line
- LightStream stops accepting loan applications. Try these 6 lenders instead