
Quill Bank launches merchant acquiring business, names Deborah Camm to lead
Source: PR Newswire
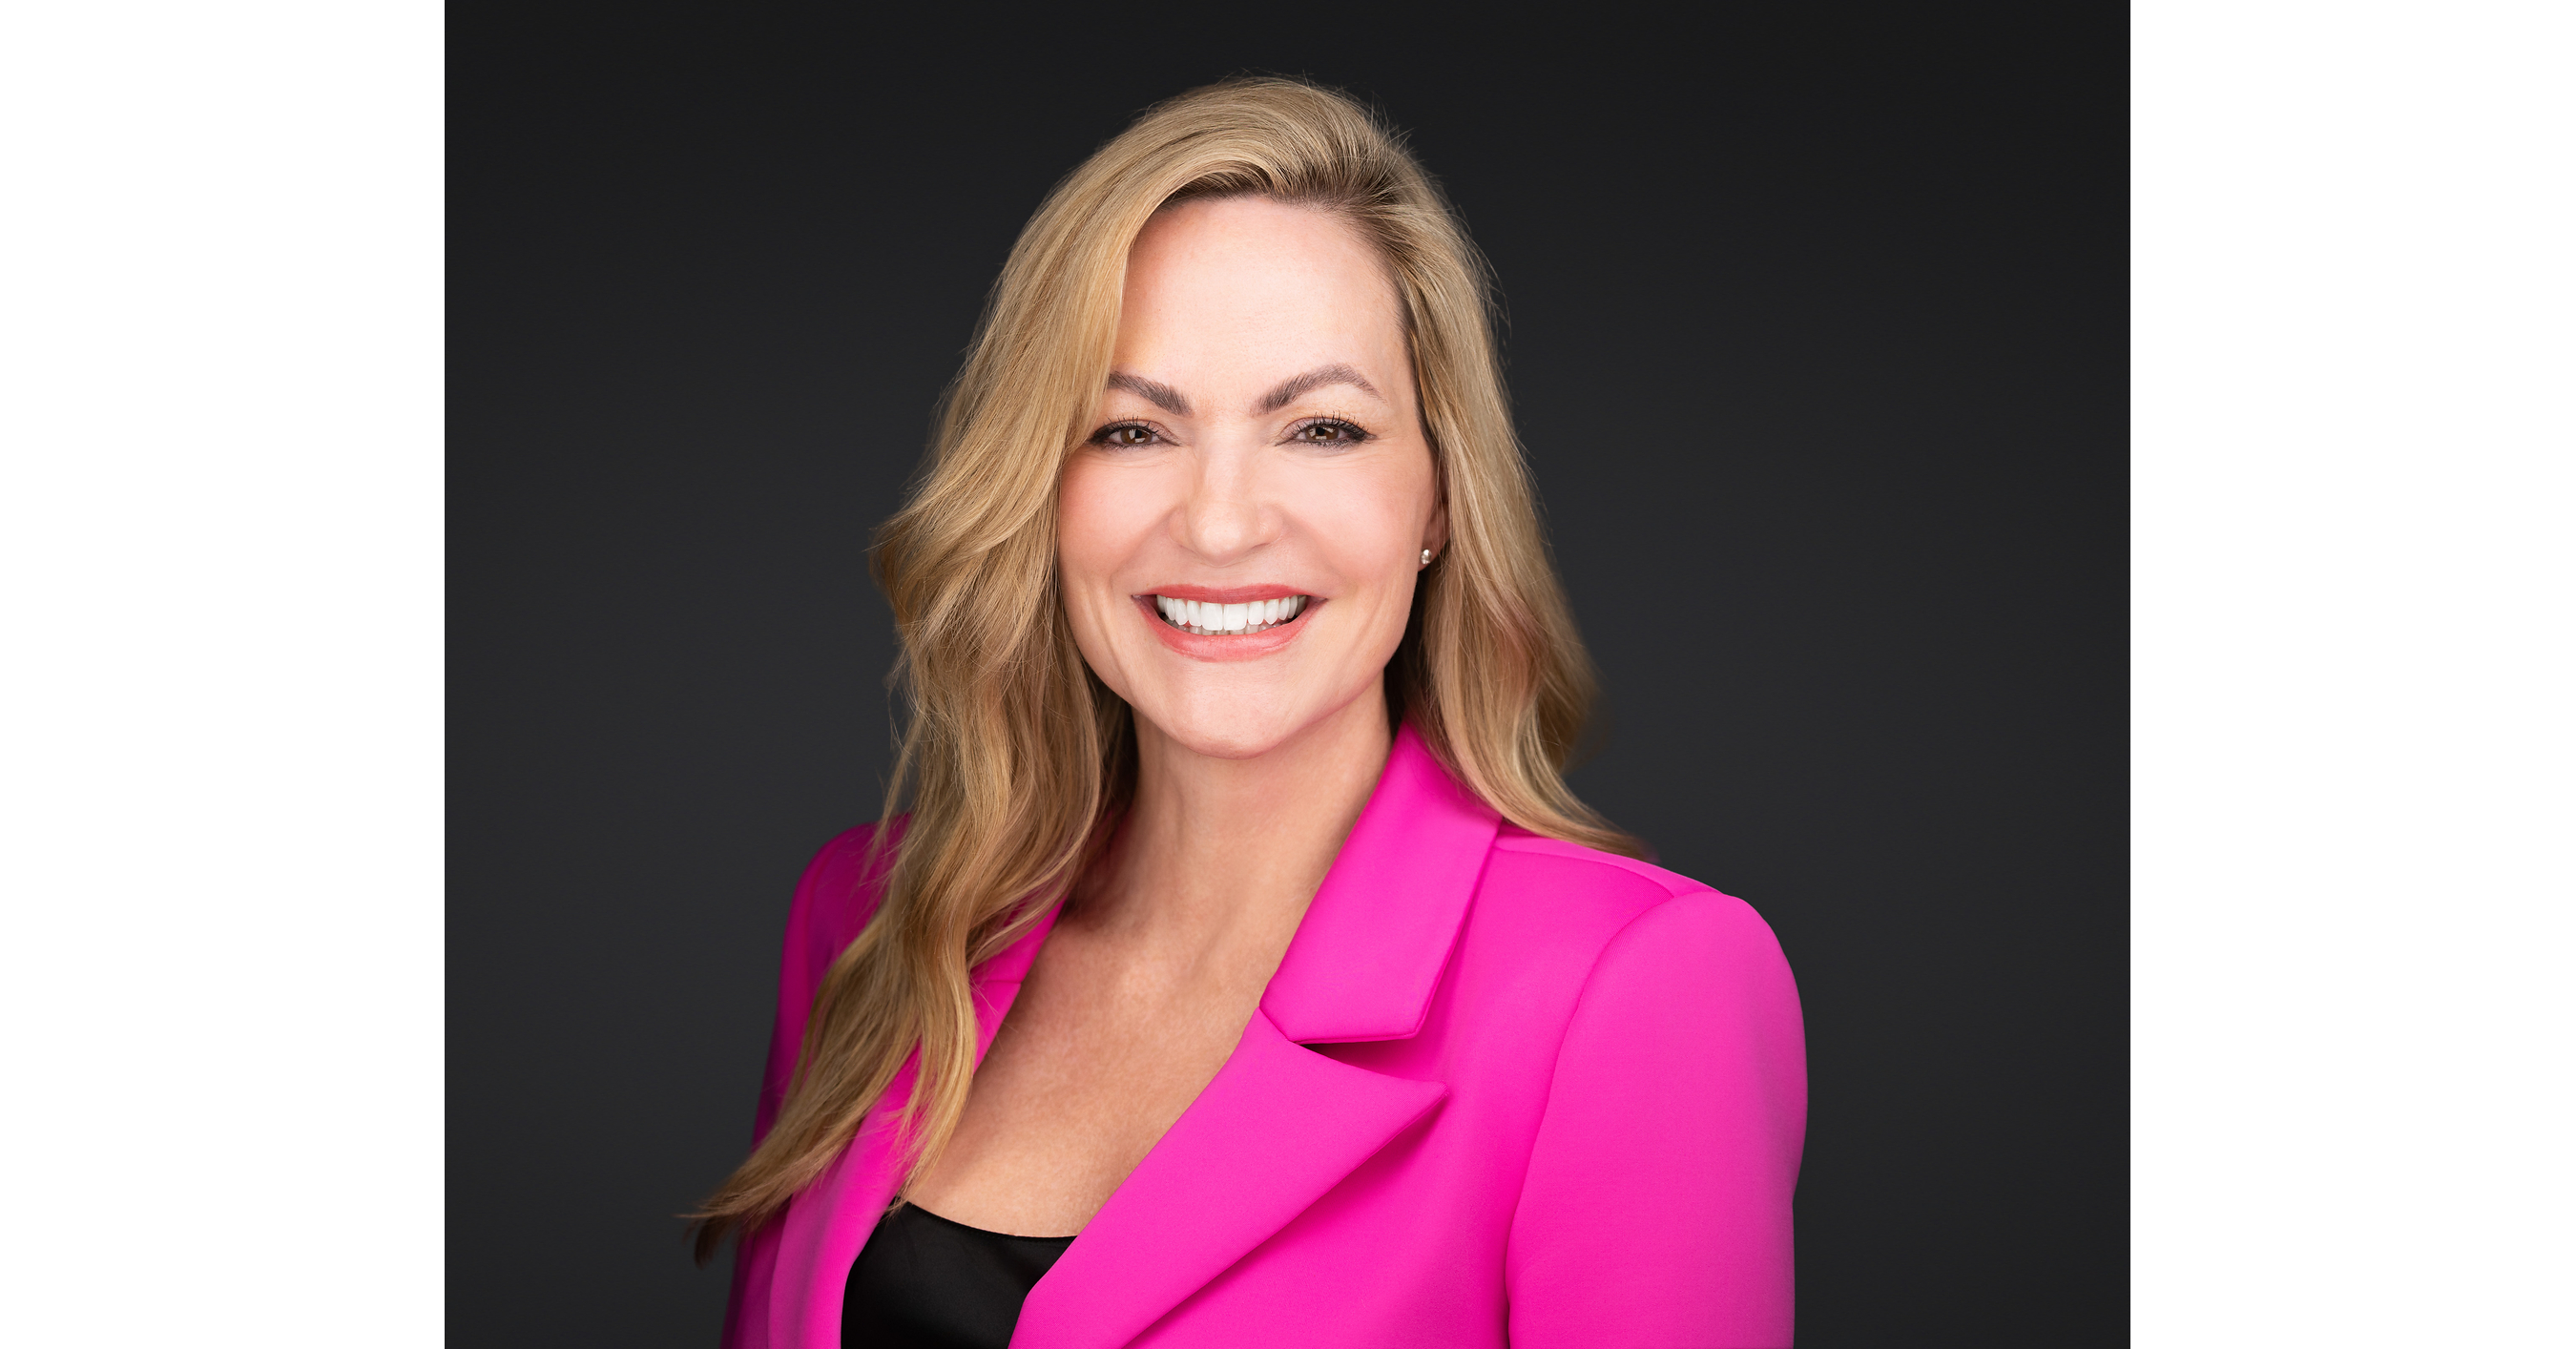
Quill Bank launched an Acquiring Line of Business for sponsored entities, consolidating merchant acquiring, card issuing, real-time payments, disbursements, lending and sponsor-bank services under one banking relationship. The approximately $1.6 billion-asset Utah bank appointed payments veteran Deborah Camm, with more than 25 years of merchant bankcard experience, as SVP and Head of Acquiring. The expansion broadens Quill's payments offering and targets new revenue opportunities among fintechs, payment facilitators, ISOs and ISVs.
Analysis
This is strategically more relevant to sponsor-bank economics than to the listed merchant-acquiring incumbents. A bundled sponsor-bank/acquiring offering can raise partner switching costs and improve fee capture per fintech client, but it also concentrates underwriting, fraud, chargeback, AML and settlement-liquidity exposure within a smaller balance sheet. The initial commercial effect is likely negligible for FIS, FI, GPN and JKHY; the more direct public comparables are sponsor-bank platforms TBBK and CASH, whose valuation depends on proving durable, well-controlled fintech-program fee income.
The key issue over the next 6-18 months is whether the bank can originate acquiring volume without underpricing reserves or accepting higher-risk payment facilitators. Acquiring revenue can appear highly recurring until fraud losses, network-rule violations or a sponsor-partner failure generate abrupt reserve requirements and reputational damage. A successful integrated proposition could pressure standalone program managers and middleware providers, but the market should demand evidence of signed partners, payment volume, net take rate, loss experience and core-deposit/contingent-liquidity funding before assigning strategic value.
There is no actionable public-equity trade from the announcement alone. The contrarian read is that one-stop payments is not inherently a moat: established processors retain material scale advantages in authorization economics, data, risk tooling and distribution, while regulated-bank integration adds supervisory complexity. The near-term signal is therefore an operating-risk watch item rather than an industry-disrupting catalyst.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No position on this announcement; treat it as non-priceable private-company news until partner wins, annualized processing volume, reserve balances and credit-loss disclosures are independently observable.
- Maintain a 1-3 month monitoring basket of TBBK and CASH versus KRE: investigate any valuation premium driven by fintech-program growth for evidence that acquiring/settlement exposure is being adequately reserved and funded.
- For holders of GPN, FIS and FI, do not alter exposure on this development; reassess only if multiple sponsor banks publicly report merchant-acquiring share gains or fee-rate compression in 2027 guidance.
- Set a risk alert for regulatory actions, elevated chargeback ratios, or rapid growth in noninterest-bearing/settlement balances at sponsor banks; any of these would challenge the assumption that bundled payments growth is capital-light and could warrant reducing sponsor-bank exposure.
More News
- Asian stocks rise as oil retreat eases inflation fears, BOJ in focus
- Why High Yields on Treasury Bonds, Government Debt Look Like the New Normal
- Fed rate decision and Warsh comments roiled markets. Where to find opportunities
- How Bessent, America’s bond salesman, cornered Japan on big spending
- Microsoft exec called AI scraping the “largest theft of labor in human history”
- Yuan hits 4-year high ahead of Trump-Xi meeting as China broadens clearing