
Papa Murphy's Signs Three Co-Brand Franchise Agreements, Expanding Growth Opportunities for Papa Murphy's and Pinkberry
Source: PR Newswire
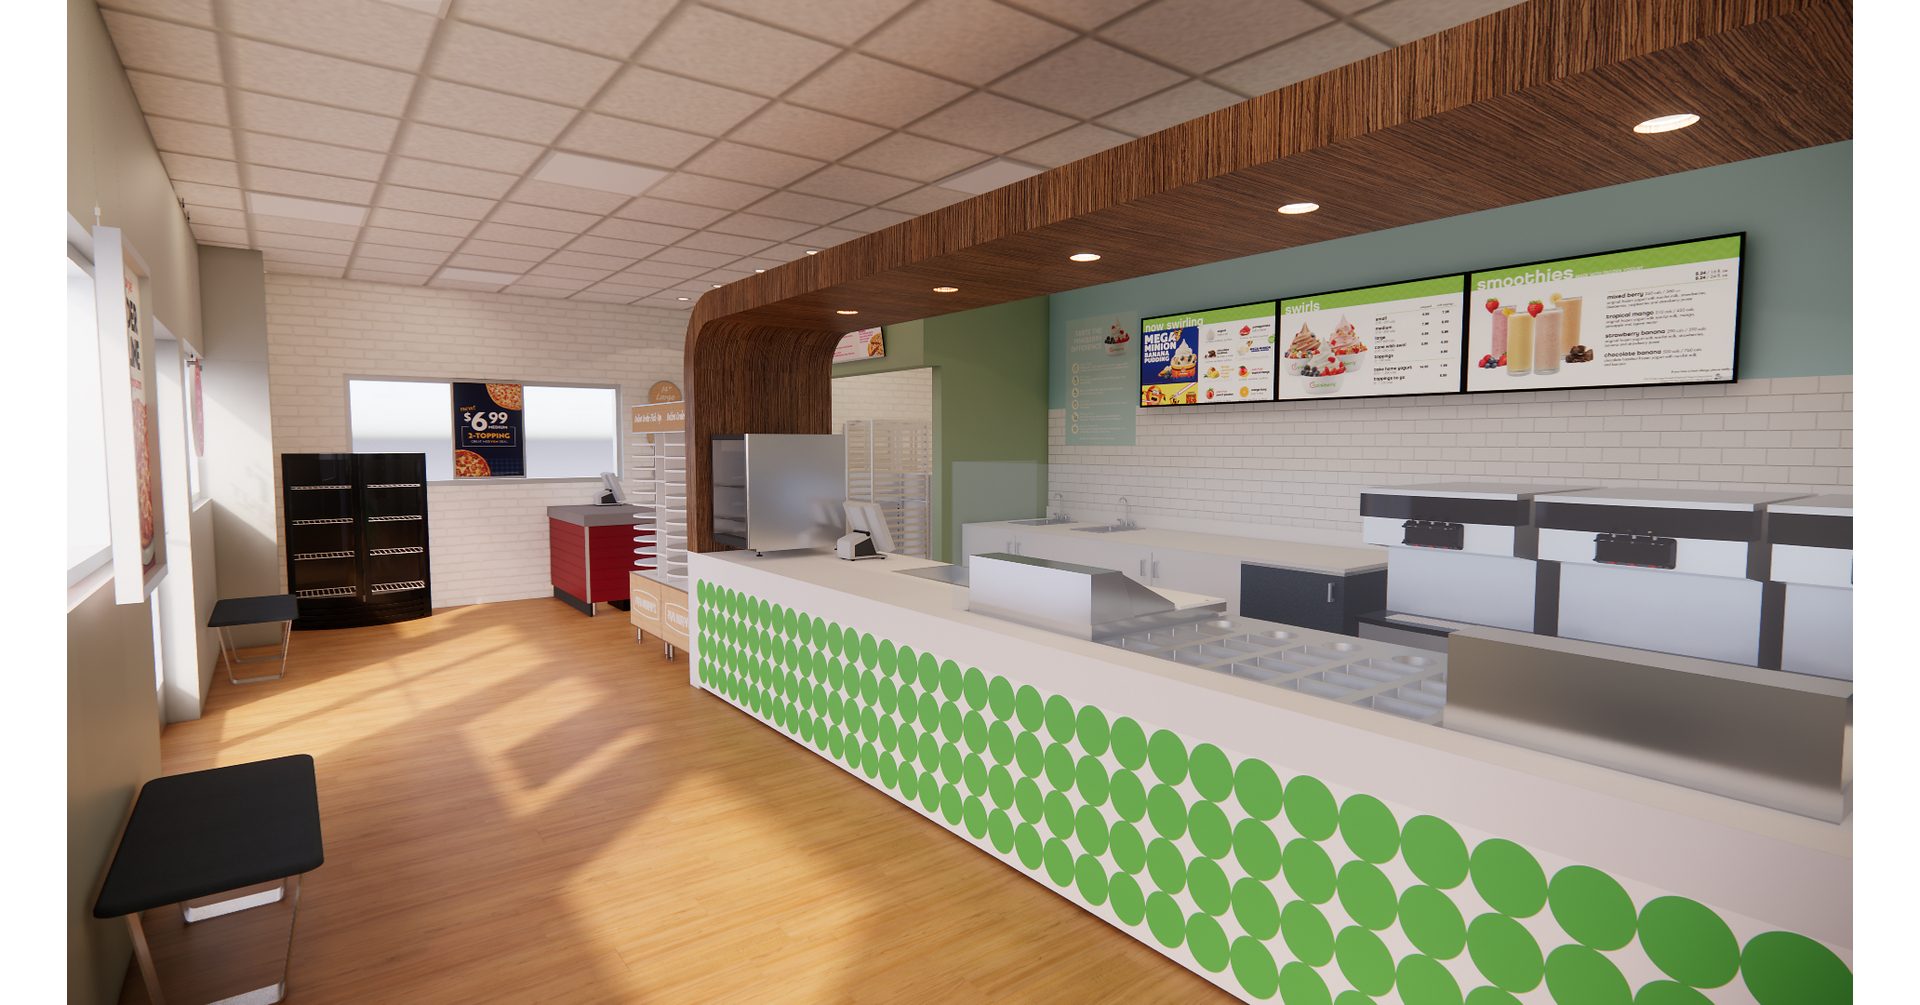
Papa Murphy's signed three franchise agreements to expand its co-brand concept with Pinkberry into Sunriver, Oregon; Santa Fe, New Mexico; and West Haven, Utah. The model combines take-and-bake pizza and frozen yogurt, with franchisees citing shared overhead, cross-trained labor, and seasonal demand as potential benefits. Sunriver is expected to open in early November, while West Haven is scheduled for summer 2027; the announcement provides a modest franchise-growth signal but no financial results or sales projections.
Analysis
The investment signal is franchisee willingness to test a shared-footprint format, not yet evidence of incremental system sales or improved returns. For MTY, the economic upside depends on whether incremental Pinkberry sales exceed added equipment, inventory, training and operating complexity while genuinely reducing occupancy and labor costs. Cross-training may lower staffing friction, but serving two concepts can also widen execution demands; the franchisee’s claimed year-round employment benefit is not proof of stronger store-level cash returns.
Three agreements are too small a sample to establish a repeatable growth engine. The more meaningful read-through is whether existing Papa Murphy’s operators adopt the model: that could support development with less standalone real-estate exposure, but weak unit economics would instead risk diverting franchisee capital from core stores. Other restaurant operators with dessert concepts may face some competitive pressure only if this format demonstrably increases visits or captures additional occasions; there is no evidence yet of that effect.
Near term, the announcement is unlikely to alter MTY’s earnings trajectory absent broader rollout. Over the next 1–3 months, watch for openings, additional signed agreements and franchisee adoption. Over 6–18 months, judge the model on comparable-store sales, franchisee returns and repeat development—not brand-level claims. The contrarian risk is that seasonal complementarity sounds compelling but does not establish consumer demand overlap or cost savings. Falsification: delayed openings, no follow-on commitments, or MTY reporting weaker franchise development or economics.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- No immediate trade on this announcement alone; treat it as a low-confidence, small-scale operating experiment rather than a material MTY catalyst.
- Put MTY on a watchlist for the next 1–3 months: upgrade the thesis only if locations open on schedule and MTY provides evidence of follow-on franchisee commitments or measurable unit economics.
- Before underwriting a long MTY position on the concept, verify store-level sales, incremental Pinkberry investment and operating costs, franchisee payback, and whether co-branded openings are incremental rather than replacing standalone development.
- Reassess negatively if openings slip materially, franchisees do not repeat the format, or management commentary indicates weaker development or franchisee returns.
More News
- Former world No. 1 Jon Rahm's lawyer tells court Spaniard is done with LIV Golf after three seasons
- Anthropic will be 'most ridiculous IPO' of year, analyst says
- Levi Strauss hikes profit guidance after tariff refunds, but its sales outlook is less optimistic
- Weston Family, Fairfax Financial’s Watsa Acquire Boots in $8.9 Billion Deal
- Samsung Q3 profit surges to record high, but misses lofty expectations
- Brazil is having its Argentina moment. How to play it