
Jewelry sales are heating up as Gen Z seeks out ‘little treats’ and the ultra-rich go for chunky gold
Source: MarketWatch
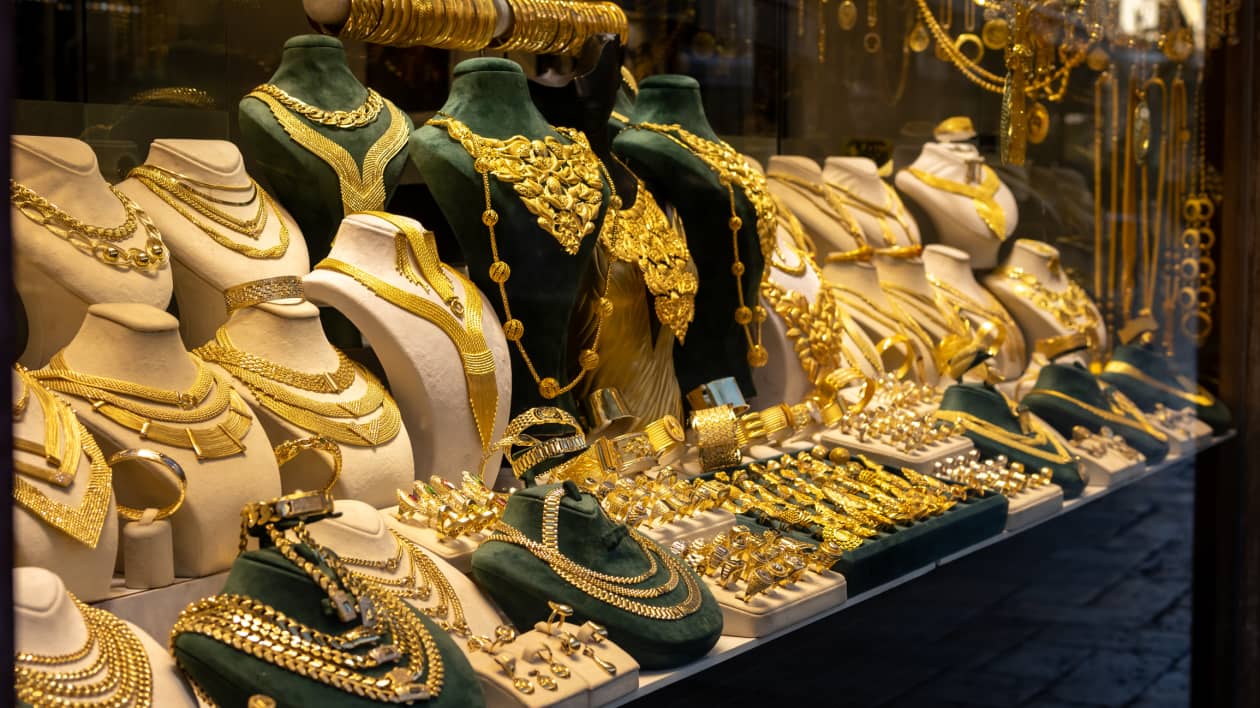
Jewelry sales are emerging as a retail bright spot, with Macy's, Kohl's and Simon Property Group citing the category as a source of strength. Wealthier consumers continue spending despite inflation, while Gen Z demand for affordable 'little treats' and a shift from quiet luxury toward more ostentatious chunky gold pieces support category momentum. The trend is positive for department stores, mall operators and jewelry brands, though it is unlikely to be broadly market-moving.
Analysis
The relevant read-through is not broad discretionary strength; it is category-mix resilience concentrated in high-ticket, low-frequency purchases. For KSS and M, jewelry can support gross-margin dollars and attachment sales, but it is unlikely to offset pressure in apparel, home, or promotional activity because jewelry is too small a share of total revenue. The more durable beneficiary is SPG: productive jewelry tenants raise sales per square foot, support percentage-rent clauses, and improve leasing economics for premium mall space without requiring the landlord to carry inventory risk.
The second-order winner is branded jewelry with controlled distribution and pricing power—Signet (SIG), Pandora (PNDORA DC), Richemont (CFR SW), and Cartier-owner Cie Financière Richemont—rather than department stores acting as multi-brand distributors. Higher gold prices create a split outcome: they raise ticket values and reinforce gold’s luxury signaling, but eventually squeeze retailers and value-oriented jewelers that cannot fully pass through metal costs. Watch whether unit volumes hold as average selling prices rise; nominal category growth driven solely by gold inflation would not justify a rerating.
Over the next 1-3 months, jewelry commentary may modestly improve holiday category expectations and mall-traffic sentiment, but it is not a sufficient catalyst for a KSS or M turnaround. Consensus may over-extrapolate affluent demand into middle-income retail demand; luxury spending is increasingly bifurcated, while department-store customer bases remain exposed to credit stress and promotions. A deterioration in revolving-credit delinquency trends, a sharp gold-price spike, or holiday guidance that shows jewelry strength failing to lift consolidated gross margin would falsify the constructive read-through.
For 6-18 months, the key question is whether conspicuous luxury represents a sustained replacement cycle or a short-lived fashion rotation. If branded operators retain full-price sell-through while department stores increase markdowns elsewhere, the trade is long premium brands and high-quality mall real estate, not long the department-store complex. This article alone is low-impact and does not establish a standalone directional trade in KSS or M.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Ticker Sentiment
Key Decisions for Investors
- Maintain/consider a 3-6 month long SPG versus short KSS pair: SPG monetizes tenant-category productivity with lower inventory and markdown exposure; use a 10-12% adverse spread stop, with upside dependent on holiday leasing/traffic data confirming premium-tenant sales momentum.
- Put SIG on a holiday watchlist rather than chase immediately: initiate only if comparable-store sales and gross margin show unit demand holding alongside higher average selling prices. A 5-8% post-results pullback with maintained guidance offers a cleaner entry than a sentiment-driven pre-earnings bid.
- Avoid treating jewelry momentum as a broad long-M or long-KSS signal. Require evidence that category strength lifts consolidated gross margin or raises annual guidance; absent that, any rally is more likely multiple relief than a durable earnings revision.
- Monitor gold and consumer-credit data weekly: sustained gold appreciation without retail price pass-through is margin-negative for mass jewelers, while rising card delinquencies would challenge the assumed 'little treats' demand elasticity. These are triggers to reduce jewelry exposure rather than add.
More News
- BOJ expected to hike rates by 25 basis points to fresh three-decade high: CNBC survey
- BOJ set to raise interest rates to 31-year high as inflation risks loom
- Three Big Central Bank Decisions Loom: Evening Briefing Americas
- Iran war increasing inflation, straining US munitions: congressional report
- Attacks on Saudi oil expose Iraqi PM’s struggle to control armed factions
- Oil prices dip as U.S. inventory build offsets M.East supply jitters