
Geely Auto Group feiert ihr Debüt auf dem Pariser Autosalon mit Geely Auto, Lynk & Co und Zeekr
Source: PR Newswire
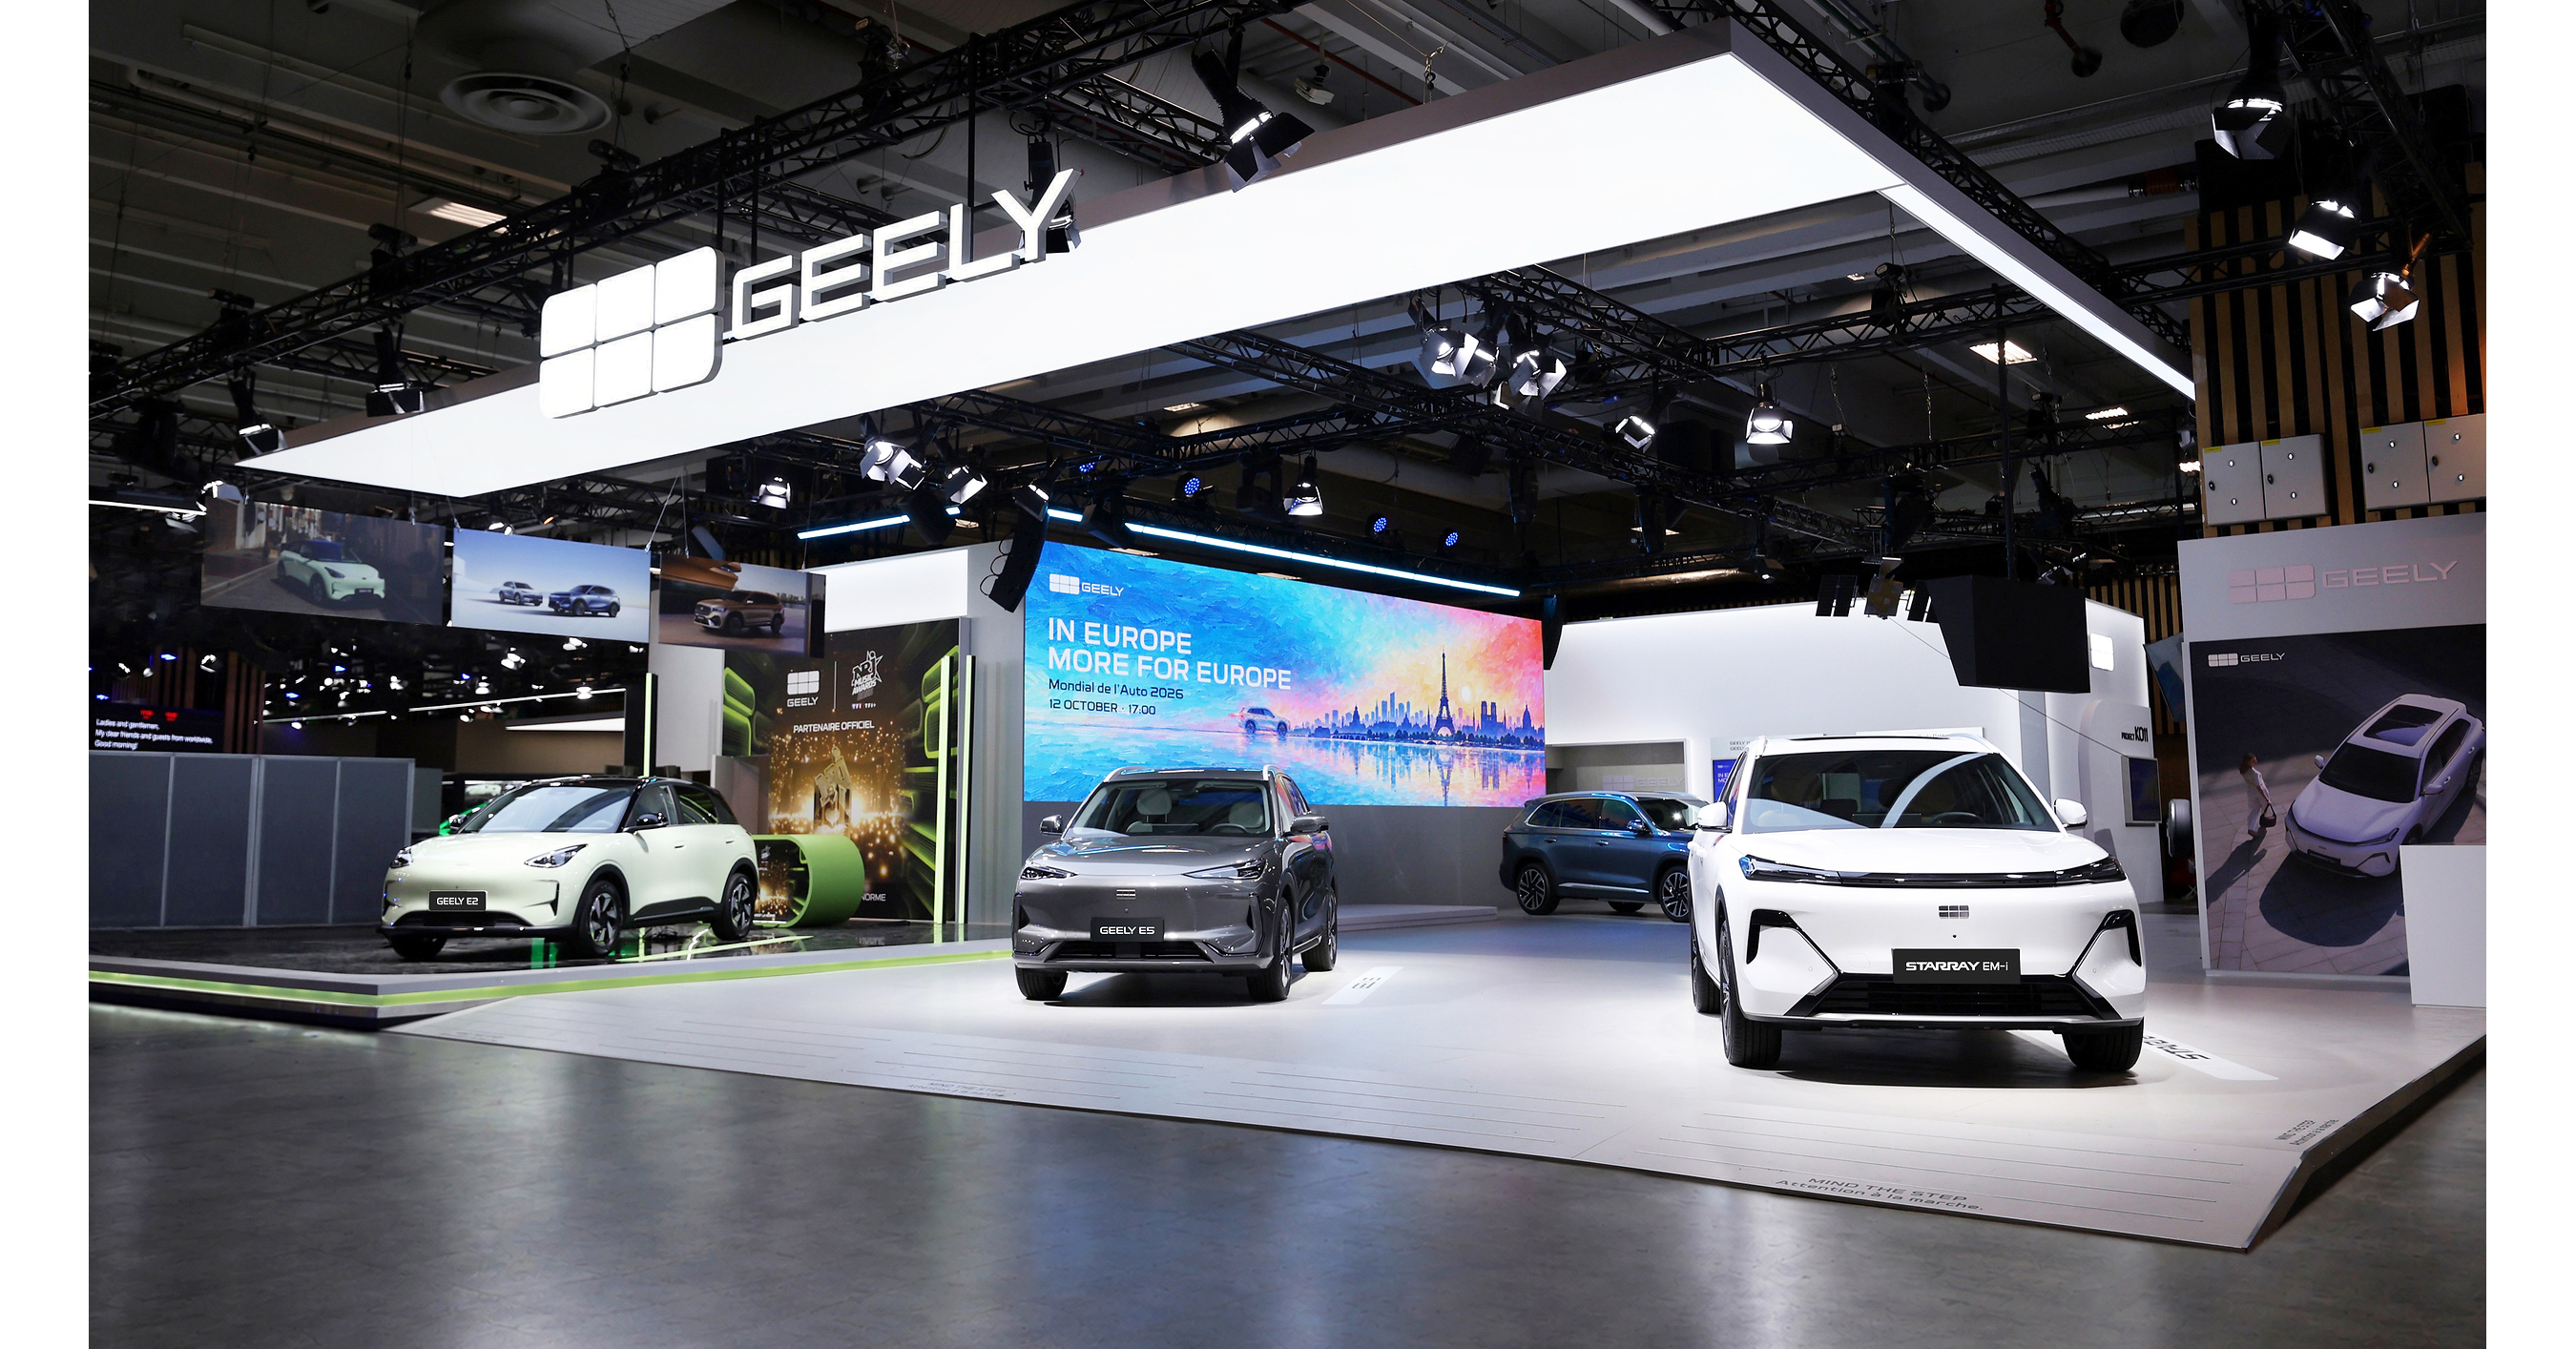
Geely Auto Group made its first group-wide appearance at the Paris Motor Show, highlighting the Geely Monjaro EM-i, Lynk & Co 07GT and Zeekr 9X as it expands across European market segments. Sales by the three brands in Europe exceeded 10,000 units in September 2026 for the first time; worldwide sales reached 2,235,481 units from January through September, while sales outside mainland China rose 169% year over year to 797,670. Zeekr 9X orders are open, with deliveries expected to begin in January 2027; first Zeekr 7X deliveries of the new version are planned for Q1 2027.
Analysis
The investable signal is not the show-floor breadth but whether Geely can convert European demand into profitable, repeatable retail sales. A 10,000-unit monthly run rate across three brands is an encouraging distribution proof point, but without country mix, registrations versus wholesale deliveries, pricing, incentives, or contribution economics it does not establish share gains or attractive returns. The launches may also create brand overlap: Geely, Lynk & Co, and Zeekr could compete for the same customers, forcing higher marketing spend or discounting rather than expanding the addressable market.
Near term (days to 1–3 months), treat the announcement as sentiment-positive but low-information. The useful catalysts are independent registration data, order books and realized pricing for the new models, plus evidence that local service capacity keeps pace. The Zeekr 9X’s planned 2027 deliveries make this more a forward-order and execution test than a current earnings catalyst. Over 6–18 months, the key swing factors are warranty/service costs, residual values, dealer or direct-sales economics, and whether European production or sourcing changes the exposure to trade-policy risk. A poor residual-value trajectory could impair leasing demand across the brands, even if initial deliveries look strong.
Contrarian read: investors may over-credit a large product portfolio as proof of durable competitive advantage. Incumbents such as Volkswagen, Stellantis, and BMW face incremental competition, but Geely’s expansion also raises the cost of establishing three distinct brand propositions. Without verified unit economics, there is no clean directional equity trade; the release alone does not justify shorting incumbents or extrapolating global volume growth into European profitability.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.40
Key Decisions for Investors
- No event-driven position on the announcement alone. Put Geely’s European activity on watch and verify monthly country-level registrations, retail-versus-wholesale mix, transaction prices, and incentive intensity before sizing a trade.
- For the next 1–3 months, monitor order conversion and delivery timing for the Zeekr 9X and 7X, alongside independent registration data. Slippage, discounting, or weak registrations would falsify the near-term demand thesis.
- Over 6–18 months, track warranty/service expense, residual values and leasing availability. Deteriorating resale values or rising incentives would indicate that volume is being purchased at the expense of brand economics.
- Treat trade-policy exposure as a diligence item, not an assumed headwind or tailwind: verify model-level production origin, customs classification and applicable EU measures before expressing a relative-value view against Volkswagen, Stellantis, or BMW.
More News
- South Korean carmaker Hyundai plans 'strategic' investment of $15.5 billion in India by 2032
- Namibia battles cattle disease outbreak as EU suspends several meat imports
- Applied Materials’ $5 billion AI lab aims to cut chip development time in half—and restore Silicon Valley’s edge
- Wells Fargo CFO on Earnings, Deals, Consumer Strength
- Bank of America hit with more than $1.2 billion in penalties over money-laundering violations
- Meta’s Muse models reach the AI frontier—and kill any hopes to ‘pace’ it
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Tools for Independent Research Firms: A Publishing System
- Weekly Update: Options, Earnings Call Transcripts, AI Chat, Bookmarks & More