
ROSEWOOD HONG KONG WURDE ZUM ZWEITEN MAL IN FOLGE ZUR NO.1 IN THE 50 BEST HOTELS 2026 ERNANNT
Source: PR Newswire
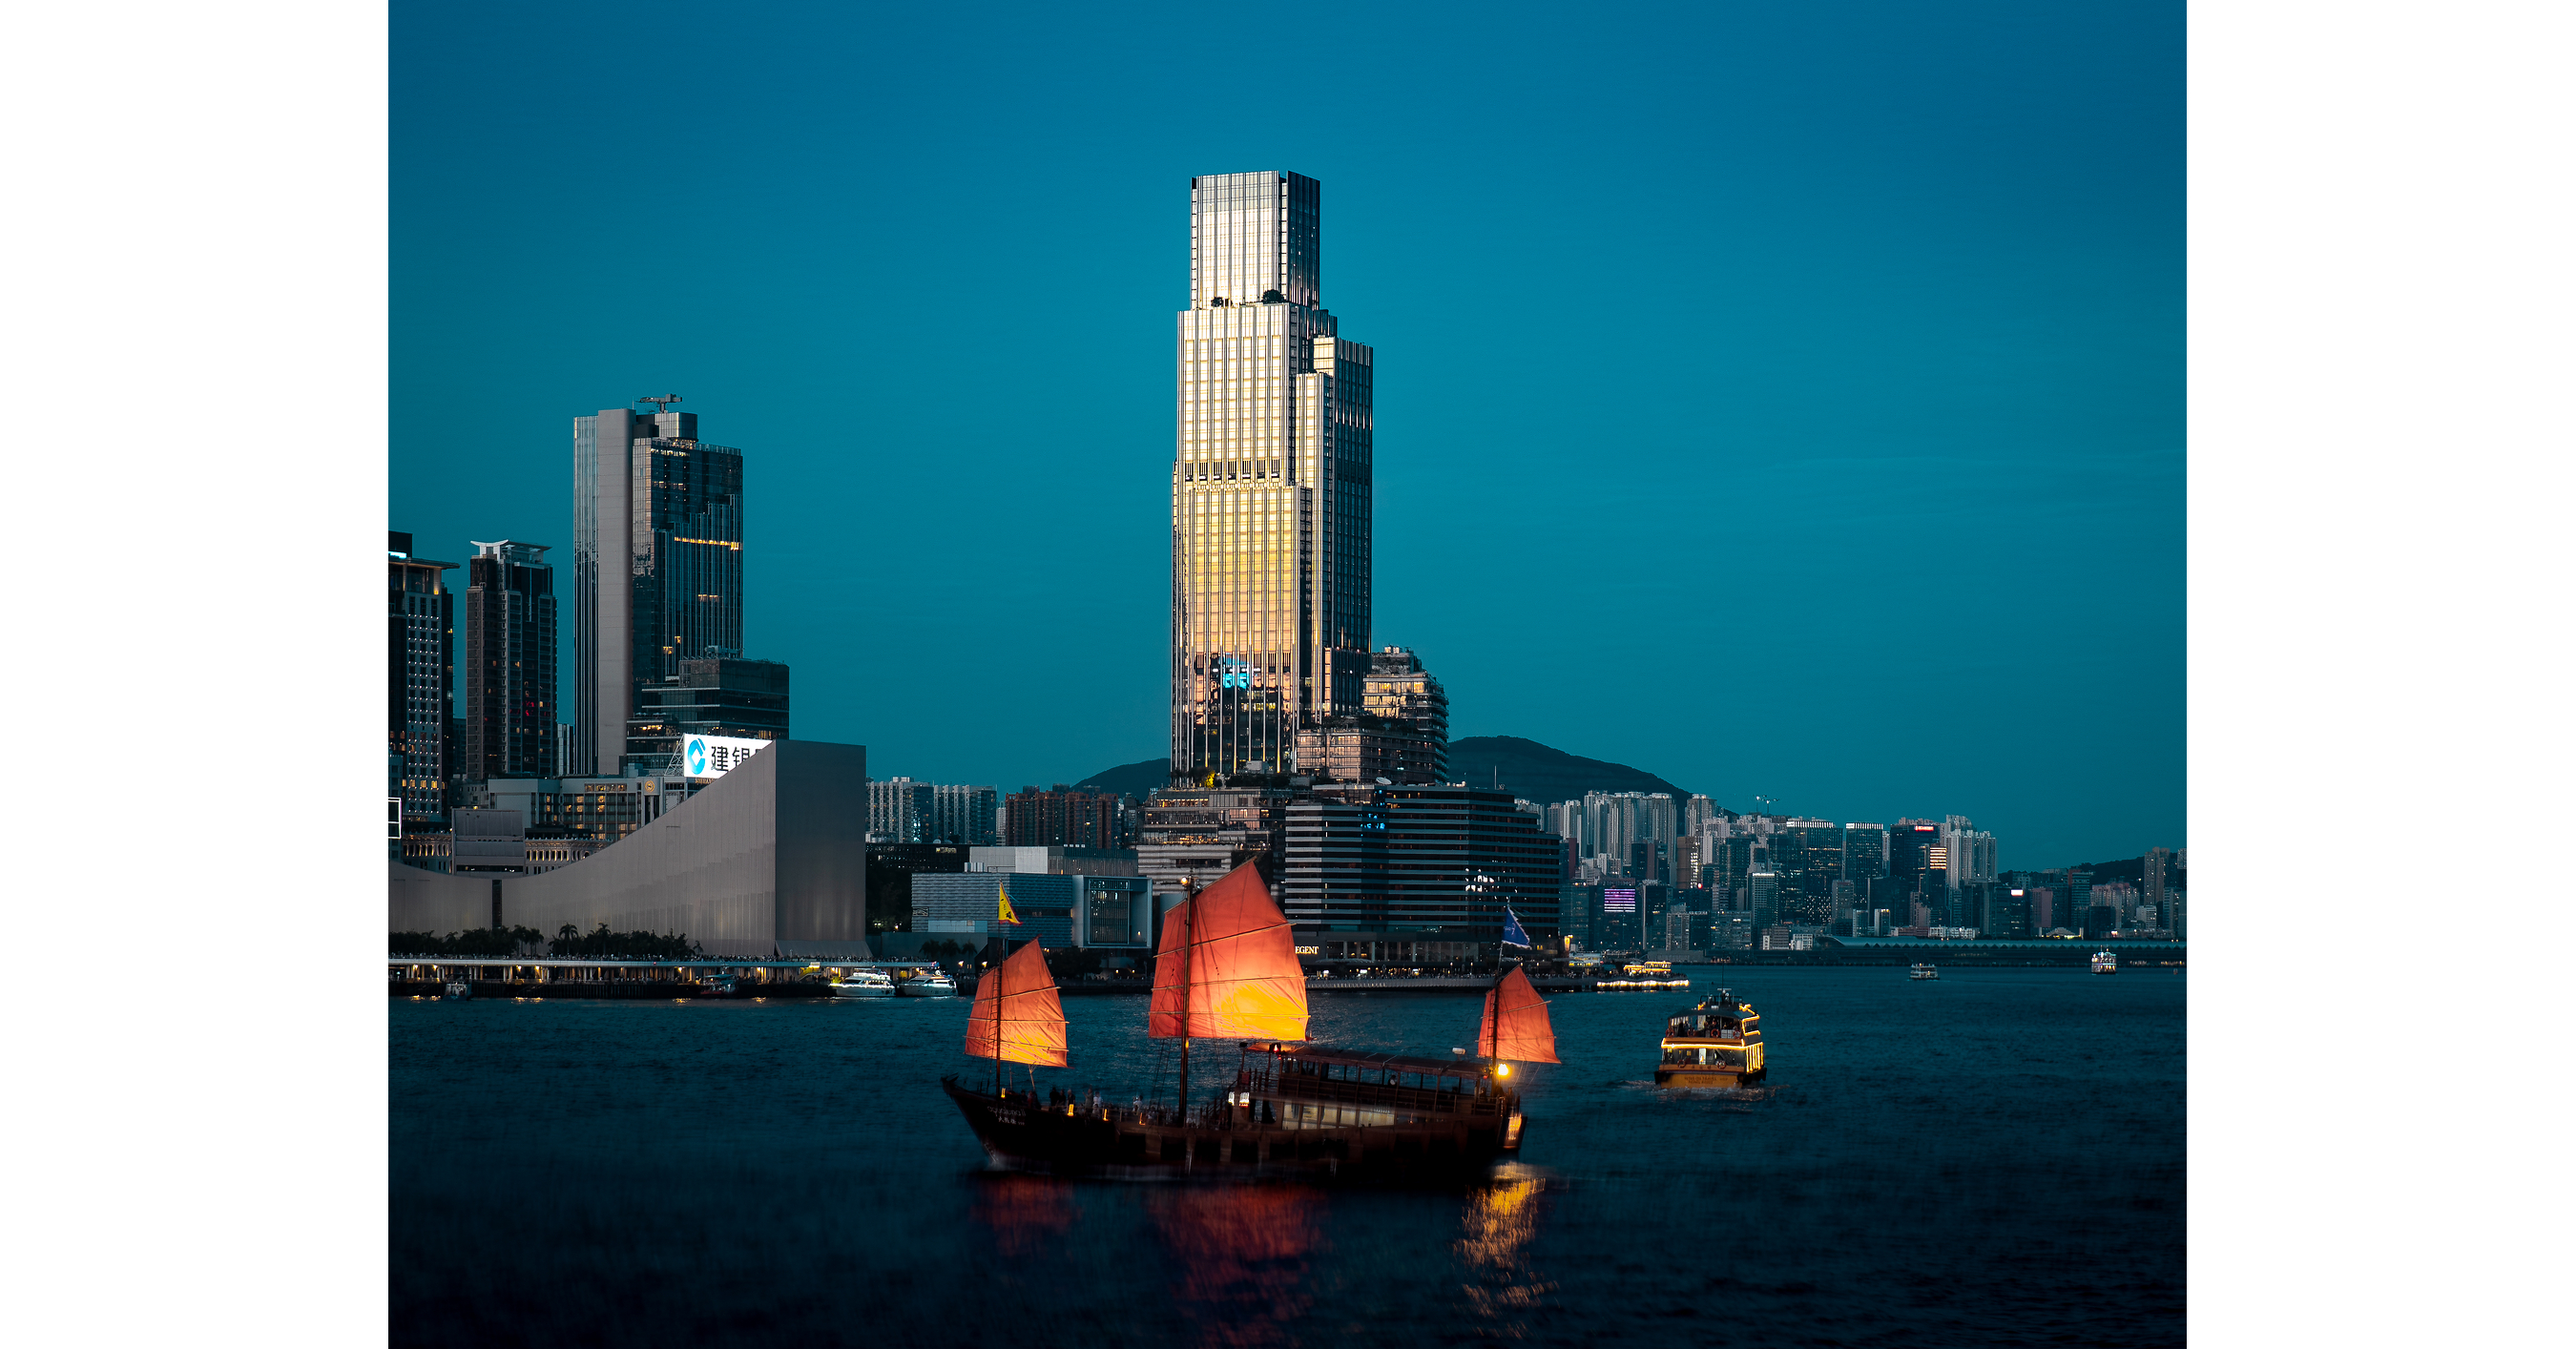
Rosewood Hong Kong was named The World's Best Hotel 2026 for the second consecutive year, retaining its No.1 ranking after also leading in 2025. The 50 Best Hotels list recognized properties across 22 destinations and six continents, with Europe leading representation at 21 hotels and Asia contributing 18. Other notable winners included Passalacqua at No.5 as Best Boutique Hotel and Patina Osaka at No.33 as Best New Hotel.
Analysis
This is primarily brand-validation rather than an earnings catalyst. Rosewood’s recognition modestly strengthens pricing power and affluent-traveler awareness for its private owner, but it does not create a direct listed-equity read-through for H. Hyatt’s more investable implication is indirect: luxury demand remains concentrated in destination urban and resort properties, favoring asset-light operators with high-end pipeline exposure over broad-based, midscale lodging beta.
RACE gains marginal halo value from association with ultra-luxury hospitality, but the economic effect is immaterial relative to vehicle deliveries, mix, and order-book conversion. The more relevant second-order signal is that premium experiential spending remains resilient; that supports card-spend volumes for AXP, particularly international travel-and-entertainment categories, if affluent consumers continue substituting experiences for discretionary goods.
Near term, this should not move any of the named stocks. Over 1-3 months, AXP’s travel-and-entertainment billed-business growth and cross-border spending trends are the verification points; a deceleration would show that awards-driven luxury visibility is not translating into spend. Over 6-18 months, sustained luxury occupancy and ADR expansion could support multiple dispersion in favor of Marriott/Hyatt luxury exposure, but only if RevPAR gains exceed wage, insurance, and property-cost inflation.
Contrarian view: the accolades may reflect supply scarcity at trophy properties rather than a broad luxury-travel acceleration. High-end hotel ADR has already recovered sharply in major leisure destinations; further rate increases can shift demand toward premium vacation rentals, private clubs, and luxury cruises. No standalone trade is warranted from this release.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Ticker Sentiment
Key Decisions for Investors
- No immediate position change in H or RACE; treat the news as non-price-sensitive marketing validation rather than a fundamental catalyst.
- Maintain AXP on a 1-3 month watch: add only if reported travel-and-entertainment billed-business growth and international card spend accelerate versus the prior quarter. Falsifier: two consecutive monthly decelerations in T&E spending or rising credit-loss provisions.
- For luxury lodging exposure, monitor H versus MAR as a relative-value screen after upcoming earnings: favor the operator showing luxury RevPAR growth above labor-cost growth and intact fee-revenue guidance. Do not initiate based on award rankings alone.
- Use RACE as a macro confirmation indicator, not a hospitality trade: retain existing exposure only if order intake and pricing/mix remain resilient; luxury travel recognition does not offset risk from delivery misses or weaker regional demand.
More News
- Trip.com swings to Q2 loss after $763 million antitrust penalty
- Saudi-led coalition intercepts drone headed for Mecca
- Malaysia talks to rival airlines as it monitors AirAsia's financial health, sources say
- Trip.com ADR earnings beat by ¥1.15, revenue topped estimates
- Lennar earnings outlook: two consecutive misses and a stock near multi-year lows
- Ryman Hospitality Properties declares $1.20 dividend, sets October payment