
Civista Bancshares Names Mark J. Sams Senior Vice President and Chief Revenue Officer
Source: PR Newswire
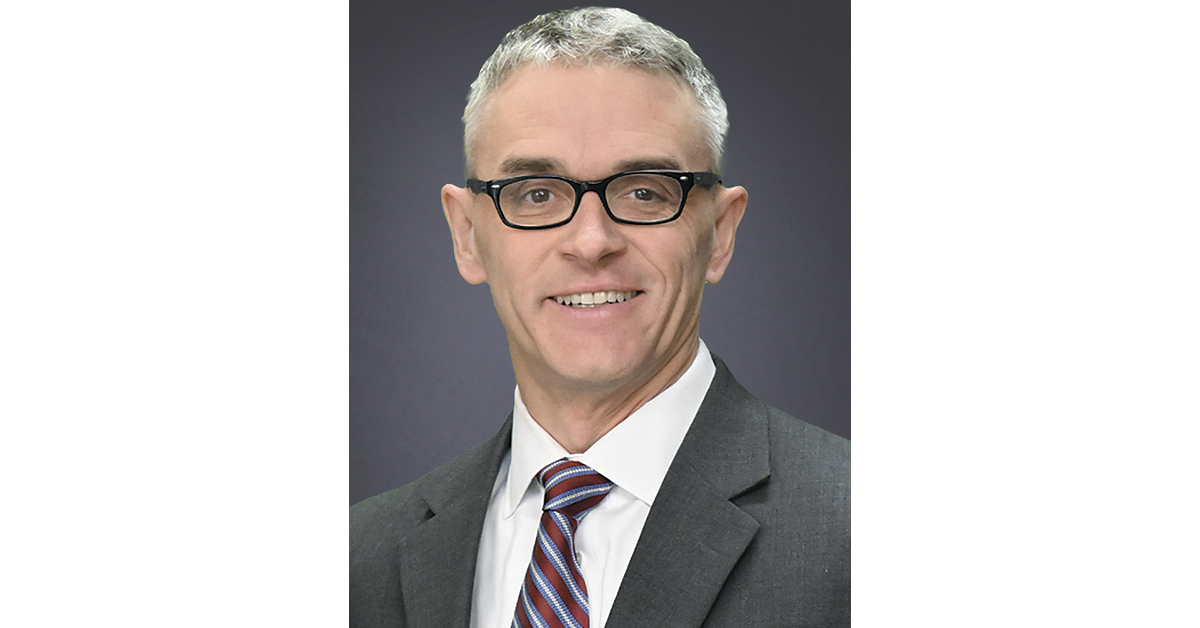
Civista Bancshares appointed Mark J. Sams as Senior Vice President and Chief Revenue Officer, placing Treasury Management, Wealth Management, Private Banking, Healthcare Solutions and strategic growth initiatives under his leadership. Sams has led these businesses since January 2026 and brings more than 25 years of banking experience; the announcement signals continuity in Civista's growth strategy rather than a material change to financial outlook. Civista is a $4.3 billion financial holding company with 44 banking locations.
Analysis
This is not an investable fundamental catalyst by itself: the role largely formalizes oversight of businesses already under the executive's remit, with no disclosed production targets, incentive redesign, hiring plan, or revenue guidance. In a thinly traded community-bank stock, the likely near-term effect is limited to modest governance signaling rather than an earnings-estimate revision.
The relevant 1-3 month question is whether centralized revenue accountability produces measurable cross-sell in treasury management, private banking, and healthcare verticals without weakening underwriting. These fee-oriented lines can diversify net-interest-income sensitivity, but only matter if noninterest income growth outpaces associated personnel and technology costs; the bank's next earnings release should provide the first verifiable evidence. A stronger commercial deposit-gathering franchise would also reduce funding-cost pressure, potentially supporting net interest margin if rate competition remains elevated.
Over 6-18 months, execution risk is asymmetric for CIVB: an aggressive push into specialized commercial relationships or nationwide equipment finance could raise criticized assets before reported revenue benefits emerge. The market should discount management rhetoric until there is evidence of stable deposit betas, improved fee-income mix, and no deterioration in charge-offs or the allowance-to-loan coverage ratio. There is no compelling relative-value read-through to larger regional banks from this announcement.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Ticker Sentiment
Key Decisions for Investors
- No new directional position in CIVB on the announcement; treat it as a monitoring event rather than a catalyst, given the absence of financial targets or independently verifiable operating changes.
- For existing CIVB exposure, retain only if the next two quarterly reports show positive core fee-income growth and stable or improving net interest margin while nonperforming assets and net charge-offs remain contained; a meaningful deterioration in either credit metric falsifies the revenue-growth thesis.
- Set an earnings watch item for commercial deposit growth, treasury-management fee growth, wealth/private-bank assets, and the efficiency ratio over the next 1-3 months. Consider adding only after evidence that incremental revenue exceeds operating-expense growth.
- Avoid extrapolating the title change into a sector trade versus regional-bank ETFs such as KRE; funding costs, loan-loss provisioning, and local commercial real-estate exposure remain materially more important drivers of CIVB valuation.
More News
- Can Trump Oust Powell From the Fed Board? What to Know
- See 'Skittishness' Around Credit: Annie Seelaus
- $8.2B acquisition validates AI-picked chip stock: +20% since June
- Nike Warns Sales Slump Will Worsen This Fiscal Year
- Nuveen CEO on Schroders Deal, Plans for Combined Company
- Broadcom to lend Anthropic up to $42 billion to lease its chips, filing says
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- 2026 Global Markets Outlook: Asset Allocation After the Great Disconnect
- Fintool Alternatives After the Microsoft Acquisition