
Sceye's Stratospheric Platform Re-enters United States After Record-Breaking Roundtrip Stratospheric Flight Between U.S. and Japan
Source: PR Newswire
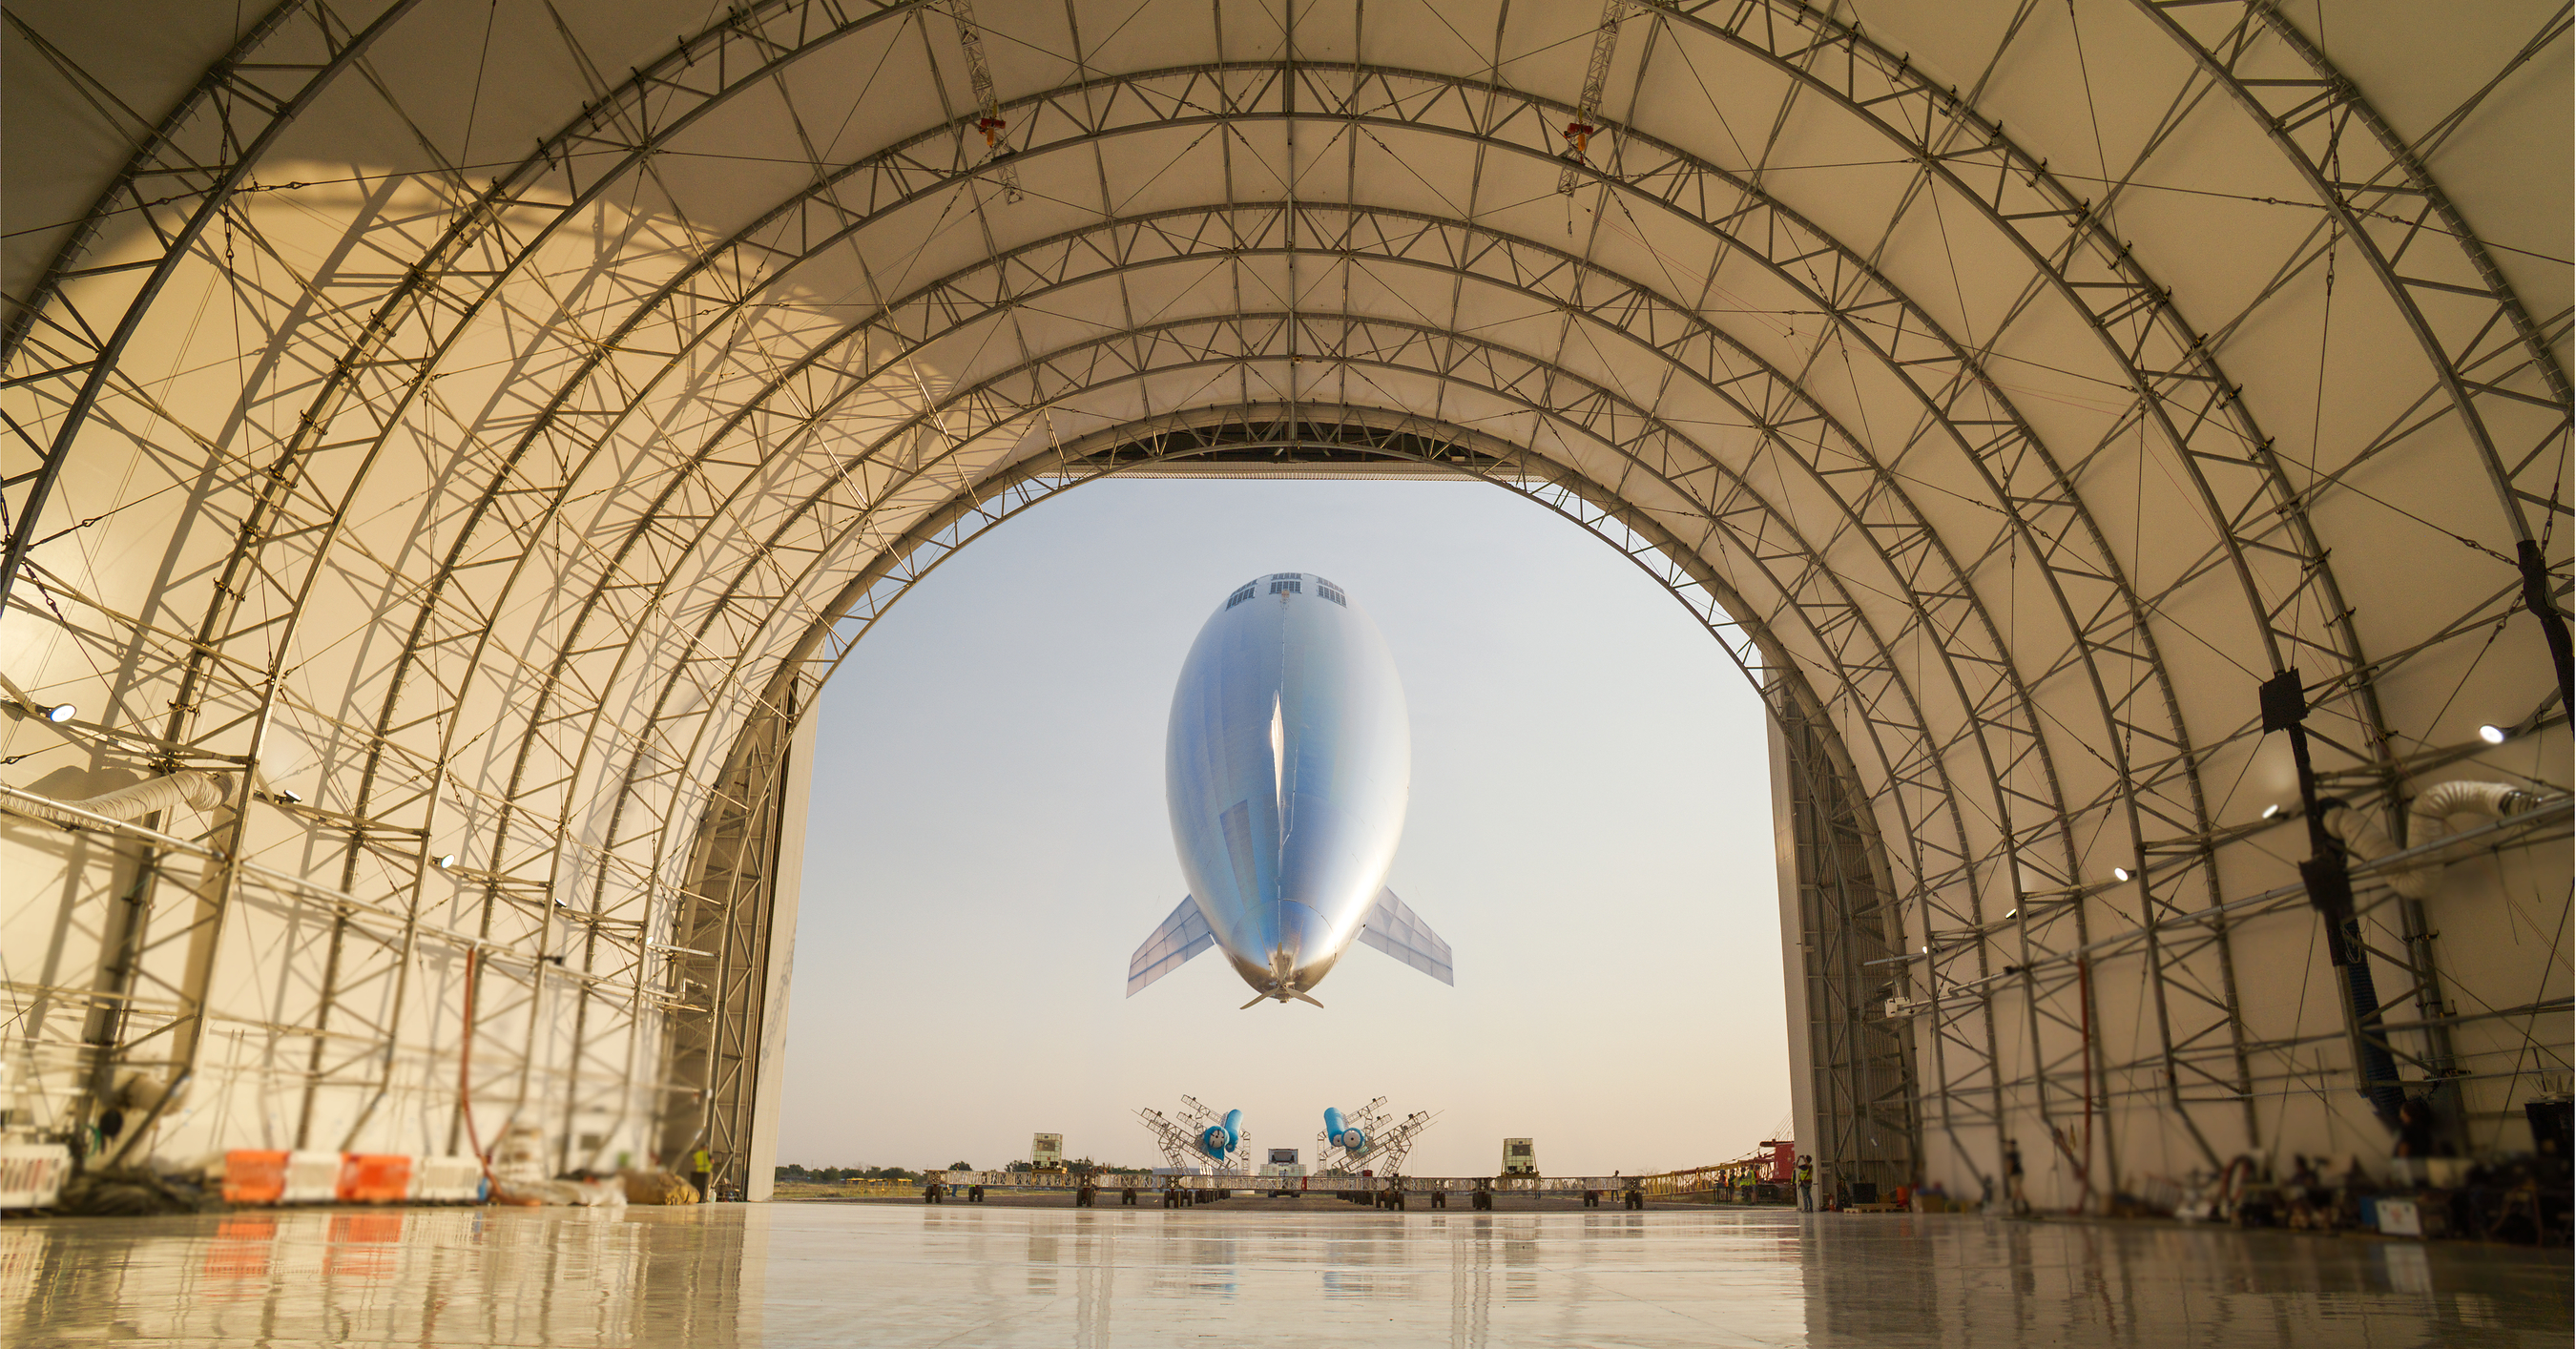
Sceye's ST1 high-altitude platform system completed a nearly 30,000 km month-long flight from New Mexico to Japan and back, including more than seven days in Japanese-managed airspace and station-seeking accuracy within a 5 km radius. In partnership with SoftBank, the platform demonstrated mobile broadband, voice, video, emergency messaging and drone communications from 16.5-17 km altitude, while onboard edge processing achieved a 68 ms average round-trip response time—more than 40% lower latency than cloud-based processing. The trial advances commercial deployment of Sceye's stratospheric "cell tower in the sky," which the company says could cover an area equivalent to roughly 500 terrestrial towers per platform.
Analysis
The investable implication is not a near-term earnings event but a potential architecture shift in rural coverage, disaster recovery, and private-network edge computing. If high-altitude platforms prove durable across seasons and regulators permit commercial spectrum use, they could reduce the marginal cost of coverage in low-density markets—pressuring the long-tail tower-build opportunity for terrestrial equipment vendors while expanding addressable edge-network demand for Nokia (NOK), Ericsson (ERIC), and specialized radio/network integrators. The more likely initial use case is carrier network resilience rather than broad replacement of towers, which makes the technology complementary to incumbent mobile operators.
SoftBank Corp. (9434.T) has strategic optionality, but the direct financial contribution is immaterial until commercial unit economics, spectrum rights, and fleet manufacturing costs are disclosed. The company-reported latency and network-performance claims are technically encouraging but not independently sufficient to establish availability, payload throughput under congestion, maintenance cycles, or cost per covered subscriber—the metrics that determine whether HAPS competes with terrestrial densification or satellite backhaul. Over the next 1-3 months, watch for paid pilot contracts, Japanese regulatory filings, and third-party network-performance data; absent these, the announcement is unlikely to alter listed-equity estimates.
The contrarian read is that HAPS may challenge satellite connectivity narratives more than tower economics. For direct-to-device coverage, AST SpaceMobile (ASTS), Globalstar (GSAT), and Iridium (IRDM) carry valuations partly dependent on scarce non-terrestrial connectivity capacity; a credible, lower-latency airborne alternative could eventually cap pricing and multiple expansion in specific regional or emergency-use cases. Conversely, HAPS has a concentrated regulatory and weather/operational-risk profile, so it is unlikely to displace space-based networks for global, maritime, or remote-ocean coverage over the next 6-18 months.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.70
Key Decisions for Investors
- No immediate directional trade on 9434.T: treat this as a watch catalyst rather than an earnings catalyst. Reassess only if SoftBank discloses paid deployments, fleet capex, spectrum authorization, and target revenue contribution; without these, the position is dominated by its broader telecom and investment-portfolio drivers.
- Establish an alert on ASTS, GSAT, and IRDM for commercial HAPS contract announcements or Japanese spectrum approvals over the next 3-6 months. Consider a modest relative-value short basket versus a broad communications-services hedge only if evidence shows HAPS cost per covered user is competitive; the thesis is falsified by satellite exclusivity agreements, superior global coverage economics, or absence of repeatable HAPS operations.
- Monitor NOK and ERIC for carrier-led HAPS trials and edge-core integration orders over 6-18 months. A long bias is warranted only on disclosed equipment/software backlog, since pilot activity alone is too small to affect revenue; failure to convert pilots into multi-year carrier contracts would invalidate the incremental-demand thesis.
More News
- Saudi Arabia intercepts missiles and drones as fighting with Houthis rages
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Israelis hold final rally against Netanyahu ahead of what may be the most consequential election in the country’s history
- 5 big analyst AI moves: ’Uniquely catalyst-rich’ months ahead for SpaceX
- Saudi Arabia intercepts drones and missiles as fighting with Yemen’s Houthis continues
- Qatar official calls for peace and security to boost trade, investment
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Build an Automated Research Process for a Fund
- Weekly Update: AI-Powered Report Editing, Investor Relations, and Enhanced Search