
Angel Aligner Upgrades Torque Ridges to "Pressure Points" in Europe
Source: PR Newswire
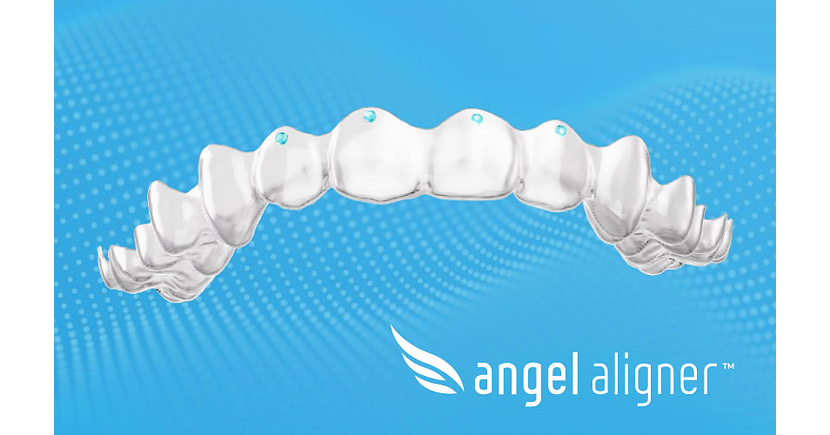
Angelalign Technology launched its Pressure Points orthodontic aligner feature in Europe, replacing Torque Ridges and targeting more predictable torque correction. The single-pressure-point configuration increases tooth surface contact by 25% and is designed to improve digital accuracy and scalability versus clinician-made dimples. The company plans global distribution and future configurations for rotation and intrusion, but disclosed no revenue or financial guidance impact.
Analysis
This is unlikely to alter Angelalign's near-term revenue or valuation without evidence that the feature improves case-completion rates, reduces refinements, or supports higher average selling prices. The economic value sits in orthodontist workflow: if digital force-placement reduces chair-time adjustments and mid-course corrections, it can raise provider loyalty and lower Angel's clinical-support burden. That would matter over 6-18 months, but a single regional feature release is not independently verifiable evidence of either outcome.
The more relevant competitive read-through is that Angel is targeting a clinical-performance gap rather than competing solely on price. That is directionally challenging for Align Technology (ALGN), Straumann (STMN.SW), and Dentsply Sirona (XRAY), but only if adoption converts into measurable share gains among specialist orthodontists; general-practitioner adoption would have less strategic value and likely require discounting. In Europe, reimbursement fragmentation and clinician switching costs make a rapid share shift improbable, limiting the 1-3 month catalyst path.
Consensus may over-credit product announcements in a category where clinical claims often diffuse quickly and are difficult to monetize. The key falsifier for a constructive Angel thesis is not feature rollout breadth, but subsequent disclosure of European case volumes, refinement rates, retention/pricing, and gross-margin progression. Absent those data, this should be treated as a product-roadmap signal rather than an earnings catalyst.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Key Decisions for Investors
- No immediate directional trade in 6699.HK; the reported impact is too small and there is no disclosed pricing, uptake, or clinical-outcome data to underwrite a near-term earnings revision.
- Set a 1-2 quarter watch on 6699.HK European case-volume growth versus company-wide growth, ASP, and gross margin. Consider a long only if Europe accelerates meaningfully without a deterioration in gross margin, indicating product-led mix rather than promotional share capture.
- Monitor ALGN, STMN.SW, and XRAY for commentary on refinement rates, orthodontist retention, and European clear-aligner pricing during the next earnings cycle. A sustained Angel share gain paired with competitor price concessions would support a relative long 6699.HK / short ALGN basket, but not before confirmation.
- Risk control for any future Angel long: exit if management expands feature availability without improved case growth or if gross margin declines, as that would imply the innovation is functioning mainly as a sales incentive rather than a differentiated clinical product.
More News
- Anthropic warns government attitudes may hurt customer ties, IPO prospectus shows: Reuters
- FAA says Boeing 737 Max software glitch not a flight-safety issue
- Your health insurance premiums may take a big jump in 2027 — here's why
- Anthropic to invest $100 million to train AI engineer talent
- Paramount and Warner Bros. Discovery to Merge Into Skydance (SKYD). Will Skydance Achieve David Ellison’s "Quality Storytelling" Vision?
- Big Pharma turns to China for new drugs as patent cliff drives multibillion-dollar deals
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Options, Earnings Call Transcripts, AI Chat, Bookmarks & More
- AI Tools for Family Offices: A Stack by Decision Type