
Intel: Time For A Very Serious Watch
Source: seekingalpha.com
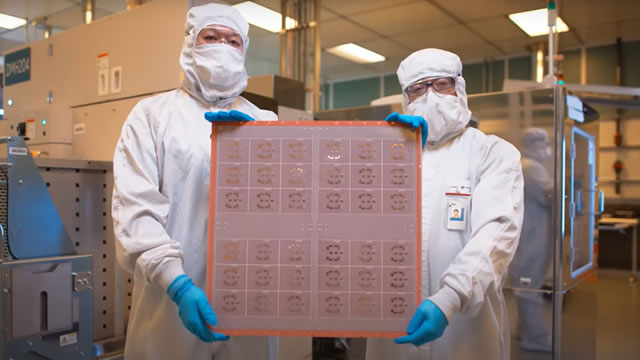
Intel reported results and guidance in line with the author's expectations. Server business DCAI generated $7.3B in revenue, up 80% year over year, offsetting weakness in the client segment. Management targets long-term gross margins above 50%, citing 18A and 14A process advancements and major synergies expected by 2028.
Analysis
An in-line print limits the near-term re-rating case: the server strength is already doing the work of cushioning client weakness, but without a surprise it is not, by itself, evidence of durable earnings revisions. The key question is mix-adjusted profitability. If incremental server revenue carries weaker economics than expected, revenue growth could coexist with limited gross-margin progress; if it improves utilization and absorbs fixed costs, it could help fund the process roadmap. Verify segment margins and cash investment before treating growth as earnings quality.
Over 1–3 months, watch whether server momentum persists and whether client demand stabilizes; a reversal in either could expose the offset as less dependable. Over 6–18 months, execution—not the stated long-term margin ambition—is the valuation driver: process yields, ramp timing, customer adoption, and capex discipline. Failure to deliver would leave Intel competing against AMD and Nvidia in products while relying on TSMC and other foundries for a different part of the competitive equation; the consequences depend on product mix and actual manufacturing economics. The 2028 synergy target is too distant to underwrite near-term earnings without milestones.
Contrarian read: the bullish narrative may over-credit revenue growth and roadmap claims while underweighting the time and capital required to turn process progress into consolidated margin improvement. Conversely, an in-line quarter may also mean the market is not paying for further server upside; there is no valuation or price-action data here to establish that. Net: modestly constructive fundamentals, but no high-conviction entry signal.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- Do not chase INTC solely on the server growth narrative after an in-line report; absent price and valuation data, keep exposure neutral pending evidence of earnings conversion.
- Treat any add as conditional: look for sustained server momentum alongside improving or resilient segment economics and credible gross-margin guidance. Reassess if server growth decelerates or client weakness deepens.
- Track 18A/14A yield, ramp timing, customer adoption, and capex against milestones over the next 6–18 months. Delays, weaker utilization, or rising investment without margin progress would falsify the execution thesis.
- No forced pair trade: monitor AMD and Nvidia for competitive share signals, but do not infer Intel share gains from server-market growth alone.
More News
- Apple's quarter is not perfect. But with enough to like, we raised our price target
- Palantir’s revenue rises 96% to $2.3 billion as investors’ patience rests on a hair trigger
- S&P 500 rises; Apple and Palantir set to report results
- The AI Selloff Meets Election Day
- INTC SHAREHOLDER INVESTIGATION: SueWallSt Notifies Investors of Potential Securities Claims Involving Intel
- Bernstein SocGen cuts Qualcomm stock price target on handset concerns