
Unisound 2026 Interim Results: Revenue Up 38.7% YoY, Token Business Surges 760%, Large-Model Commercialization Accelerates Across the Board
Source: PR Newswire
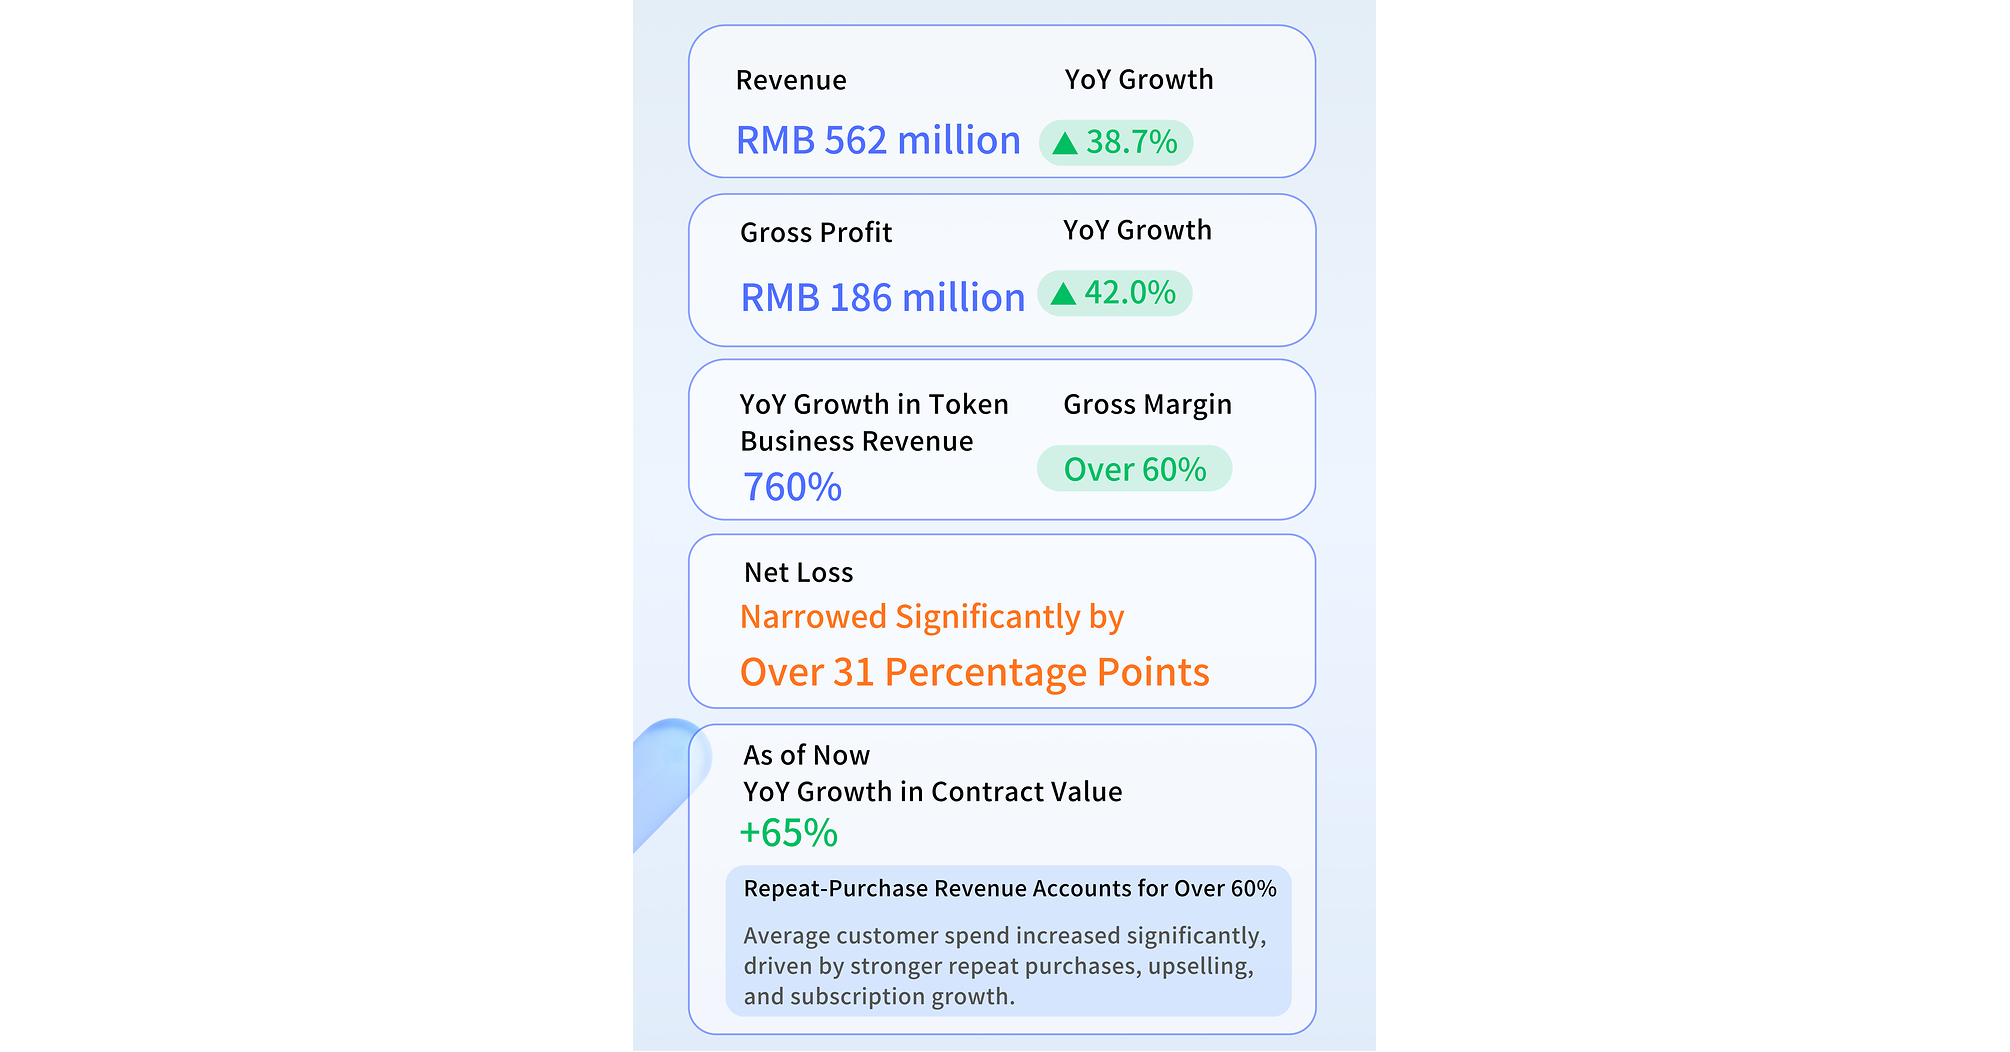
Unisound reported 1H26 revenue of RMB 562m, up 38.7% YoY, with its token business revenue jumping ~760% YoY (gross margin >60%). The company also reported segment traction with Enterprise AI Services revenue of RMB 478m (+35.7% YoY) and Edge AI revenue of RMB 53.8m (+9.2% YoY), while administrative expenses fell 37.8% and the net loss margin improved by over 31pp YoY. Contract value rose 65% YoY to increase visibility, order backlog exceeded RMB 1.5b, and cash reserves are nearing RMB 1.0b as Unisound shifts toward a platform and commercialization-focused model.
Analysis
The investable signal is not the top-line growth; it is the evidence that deployment is becoming repeatable. When AI implementations shift from one-off customization to reusable modules plus usage-based consumption, the economic winner is the vendor with distribution, not necessarily the one with the best model benchmark. That is a constructive read-through for China-listed application-layer names with subscription/usage exposure such as 4Paradigm and, secondarily, iFlytek; it is less helpful for services-heavy software vendors that still depend on manual delivery and low reuse.
The second-order pressure is on pricing power across the China AI stack. If enterprise buyers can standardize agent workflows, cloud and internet giants can bundle inference and model access, which caps standalone monetization and forces smaller vendors to prove gross-margin durability rather than just growth. The next 1-3 months matter most: backlog conversion, cash collection, and Q3 guidance will tell us whether the current momentum is real or just budget timing; over 6-18 months the key variable is whether recurring revenue can become a meaningful share of the mix before cloud bundling compresses margins.
Contrarian view: the market may be overpaying for percentage growth off a still-small revenue base. Token-like revenue at this scale does not yet justify a platform multiple unless the company can show sustained take-rate expansion and lower implementation intensity; otherwise this is still a project business in better packaging. Falsifiers are a slowdown in order intake, margin erosion from inference costs, or evidence that customers are piloting AI but not renewing at higher spend.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.50
Key Decisions for Investors
- Tactically long 4Paradigm (6682.HK) on any post-earnings weakness; use a 1-3 month horizon into the next guidance update. Risk/reward is attractive if the market starts paying for recurring AI software revenue instead of headline growth alone; invalidate the trade if gross margin stalls or growth decelerates below 20%.
- Pair trade: long 4Paradigm (6682.HK) vs short SenseTime (0020.HK). The thesis is better monetization quality and less reliance on model-capex optics; the pair should work if investors rotate from 'AI story' to 'AI cash flow.' Cover the short if sector beta, not fundamentals, drives the move.
- Buy a small starter position in Kingsoft Cloud (3896.HK / KC) only if the next quarter shows higher AI inference utilization without incremental margin dilution. This is a higher-beta read-through trade; upside is a rerating on evidence that usage revenue is becoming real, but the position should be cut if cloud bundling compresses gross profit.
- No direct trade in Unisound itself; treat it as a sentiment/competitive read-through and wait for verification from listed peers' earnings. The alert level is a sharp rise in China AI application contract renewals or backlog conversion over the next 30-60 days.
More News
- Take Five: Bangkok blues
- ‘If nothing is done, it’s almost inevitable’: Ukraine’s Yuriy Ryzhenkov on why steelmaking is on the brink of collapse as Russian bombing intensifies
- Why is LG Innotek stock plunging today?
- TotalEnergies, KKR expand U.S. solar venture with 700 MW addition
- Why is SK Hynix stock sliding today?
- TSMC expected to report sixth straight quarter of record profit thanks to AI boom