
Lennar Celebrates Grand Opening of Cherokee Bend in Moundville, Alabama
Source: PR Newswire
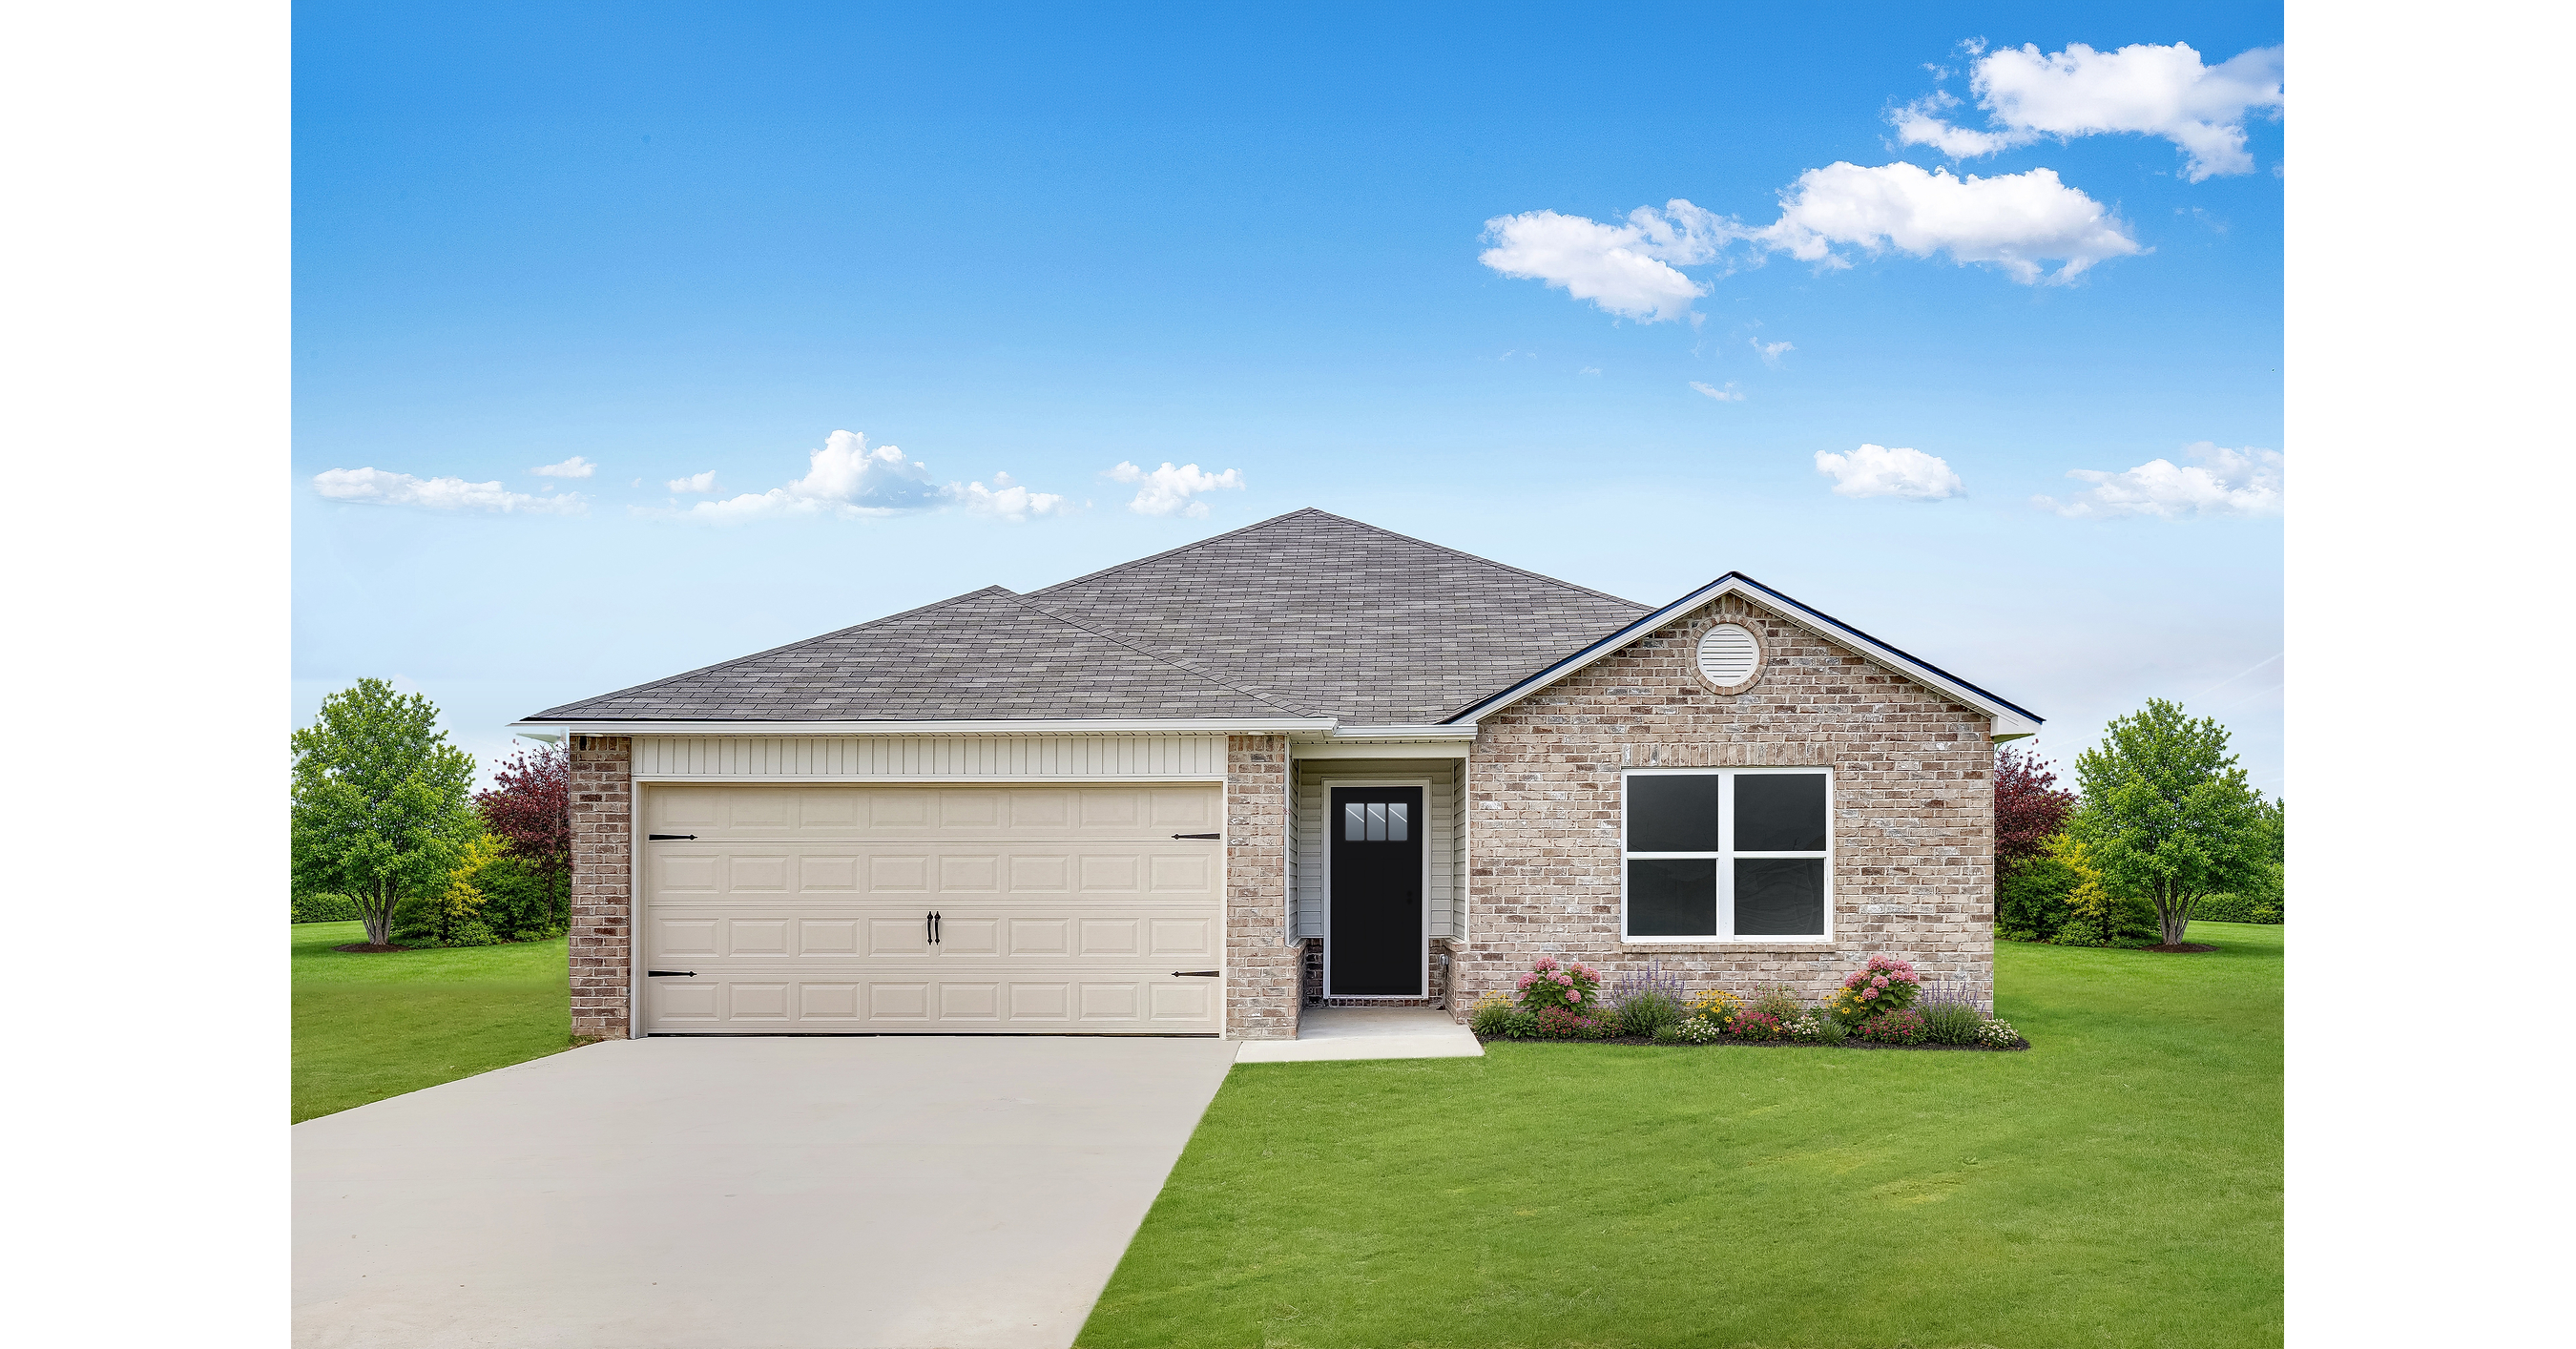
Lennar opened Cherokee Bend, a new single-family-home community in Moundville, Alabama, with seven floorplans priced from the $200,000s. Homes range from 1,143 to 2,174 square feet and include three to four bedrooms, with included features such as quartz countertops, appliances, washer/dryer and smart thermostats. The localized community launch modestly expands Lennar's Alabama footprint but is unlikely to materially affect company-wide results.
Analysis
This is immaterial to Lennar’s consolidated earnings and should not alter estimates; the investment relevance is instead as a low-cost-market data point. Entry-level product near Tuscaloosa can support absorption even when national affordability remains constrained, but included finishes, appliances and financing-related incentives may limit gross-margin realization versus headline base pricing. Investors should treat the release as marketing rather than evidence of incremental demand or pricing power until local starts, cancellation rates and incentive levels are disclosed.
The more useful read-through is competitive: LEN’s scale can make turnkey specifications and captive mortgage execution harder for smaller Alabama-focused builders to match, potentially pressuring private-builder pricing before it meaningfully moves LEN’s share. Public comparables with greater Southeastern entry-level exposure—DHI, LGIH and MTH—face the same affordability-sensitive buyer pool, while regional resale inventory is the nearer substitute. Over the next 1-3 months, mortgage-rate direction and University of Alabama/Tuscaloosa employment trends matter far more than this community launch; a renewed rate decline would amplify demand, while rising incentives would reveal that nominal affordability is insufficient.
Contrarian view: the market often treats lower-priced community openings as volume-positive, but they can dilute margins if lot costs, buyer concessions and included-content costs rise faster than closing prices. The structural upside over 6-18 months is only credible if Lennar converts localized scale into faster turns and lower SG&A per delivery—not merely additional community count. Falsify a cautious margin view if upcoming LEN results show stable or improving gross margin excluding interest, declining incentives, and sustained community-level absorptions despite higher rates.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Ticker Sentiment
Key Decisions for Investors
- No standalone trade on this release; keep LEN exposure tied to quarterly evidence on orders, cancellation rates, incentives and gross margin rather than community-opening announcements.
- For a 1-3 month housing-rate expression, prefer a diversified long ITB or XHB over adding LEN specifically; use a move higher in 10-year Treasury yields and a broad deterioration in builder order commentary as the stop condition.
- Monitor a potential pair: long LEN / short a basket of smaller, entry-level Southeastern builders such as LGIH and MTH only if LEN demonstrates faster absorption with stable incentives. The thesis is scale and captive-finance advantage; exit if LEN’s incentive rate rises faster than peers or its margin guidance is cut.
- At LEN earnings, treat sequential deterioration in gross margin excluding interest or materially higher sales incentives as a signal to reduce exposure, even if unit-order growth remains positive; that combination would indicate volume is being purchased at the expense of earnings quality.
More News
- Lennar earnings missed by $0.10, revenue fell short of estimates
- Lennar earnings on deck: Margin pressure tests homebuilder
- Fed delivers its first hike in 3 years. Plus, what's moving Starbucks and GE Vernova
- Japan’s corporate leaders sound alarm over weak yen — even dollar-earners are voicing concerns
- Fed hikes again - an AI-Picked insurer is still cashing in
- Berkshire May Boost Japan Trading House Holdings, Itochu Says
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Sector Analysis, Improvements on Research Data, and Performance Enhancements
- Choosing an AI Copilot for Equity Research