
VeloSource CEO Jeff Schaal Recognized on SIA's Healthcare Staffing 100 List
Source: PRWeb
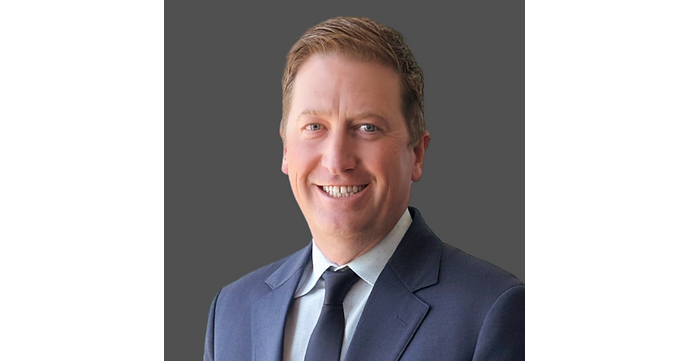
VeloSource CEO Jeff Schaal was named to SIA’s 2026 Healthcare Staffing 100, amid the company’s expansion from a locum tenens agency into a full-scale workforce solutions provider. VeloSource acquired Syncx and Quest earlier in 2026 and says its expanded offerings will include VMS, MSP, physician float pool, and applicant tracking systems; the article reports no financial figures or market reaction.
Analysis
The strategic bet is not the leadership award; it is whether VeloSource can convert acquisitions and a broader product suite into recurring, multi-service hospital relationships. Bundling locum coverage with VMS/MSP and float-pool offerings could improve retention and expand wallet share, while giving the company more visibility into demand and clinician utilization. But the model has a trust hurdle: a staffing supplier that also sells ostensibly neutral workforce-management services may face questions about supplier impartiality and data use. Large health systems may prefer established platforms or keep procurement technology separate from staffing vendors.
The acquisition-led expansion also raises execution risk. Combining brands, systems, and operating teams can distract from clinician fulfillment and service quality; rapid volume growth may consume working capital if payroll outpaces customer collections. These are conditional risks, not evidence that VeloSource has encountered them. SIA rankings and awards provide limited validation of scale or reputation, not proof of profitability, platform adoption, or acquisition returns.
Over the next 1–3 months, the useful signals are customer wins that include multiple services, retention, clinician fill rates, and evidence that Syncx technology is being adopted beyond acquired accounts. Over 6–18 months, successful integration could strengthen VeloSource against staffing-only competitors and make it a more valuable platform for its private-equity owner. Conversely, technology or service integration problems could weaken the core staffing franchise. The article alone does not create a public-equity catalyst; any read-through to healthcare staffing companies is too indirect to justify a trade.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No direct trade on this announcement: VeloSource is privately held, and an award plus company-reported expansion does not establish incremental earnings or a public-market catalyst.
- Track VeloSource as a competitive watch item against AMN Healthcare and Cross Country Healthcare: look for verifiable multi-service hospital contract wins, customer retention, fill rates, and whether buyers accept a staffing provider as a neutral VMS/MSP operator.
- For any future investment read-through, request evidence on acquired-business integration, platform adoption, and cash conversion. A deterioration in fill rates or service quality, or growth that strains working capital, would falsify the platform-synergy thesis.
- Treat a successful launch as a medium-term competitive signal, not an immediate sector-wide signal; absent customer or financial data, avoid positioning public staffing names on this release alone.
More News
- Magnificent 7 loses $1 trillion. The most eye-popping stats from Thursday's tech stock plunge
- Tech stocks are suffering their biggest selloff since Covid, as investors see premature end to AI datacenter boom
- Wall Street’s best post-midterm rally in 44 years lasted just one day—then $3 trillion vanished as chip stocks plunged over AI fears
- Elon Musk's Tesla and SpaceX lose over $420 billion in combined market cap after midterms
- AI stocks plunge after election, driving down US markets
- Shield AI To Hit $28.8 Billion Value With $5.3 Billion Radar Acquisition