
US Debt Reckoning and Trump’s Post-Midterm Playbook Come Into Focus
Source: Bloomberg
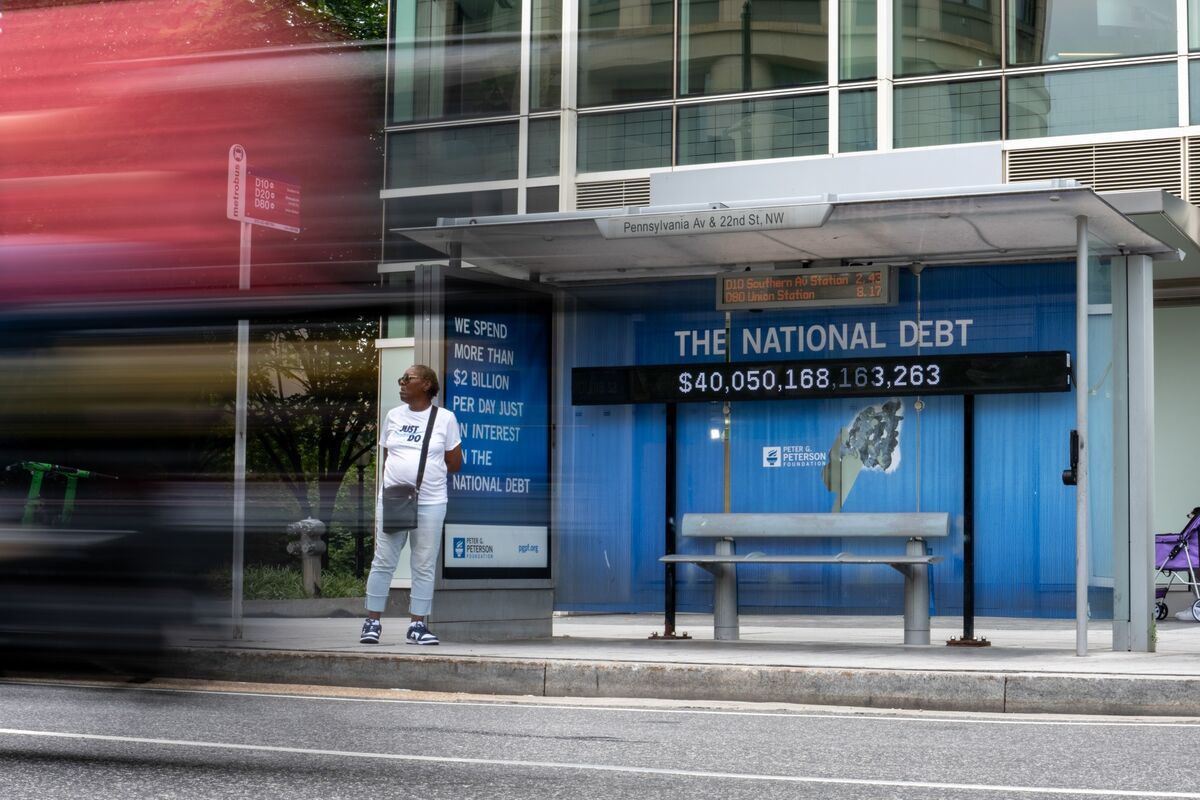
The article frames a “debt reckoning” narrative, arguing Washington will only act on deficits when the bond market forces the issue. It links the post-midterm playbook to how White House and Congress may respond, with investor focus on Treasury market signals for broader implications to yields and credit risk. Overall, the tone is cautious, implying rising sensitivity of rates to fiscal sustainability concerns.
Analysis
The market mechanism here is not a headline trade in Washington; it is a higher term-premium regime. If investors start treating fiscal path credibility as a binding constraint, the first-order winner is nominal yield volatility, not any one political asset: duration gets repriced, mortgage rates stay sticky, and equity multiples on long-duration cash flows compress. That is most punitive for unprofitable software, REITs, homebuilders, and any levered balance sheet that depends on cheap refinancing.
The second-order effect is that the Treasury market becomes the policy referee. Weak auction demand or persistent tailing would force Congress to confront financing costs faster than political calendars usually allow, and that feedback loop can tighten financial conditions even without a Fed hike. In that setup, banks and insurers can see an initial benefit from steeper curves and higher reinvestment yields, but the trade only works if credit spreads do not widen enough to overwhelm NII tailwinds.
Over 1-3 months, the cleaner expression is to own higher-rate beneficiaries versus duration. Over 6-18 months, the bigger risk is a policy pivot: fiscal tightening, a growth scare that pulls yields down, or a central-bank response that re-anchors the long end. The contrarian miss is that this is less about partisan politics and more about market plumbing; once the bond market loses patience, the adjustment can be abrupt and self-reinforcing.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.20
Key Decisions for Investors
- Short TLT on any rally; use a 1-3 month horizon and target downside if 10Y yields continue to trend higher. Falsify if 10Y yield reclaims sub-4.0% and Treasury auctions stop tailing for several cycles.
- Pair trade: long XLF / short XLK for 6-12 weeks. Higher term premium should support bank NII while compressing multiples on duration-heavy tech; exit if credit spreads widen sharply or yields fall on growth scare.
- Short IWM versus SPY over the next 1-3 months. Small caps carry more refinancing exposure and less balance-sheet flexibility, so they are more vulnerable if funding costs stay elevated.
- Avoid treating DJT as a clean fiscal proxy; no direct fundamental edge is visible from this setup. Use it only as a sentiment barometer for political-volatility spikes, not as a core trade.
- Watch the next Treasury refunding and 10Y/30Y auction results as the catalyst. If demand is strong enough to cap yields, cover duration shorts quickly; if auctions weaken, press the rate-sensitive shorts.
More News
- Oval Office spat to public rebukes: A timeline of Trump-Zelenskyy ties
- Trump selects Katie Zacharia as White House press secretary
- Trump Media advisor Katie Zacharia named White House press secretary
- Take Five: Bangkok blues
- RBI Tightens Rupee Defense as Pricey Crude, Foreign Outflows Bite: USD/INR
- Why is SK Hynix stock sliding today?
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Selecting an AI Research Platform for Institutional Investors
- Weekly Update: New Reporting Features and More Sources for Document Search