
Corewell Health Announces $1.7 Billion Investment to Build Stronger Healthcare for Michigan
Source: PR Newswire
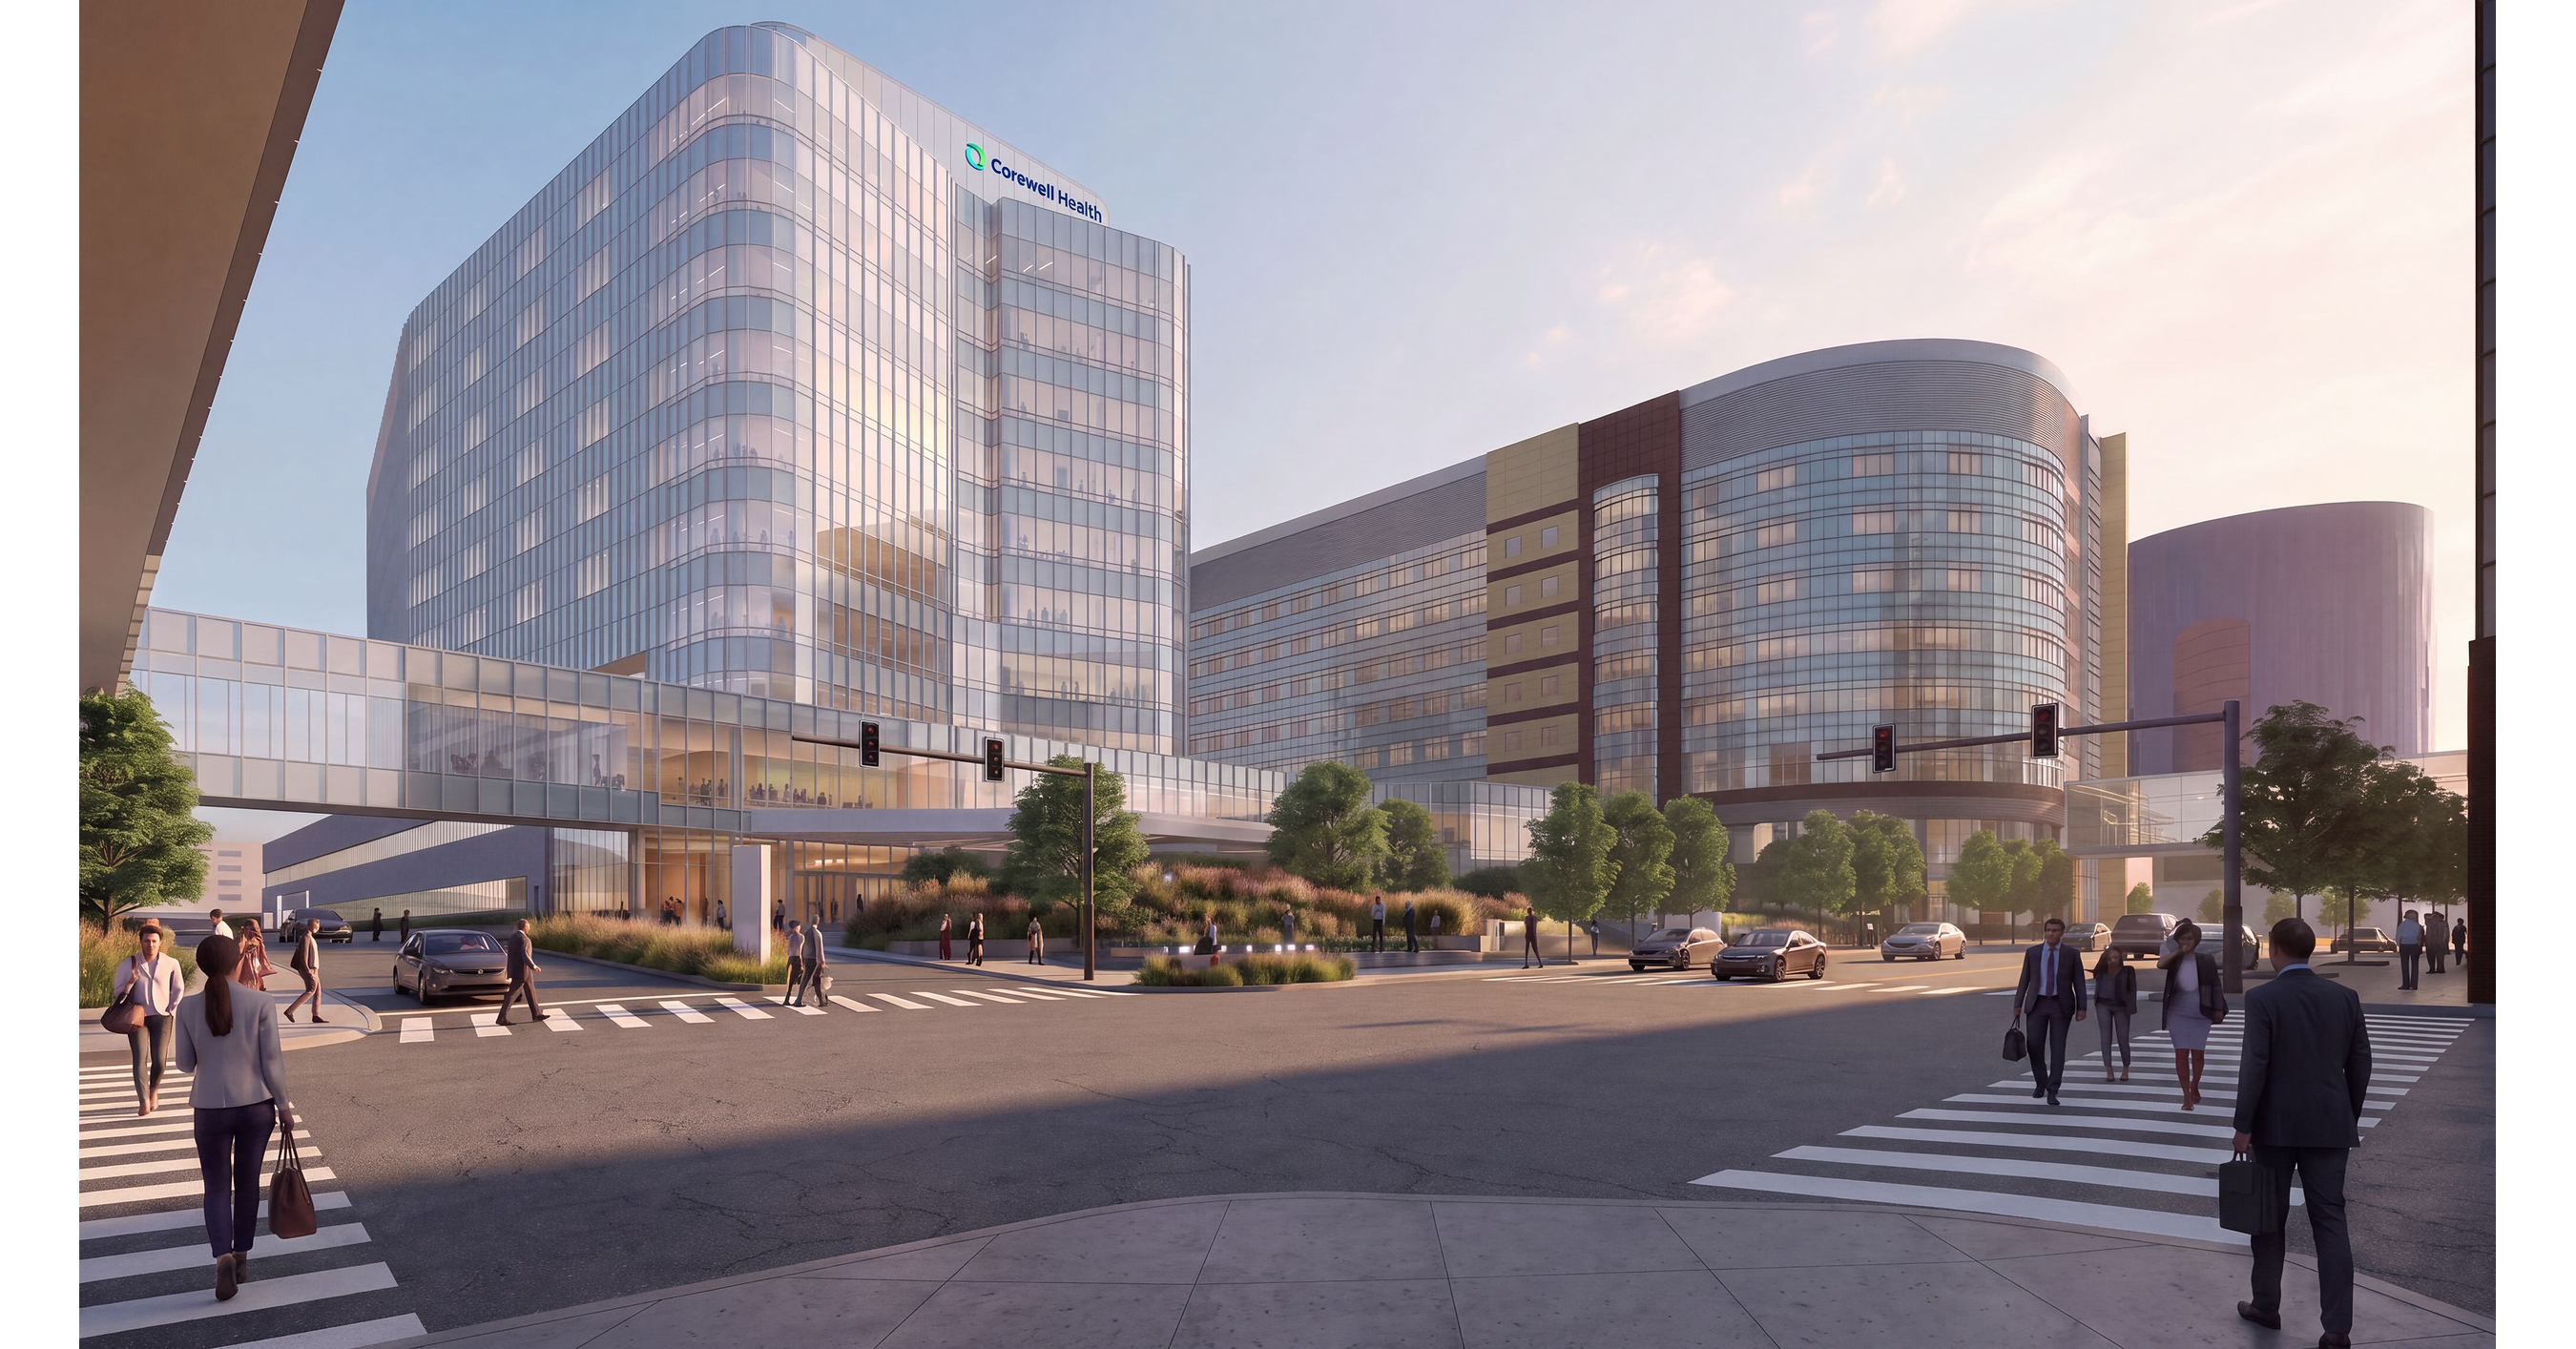
Corewell Health announced a $1.7 billion Michigan expansion, including a $1.34 billion replacement/expansion at Butterworth Hospital (780,000 sq ft) with 180 private rooms and 17 operating rooms, plus an approximately $440 million Troy hospital tower (423,000 sq ft) with 180 private rooms and a redesigned emergency arrival experience. Both projects are expected to start construction in summer 2027 and be completed by 2030, aimed at addressing healthcare demand where facilities are already running at 90%+ capacity.
Analysis
This is not a near-term earnings catalyst for public equities; the spend starts years out, so the headline is more a signal about persistent bed tightness than a tradable cash-flow event. The mechanism matters: when a system is forced to add private rooms, ED throughput and OR capacity, the value shifts from pure volume to higher-acuity capture and faster turnaround, which tends to favor scaled hospitals and equipment vendors over undercapitalized local competitors.
The cleaner second-order winners are the medical-device and hospital-equipment names that ride modernization cycles, especially SYK, GEHC, and STE, because those projects usually pull through beds, imaging, OR infrastructure, and workflow software before they pull through staffing. The likely losers are nearby outpatient and same-day surgery alternatives if the upgraded hospital keeps complex cases in-house; that is a subtle headwind for ASC-heavy business models, but only if referral leakage had been meaningful to begin with.
The main risk is execution: municipal approvals, financing costs, and labor inflation can turn a "capacity expansion" into a multi-year margin drag before any revenue benefit shows up. The contrarian read is that this may be defensive capex, not a demand inflection; if reimbursement softens or volumes normalize, the NPV of the project compresses quickly and the market should not pay up for the announcement alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- No direct trade in HIT/Corewell: treat this as a watch item, not a catalyst, until permitting and financing are visible; the 2027 start date makes the current impact de minimis.
- Buy SYK on 5-7% pullbacks over the next 1-3 months as a proxy for hospital modernization spend; target a 12-month 2:1 upside/downside setup if U.S. hospital capex commentary improves.
- Buy a small basket of GEHC and STE on weakness into any sector selloff; thesis is 6-18 months of equipment refresh demand from capacity-constrained systems, invalidated if hospital capex guides flat for two consecutive quarters.
- Relative-value: long HCA / short SGRY for 3-6 months if you want to express the "hospital systems reclaim complex volume" view; exit if ASC volumes continue to outgrow inpatient procedures or if HCA commentary turns to labor-driven margin pressure.
More News
- Attack on Saudi airport kills 12 people and wounds more than 300—the deadliest strike in any Gulf Arab country since the start of the Iran war
- Musk says Terrafab chip factory could outperform rivals despite challenges
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- Trump says he’s evaluating whether the U.S. should join Saudi Arabia’s fight against Iran-backed Houthi rebels in Yemen after fresh attacks on Riyadh
- World condemns deadly Houthi attack on Saudi Arabia’s Riyadh airport
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AlphaSense Pricing: What Public Contract Data Shows in 2026
- Eli Lilly Q4 2025 Earnings: Revenue Surges 43% as Mounjaro and Zepbound Dominate the GLP-1 Market