
Emerald Clinical Trials Appoints Michael Stibilj as Chief Executive Officer to Lead Next Phase of Global Growth
Source: PR Newswire
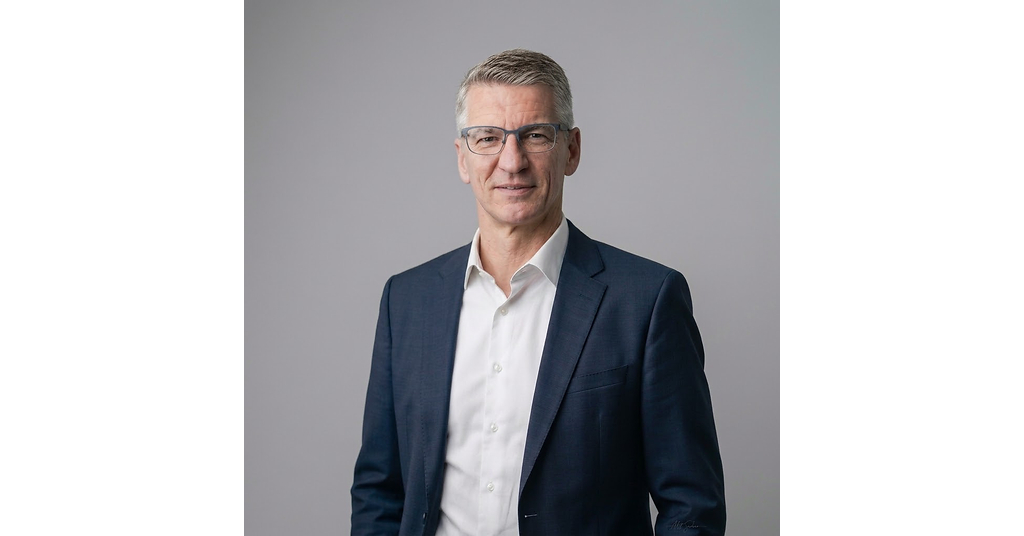
Emerald Clinical Trials appointed CRO veteran Michael Stibilj as CEO effective October 1, 2026, following a transformative year that included its acquisition of Hongyi Clinical Development Services. The combined clinical-development platform employs more than 1,000 professionals across 40+ countries and 70+ locations, serving sponsors from first-in-human trials through post-marketing. Management positions the leadership change and expanded Asia-Pacific footprint to capture accelerating global clinical-development demand.
Analysis
This is not a tradable catalyst for IQVIA (IQV): executive turnover at a private, subscale APAC-focused CRO does not alter IQV's revenue trajectory or valuation. The more relevant read-through is competitive: a better-integrated Emerald could bid more aggressively for emerging-biotech and China/APAC trial work, creating localized pricing pressure for global CROs and potentially for MEDP and ICLR in lower-complexity studies. That pressure would be gradual—visible first in book-to-bill and net-new-award growth over the next 2-4 quarters—not an immediate earnings risk.
The strategic uncertainty is integration rather than leadership pedigree. Cross-border CRO acquisitions can create delivery friction around data standards, site relationships, regulatory workflows, and staff retention; if Emerald uses its expanded footprint to discount for share, it may impair its own margins before meaningfully disrupting scaled incumbents. Conversely, sustained biotech funding, improved China trial-start timelines, and increasing use of APAC sites could make regional CRO capacity strategically scarce over 6-18 months, benefiting well-capitalized public platforms with established therapeutic-area infrastructure.
Contrarian view: the market should not infer a broad positive signal for listed CROs from management rhetoric around industry growth. CRO demand is driven primarily by sponsor R&D budgets, biotech financing, trial complexity, and cancellation rates; absent evidence of incremental awards or sponsor outsourcing gains, this is routine private-company governance news. Note that PPC in the structured ticker data is Pilgrim's Pride and has no apparent economic connection to the referenced PPC Group.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Key Decisions for Investors
- No standalone trade in IQV or PPC on this announcement; expected fundamental impact is immaterial and neither company has a direct disclosed transaction exposure.
- Place a 1-3 quarter watch on MEDP and ICLR APAC booking commentary, backlog conversion, and gross-margin guidance. A material acceleration in APAC pricing competition or slowed awards would support a relative short versus IQV; without such evidence, do not position.
- For existing CRO exposure, retain IQV as the higher-scale defensive proxy rather than chase smaller CRO beta. Reassess if IQV reports two consecutive quarters of sub-industry book-to-bill or identifies China/APAC price concessions as a source of margin pressure.
More News
- Can Trump Oust Powell From the Fed Board? What to Know
- Europe’s winter energy crunch may already be underway. Two U.S. stocks that may benefit
- Broadcom to lend Anthropic up to $42 billion to lease its chips, filing says
- Nike Warns Sales Slump Will Worsen This Fiscal Year
- Nuveen CEO on Schroders Deal, Plans for Combined Company
- $8.2B acquisition validates AI-picked chip stock: +20% since June