
IXOPAY Appoints Ajoy Krishnamoorthy as CEO to Accelerate Growth and Advance Payments for the Agentic Age
Source: Newswire
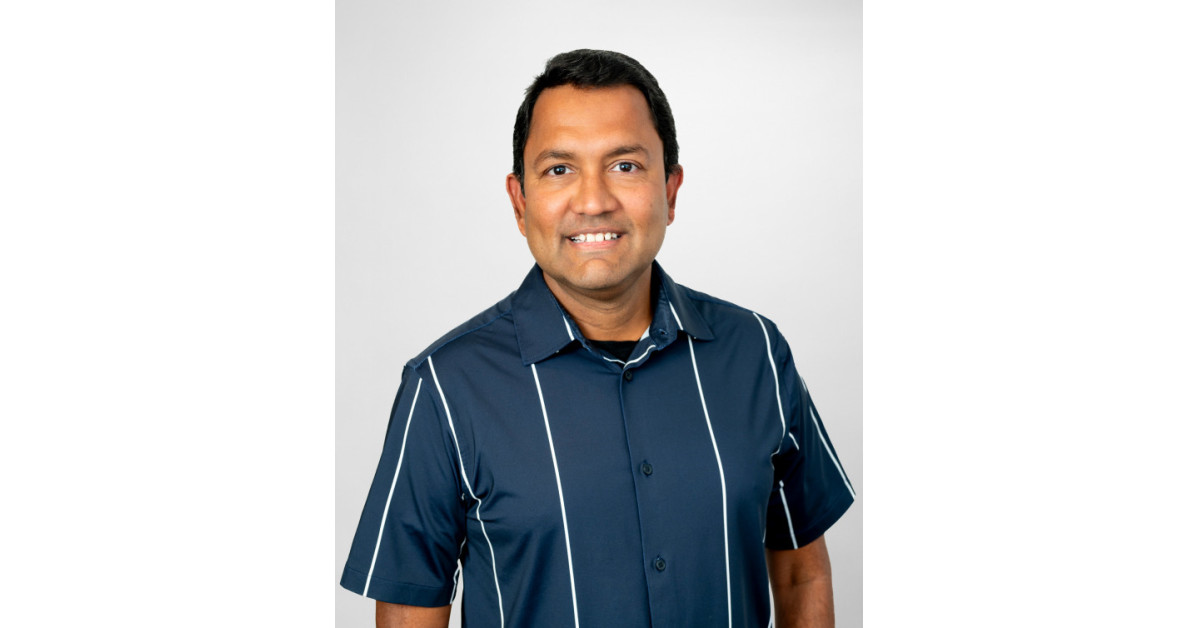
IXOPAY appointed Ajoy Krishnamoorthy as CEO to advance its AI-native, agentic payments infrastructure. The company cited 2025 performance of $171B in payment volume, 2.1B+ tokens, and support for 1.6M merchants via 500+ payment adapters, reinforcing current momentum as it pushes an “agentic age” product roadmap. This is primarily leadership/strategy news with limited direct financial impact, but it is mildly positive given the stated scale and product focus.
Analysis
This is more of a strategic signal than a near-term earnings catalyst. A payment-orchestration vendor leaning harder into AI-native infrastructure implies merchants want control points that sit above the processor, which is structurally negative for incumbents that monetize opacity, routing inertia, or bundled stacks. The first-order winner is the merchant; the second-order winner is the orchestration layer that can pressure pricing across acquiring, gateways, and fraud tools.
For public comps, the real read-through is to margin durability, not top-line growth. If merchants can swap routing, tokenization, and fraud logic more easily, then take rates and cross-sell economics for names like GPN can drift lower over 2-4 quarters even if volume stays fine. That pressure would show up first in net revenue retention, mix shift toward lower-fee products, and weaker pricing power rather than an immediate volume miss.
The contrarian risk is that "agentic commerce" remains mostly narrative for 6-18 months: more AI-driven transactions can also mean more fraud, more compliance friction, and slower deployment cycles, which delays any monetization uplift. MSFT is the cleaner structural beneficiary if AI agents become an enterprise control plane, because the value pools shift toward identity, cloud, and developer tooling rather than payments processing. I would treat this as a watch item, not a high-conviction signal, unless upcoming earnings show clear deterioration in payment take rates or a step-up in merchant churn.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- Maintain a neutral-to-underweight stance on GPN on any hype-driven strength; the setup is a gradual margin-compression story over 2-4 quarters, not an immediate revenue shock.
- Small relative-value pair: long MSFT / short GPN for 6-12 months if AI commerce adoption becomes a theme; MSFT has the better structural claim on identity, cloud, and agent infrastructure while GPN faces pricing pressure.
- Set an alert for GPN earnings on merchant solutions margin, net revenue retention, and take-rate trends; a stable or improving print would falsify the compression thesis.
- Do not force a sector-wide fintech long from this news alone; prefer to wait for verifiable evidence of higher agentic transaction volume and lower fraud losses before paying up for the theme.
More News
- US suspends Microsoft and Adobe from visa programme amid fraud claims
- Trump admin suspends green cards to Microsoft as Vance accuses the company of replacing laid-off workers with ‘foreign indentured servants’
- Trump Immigration Crackdown Targets Microsoft Workers, Harvard, MIT Students
- Why Trump Suspended Microsoft and Other Tech Firms From a Green Card Program
- This cybersecurity stock is already growing revenue at a 20% clip. And now here comes the AI boost
- U.S. suspends Microsoft, Adobe from green-card labor program in foreign worker crackdown