
Classys Nears 50,000 Devices Sold Globally as Full-Lineup Growth Accelerates
Source: PR Newswire
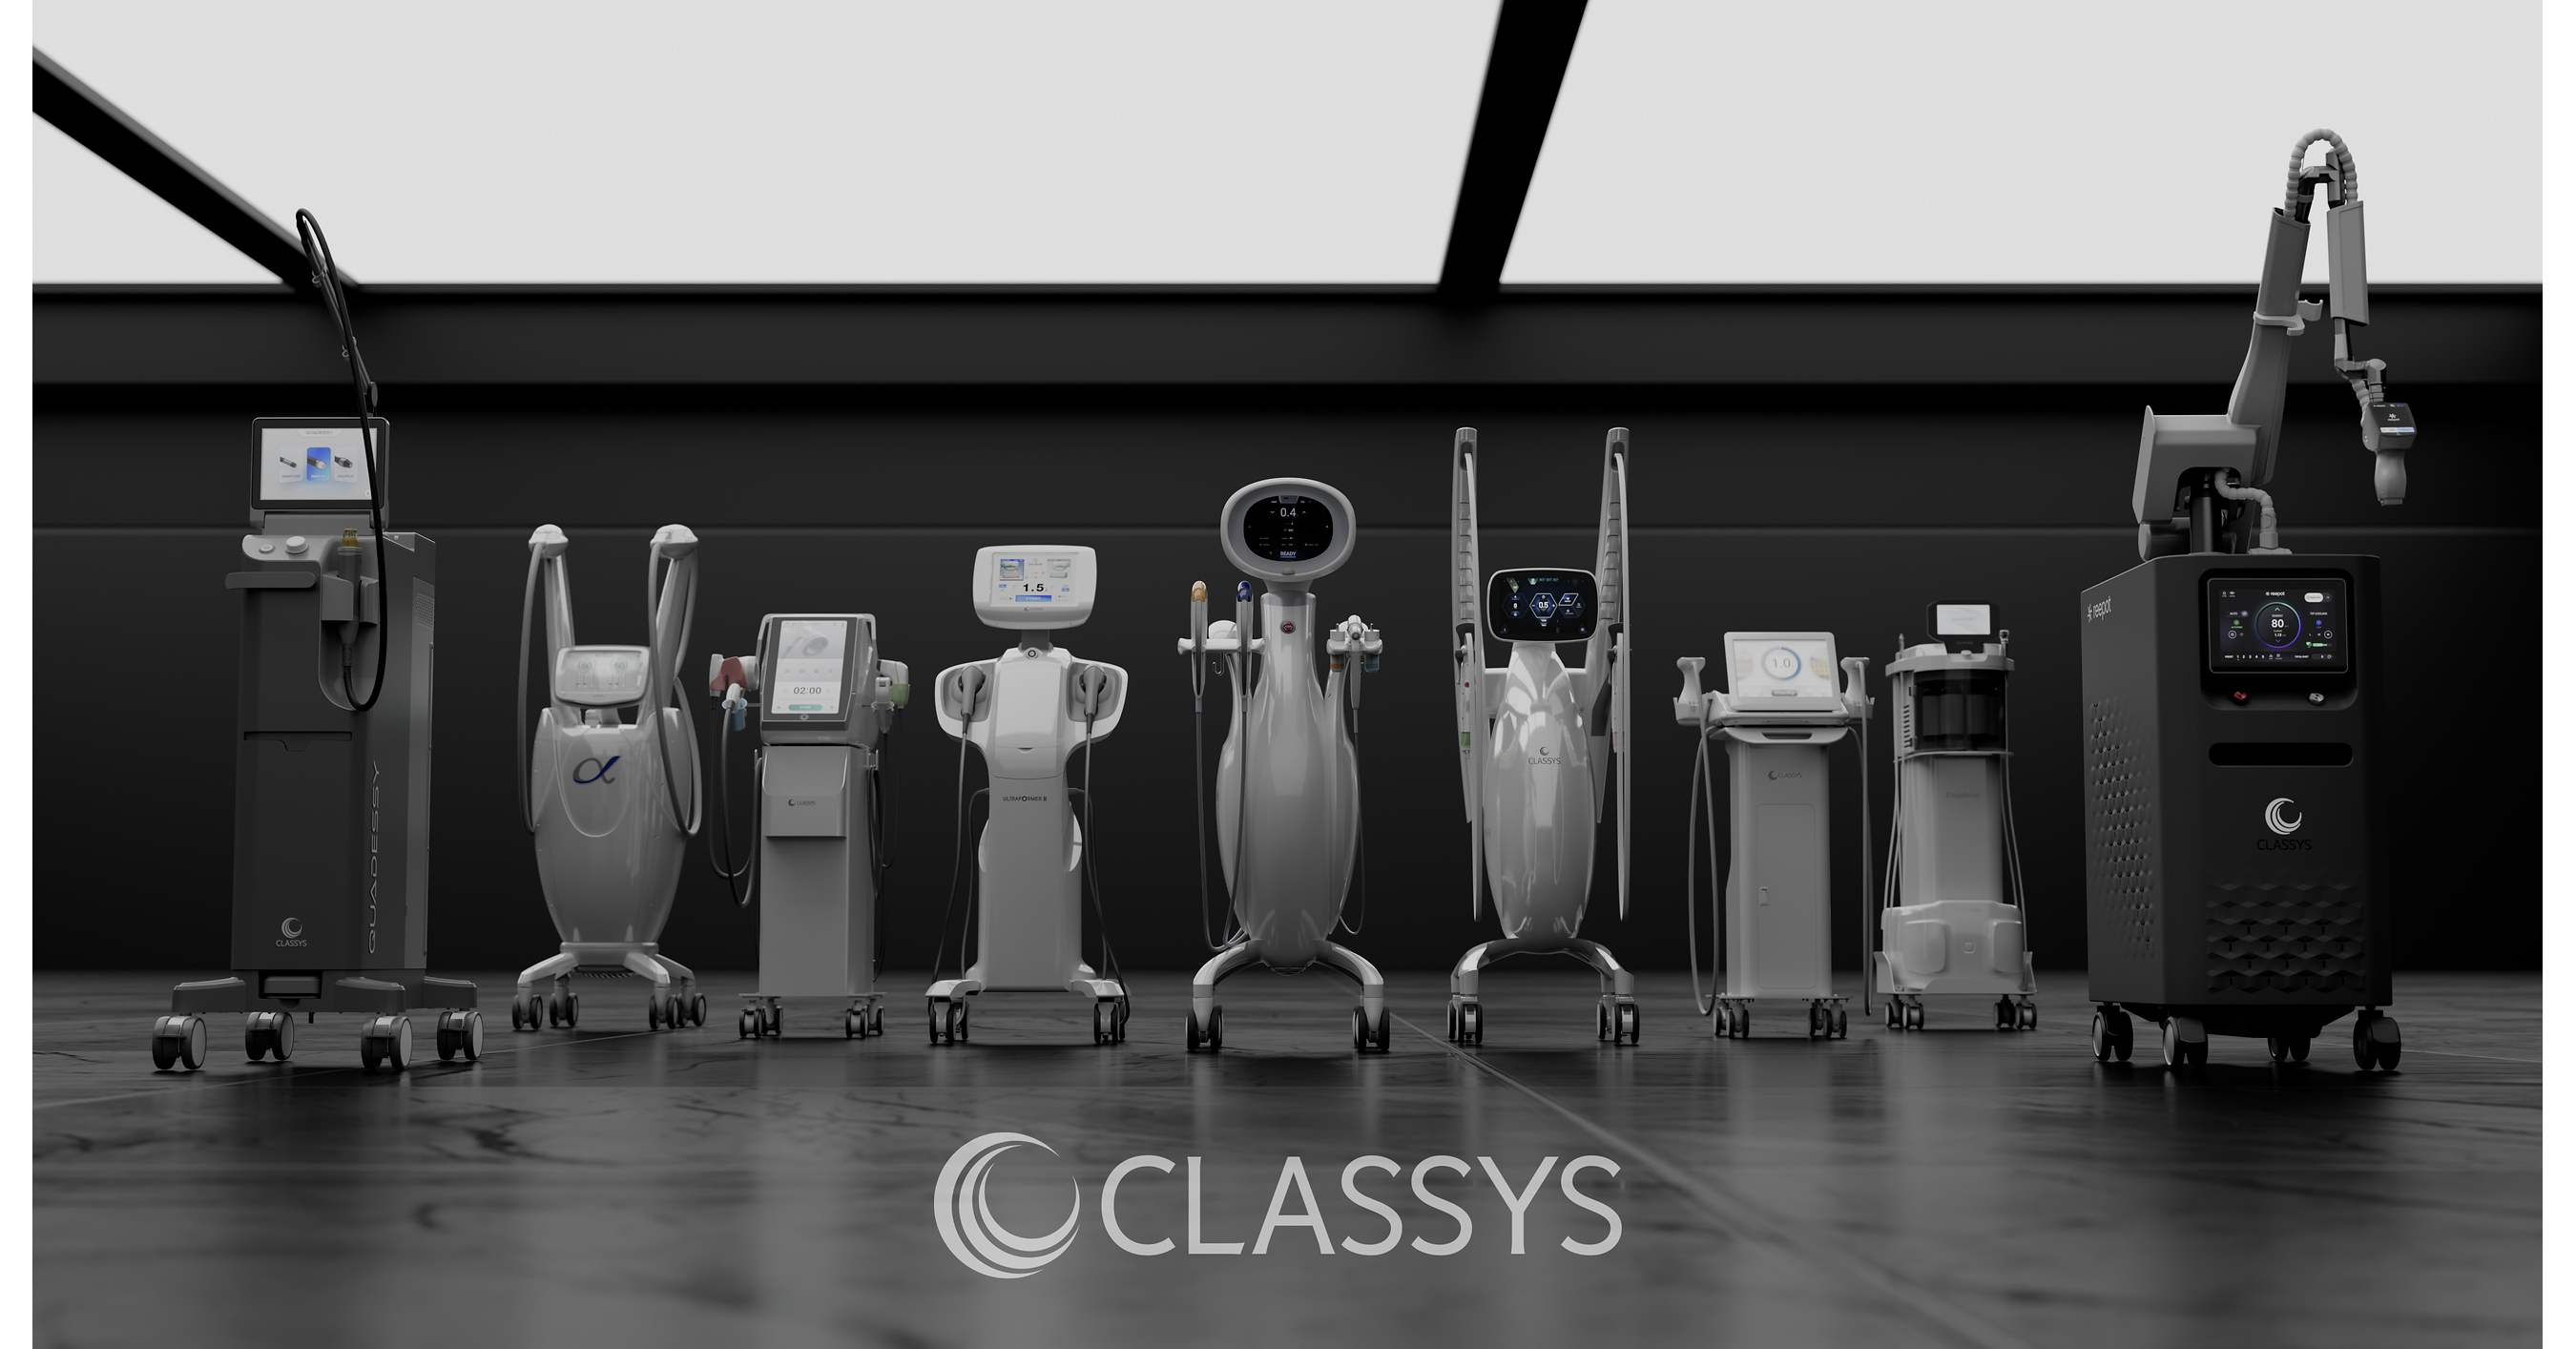
Classys expects global device sales to surpass 50,000 units this year, driven by portfolio expansion into MNRF and laser/dermabrasion beyond HIFU and MRF. 1H26 revenue rose 20% YoY to KRW 192.7B, while (excluding shipments to its Brazilian subsidiary) 1H26 export sales increased 29% YoY. Profitability remained strong with a standalone operating margin of 50.8%, and consumables revenue reached KRW 80.2B (+5.3% YoY), supported by cumulative installations exceeding 22,000 HIFU and 4,000 MRF units.
Analysis
The real signal is not unit growth; it is that the company is moving from a single-product selling motion to a platform model with higher switching costs. That matters because once a clinic is trained on one system, the next sale is increasingly about workflow consolidation and consumables capture rather than a one-off capital purchase, which should support pricing power and lower customer acquisition cost over 6-18 months.
Second-order, this is more threatening to smaller aesthetics vendors than to broad medtech. InMode and Cutera are most exposed if global distributors and KOL networks are becoming the moat, because those channels reward breadth, service coverage, and protocol depth; that tends to compress share for narrower product lines and weaker balance sheets. The consumables mix is also important: if utilization rises, the earnings quality improves faster than headline device revenue, which should help valuation durability if recurring revenue keeps compounding.
The main risk is that the growth narrative is being partially subsidized by geography and rollout timing, not just organic end-demand. Europe launches and Brazil channel transitions can inflate reported momentum for a few quarters; if procedure volumes do not follow, the installed-base thesis can disappoint. Falsifiers are simple: export growth decelerating below the high-teens for two consecutive quarters, consumables growth failing to reaccelerate, or margin compression as the company pushes too many product launches at once.
Near term, this is more of a quality-confirmation story than an immediate catalyst for a large re-rating. The market will probably wait for evidence that new platforms are monetizing the existing base rather than merely adding SKUs; if that shows up, the stock should deserve a premium multiple versus single-technology peers. If not, the market can quickly reclassify this as mature aesthetic hardware growth with lower terminal value than advertised.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.55
Key Decisions for Investors
- Relative-value long 287410.KQ (Jeisys Medical Systems) vs. short CUTR for 1-3 months: thesis is that scale, distribution depth, and cross-sell breadth are consolidating around the better platform operators; CUTR has the weaker downside if category share shifts further toward multi-product leaders.
- Watch INMD on any strength over the next 4-8 weeks as a potential short if peer data confirms Classys-style channel consolidation is real; risk/reward improves only if INMD commentary shows slowing international traction or weaker consumables attach.
- No aggressive long until the next two quarterly prints confirm consumables growth inflecting faster than device revenue; if consumables stays sub-10% growth while devices grow, fade the multiple expansion.
- Set a falsifier alert on export growth falling below ~20% YoY and/or operating margin dropping below 45%; either would argue the current narrative is being overstated and would justify reducing exposure to the aesthetics equipment basket.
More News
- Delta Air Lines cuts 2026 forecast on fuel surge, but CEO says demand is still strong
- Is AI the new China Shock?
- Why is T-Mobile stock tumbling today?
- This exchange stock is a buy on renewed options deal, Morgan Stanley says
- India calls JD Vance's comments about immigrants 'deeply offensive'
- The AI race may be decided by financing—not just better chips