
Pudu Robotics představuje PUDU TOMO S: Automatizovanou péči o trávník rozšiřuje o broušení žacích nožů
Source: PR Newswire
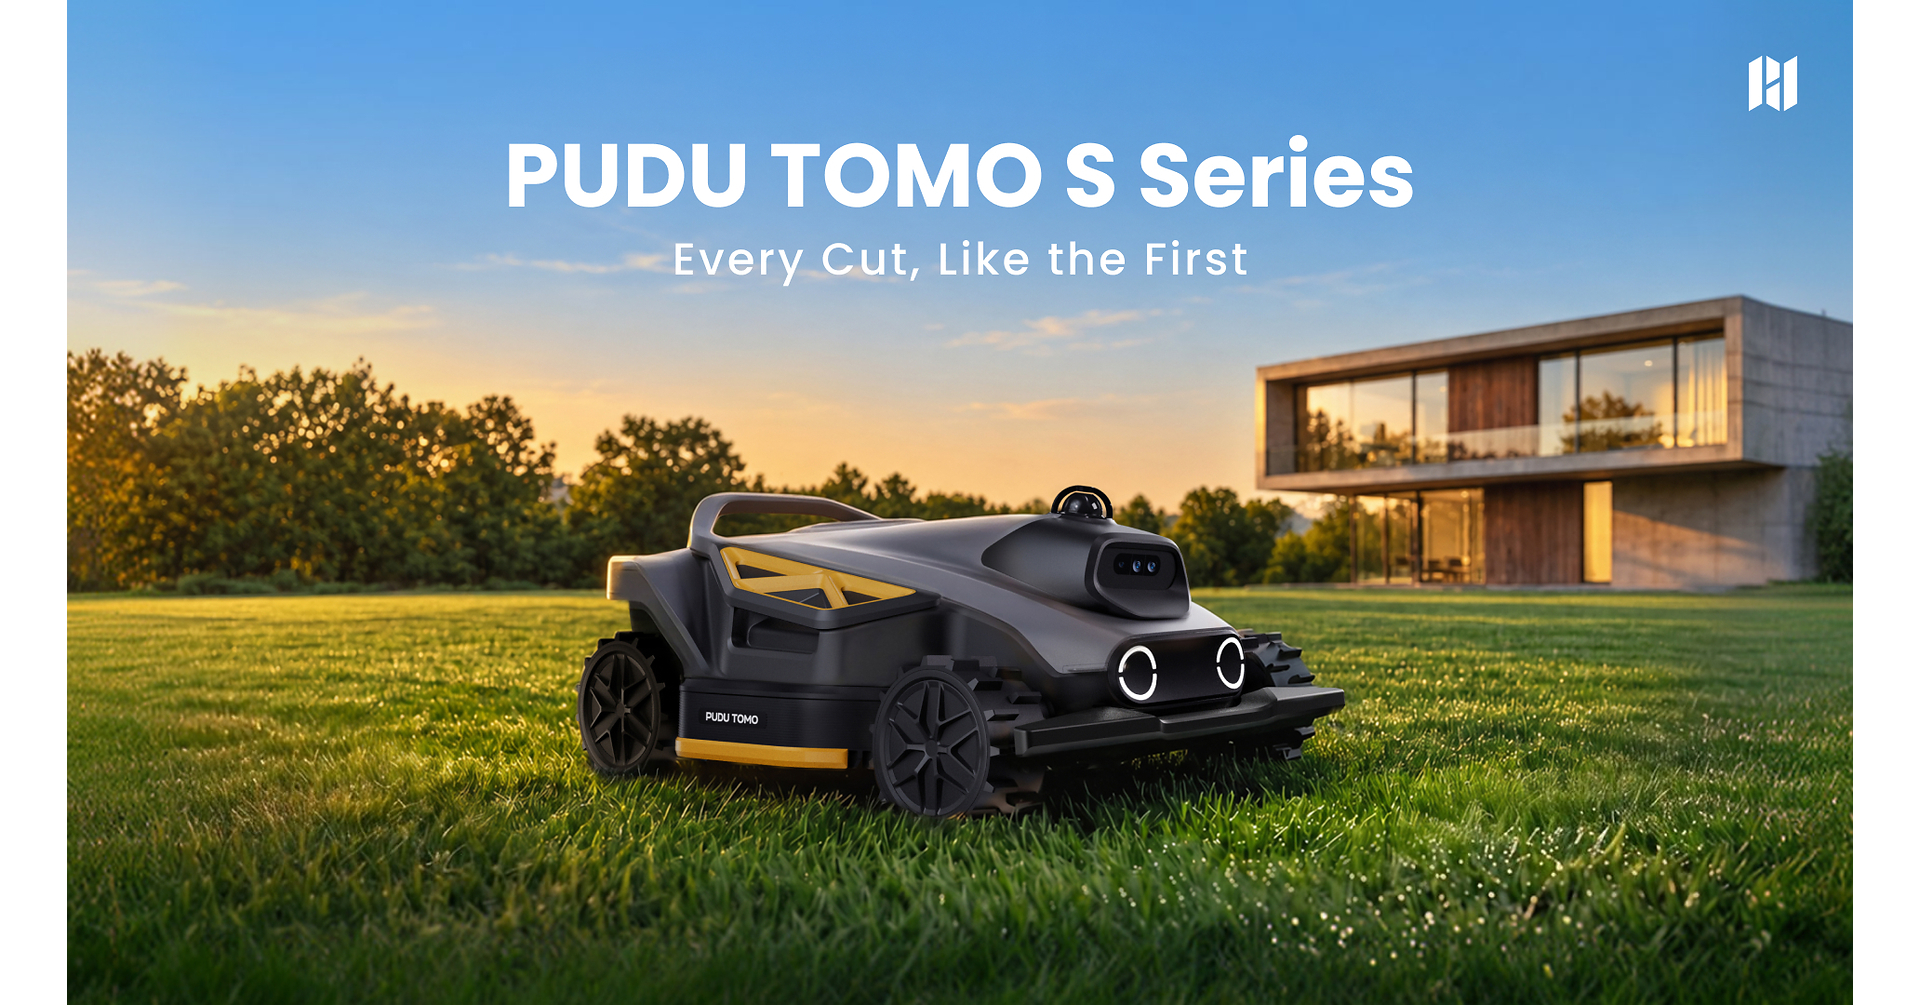
Pudu Robotics představila řadu robotických sekaček PUDU TOMO S pro trávníky o rozloze 1 500 až 5 000 m²; prodej se očekává začátkem jara 2027, ceny zatím nebyly oznámeny. Sekačky kombinují automatické ostření nožů, navigaci LiDAR, kamer s AI a RTK a zvládnou svahy až 45°; žací motory mají celkový výkon 636 W a dosahují až 6 000 otáček za minutu. Jde o expanzi společnosti z komerční robotiky do domácností, bez údajů o očekávaných tržbách či objednávkách.
Analysis
The investable signal is a competitive product test, not a read-through to the named public-company customers: Pudu’s references to Walmart and Marriott do not establish that either company is involved in this launch or will benefit from it. Pudu is privately held, and no pricing, channel, unit targets, or independently verified performance data are provided, so this does not yet support a public-equity earnings estimate.
If the self-sharpening and edge-cutting claims hold up in field use, the second-order effect is to raise the feature bar for residential mower makers and potentially shift competition toward software, navigation reliability, service, and replacement-blade economics—not merely cutting hardware. Husqvarna and Mammotion are relevant competitors to monitor; Toro (TTC) is a possible public-sector proxy, though the article gives no evidence of exposure or displacement. Any pressure on incumbents is conditional on Pudu achieving credible distribution and acceptable pricing.
Near term, the announcement is unlikely to change listed-company fundamentals. The 1–3 month catalyst is disclosure of price, regional availability, independent reviews, and dealer or direct-sales reach ahead of the expected spring 2027 launch. Over 6–18 months, warranty/service costs, reliability, and repeatable customer adoption matter more than headline specifications. The contrarian point: an impressive feature set can increase product complexity and support burden; absent pricing and evidence of durable demand, treating this as a category winner would be premature. The thesis weakens if independent tests show no maintenance or edge-cutting advantage, or if launch timing/distribution slips.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No trade in MAR or WMT: their inclusion as examples of Pudu’s commercial-robotics customers does not connect them economically to the residential mower launch.
- Keep TTC and residential-mower competitors on watch rather than shorting: seek evidence of competitor pricing changes, lost orders, or guidance pressure before positioning for share loss.
- Treat spring 2027 as the first meaningful verification window. Reassess only after pricing, regional distribution, independent performance tests, and early reliability/warranty data are available.
- Falsification/watch item: a delayed launch, weak channel reach, or field evidence that sharpening, navigation, or service needs erase the claimed maintenance advantage would undercut the competitive thesis.
More News
- Santoli: AI bull market almost surely needs tech stocks to recover to keep advancing
- Binance co-CEO Richard Teng says hackers used fake job interviews, AI tool to steal $6.3 billion in crypto 108511116
- AMD stock jumps 7% on earnings as data center revenue nearly doubles
- Marvell-Lumentum Deal Puts Optical Networking at the Center of the AI Boom
- Marvell Technology could plunge on latest multibillion-dollar acquisition
- Disney Plans Thousands of Layoffs Companywide