
Omnicom Media Again Named Best Performing Global Media Group, Earns #1 Ranking Across All Four Regions
Source: PR Newswire
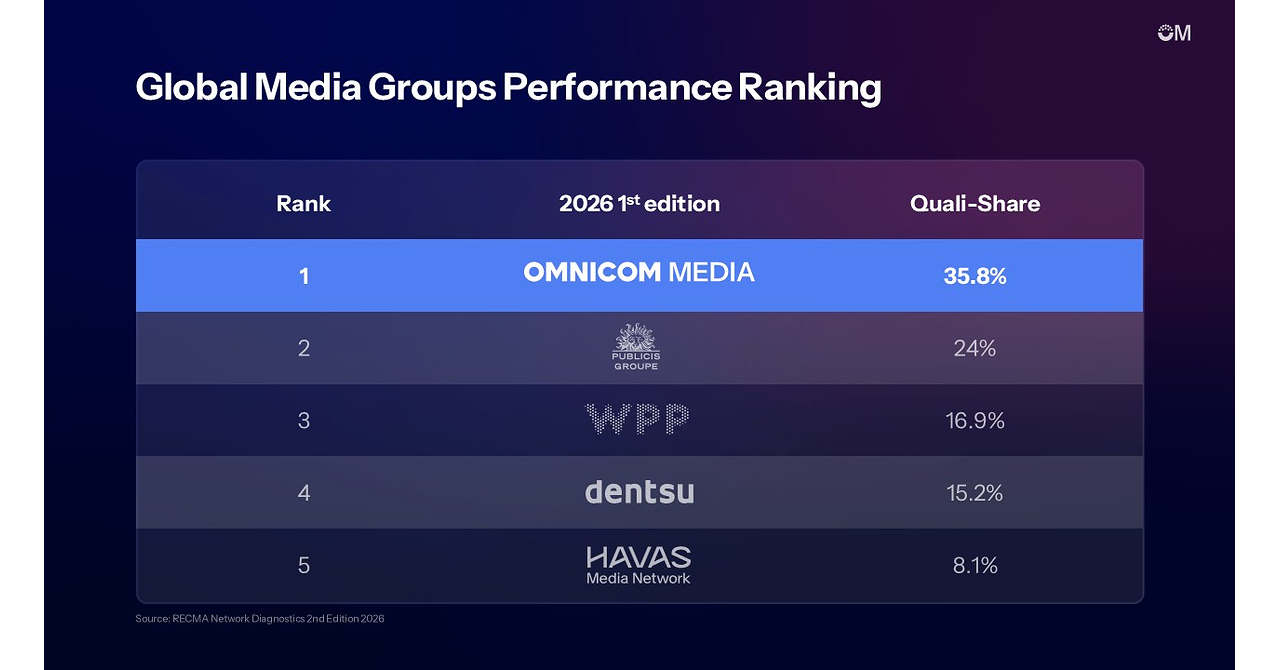
RECMA ranked Omnicom Media No. 1 globally and across North America, EMEA, APAC and LATAM for the second consecutive report; its agencies were dominant in 19 markets. OMD retained the global agency lead for a 12th consecutive report, while Omnicom Media reported approximately 30% industry share of billings, just under 35% of quali-share, and about US$10 billion in 2026 year-to-date billings won or retained through competitive pitches. The report also cited benefits from integrating Omnicom and IPG media groups; this is a company-specific performance ranking and win announcement, not reported financial earnings.
Analysis
The useful signal is not the ranking itself, but whether the merged capability can convert pitch wins into durable, profitable client revenue. The reported $10B of billings won or retained is not $10B of incremental Omnicom revenue: conversion depends on fee terms, launch timing, incumbent-account overlap and retention. RECMA’s qualitative measures may support retention and future pitches, but do not establish margin uplift or cash-flow accretion. Treat this as a modest positive indicator, not earnings evidence.
Near term, the announcement may reinforce confidence in integration execution. Over 1–3 months, verify client transitions and guidance commentary; over 6–18 months, the thesis is that combined data, identity and commerce capabilities improve retention and win rates. The countervailing mechanism is that greater scale can increase client concentration and conflicts, while integration or talent disruption could erode the very service quality the rankings measure. Stronger agency buying leverage may also benefit clients through lower fees rather than flow through to Omnicom margins.
The consensus risk is over-crediting pitch billings and agency rankings as immediate earnings growth. Conversely, if clients increasingly value integrated measurement and commerce execution, the rankings could be a leading indicator that is underappreciated. The release is company-sponsored; independently verify account start dates, retention, organic growth and margin commentary before sizing a position.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.65
Ticker Sentiment
Key Decisions for Investors
- Bias modestly positive on OMC, but do not chase solely on the release. Consider adding on broad-market or event-driven weakness only if subsequent results confirm organic growth and integration progress; no valuation or price data here supports a numeric entry or target.
- Use a 1–3 month watchlist catalyst: look for management disclosure on conversion of competitive wins into revenue, client retention and organic growth. The key missing data are fee economics, account start dates and how much of the cited billings is genuinely incremental versus retained.
- For a relative-value expression, consider OMC long against a diversified media-services peer basket only after checking current valuation, earnings revisions and relative price action; the ranking alone is not a sufficient short case against any competitor.
- Falsify the positive thesis if OMC reports weakening organic growth, margin pressure, notable account losses or integration-related disruption. Reassess if the apparent win momentum fails to translate into results over the next several reporting periods.
More News
- Binance co-CEO Richard Teng says hackers used fake job interviews, AI tool to steal $6.3 billion in crypto 108511116
- AMD stock jumps 7% on earnings as data center revenue nearly doubles
- Marvell-Lumentum Deal Puts Optical Networking at the Center of the AI Boom
- Marvell Technology could plunge on latest multibillion-dollar acquisition
- Disney Plans Thousands of Layoffs Companywide
- AMD rides data center riches to ‘largest and most profitable’ quarter in history