
Amazon's Robot Push Raises a Bigger Question About Its Next Margin Lever
Source: marketbeat.com
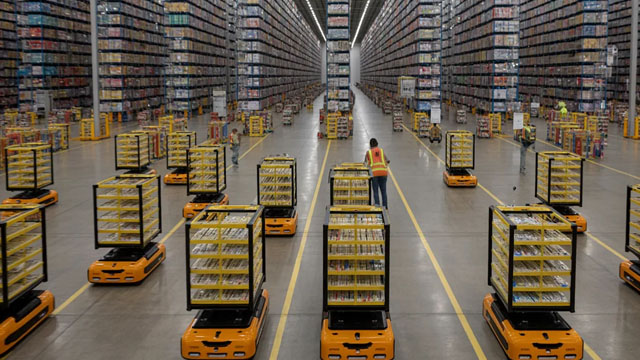
The article notes Amazon is “quietly working to automate” a previously manual part of its operations, consistent with its strategy of moving faster and cutting costs. No specific financial figures, timelines, or guidance changes are provided. As a result, the read-through for near-term performance appears limited and largely informational.
Analysis
This is an incremental margin story, not an immediate revenue story. If Amazon is automating another labor-heavy step in fulfillment, the near-term effect is higher capex and depreciation, but the real payoff is lower variable cost per unit and better throughput, which should show up first in operating margin and free cash flow rather than reported top-line growth.
The second-order effect is competitive, not just internal. A lower cost-to-serve lets AMZN keep subsidizing faster shipping and tighter price points, which widens the gap versus omnichannel retailers like TGT that cannot match network density or automation intensity. That pressure is most visible over 6-18 months through share gain in discretionary e-commerce and higher seller velocity, not necessarily in the next print.
The contrarian issue is that markets often overestimate how much of automation savings accrue to shareholders. Amazon can recycle efficiency into lower prices, more free shipping, or faster delivery, which protects share but delays margin capture. The thesis is falsified if the next 2 quarters show capex intensity rising without a visible inflection in fulfillment cost, operating margin, or FCF conversion.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.05
Ticker Sentiment
Key Decisions for Investors
- No immediate directional trade; treat this as a watch item until Amazon quantifies fulfillment productivity in the next 1-2 quarters. Falsifier: capex rises but operating margin and FCF conversion do not improve.
- On a 3-5% pullback in AMZN, add selectively for a 6-12 month margin-expansion setup. Risk/reward improves if the market discounts capex before savings show up; trim if the stock rerates ahead of margin evidence.
- Pair trade: long AMZN / short TGT over 6-18 months only if Amazon’s unit economics visibly improve. The relative thesis is that lower automation costs let AMZN defend price and speed while TGT remains more labor- and store-network constrained.
- If AMZN reports stronger margin but no FCF conversion, prefer equity over options; the market may be rewarding accounting leverage while cash payback is still pending.
More News
- Alphabet’s chief investment officer responds to Jefferies warning that the most likely outcome of the AI boom is massive U.S. capital destruction
- SpaceX’s ambitious, expensive gamble to replace AT&T, T-Mobile, and Verizon
- Neocloud Stock Collapse: Buying Opportunity or Run for the Hills?
- Amazon wants you to Bee-lieve wearable AI can recall it all for you
- EU cloud sovereignty law could cost Europe €115bn, US tech lobby study says
- Should you Buy Amazon Stock Before October 29? History Has a Clear Answer.