
United Imaging secures CE mark for world's first dual wide-coverage CT family
Source: PR Newswire
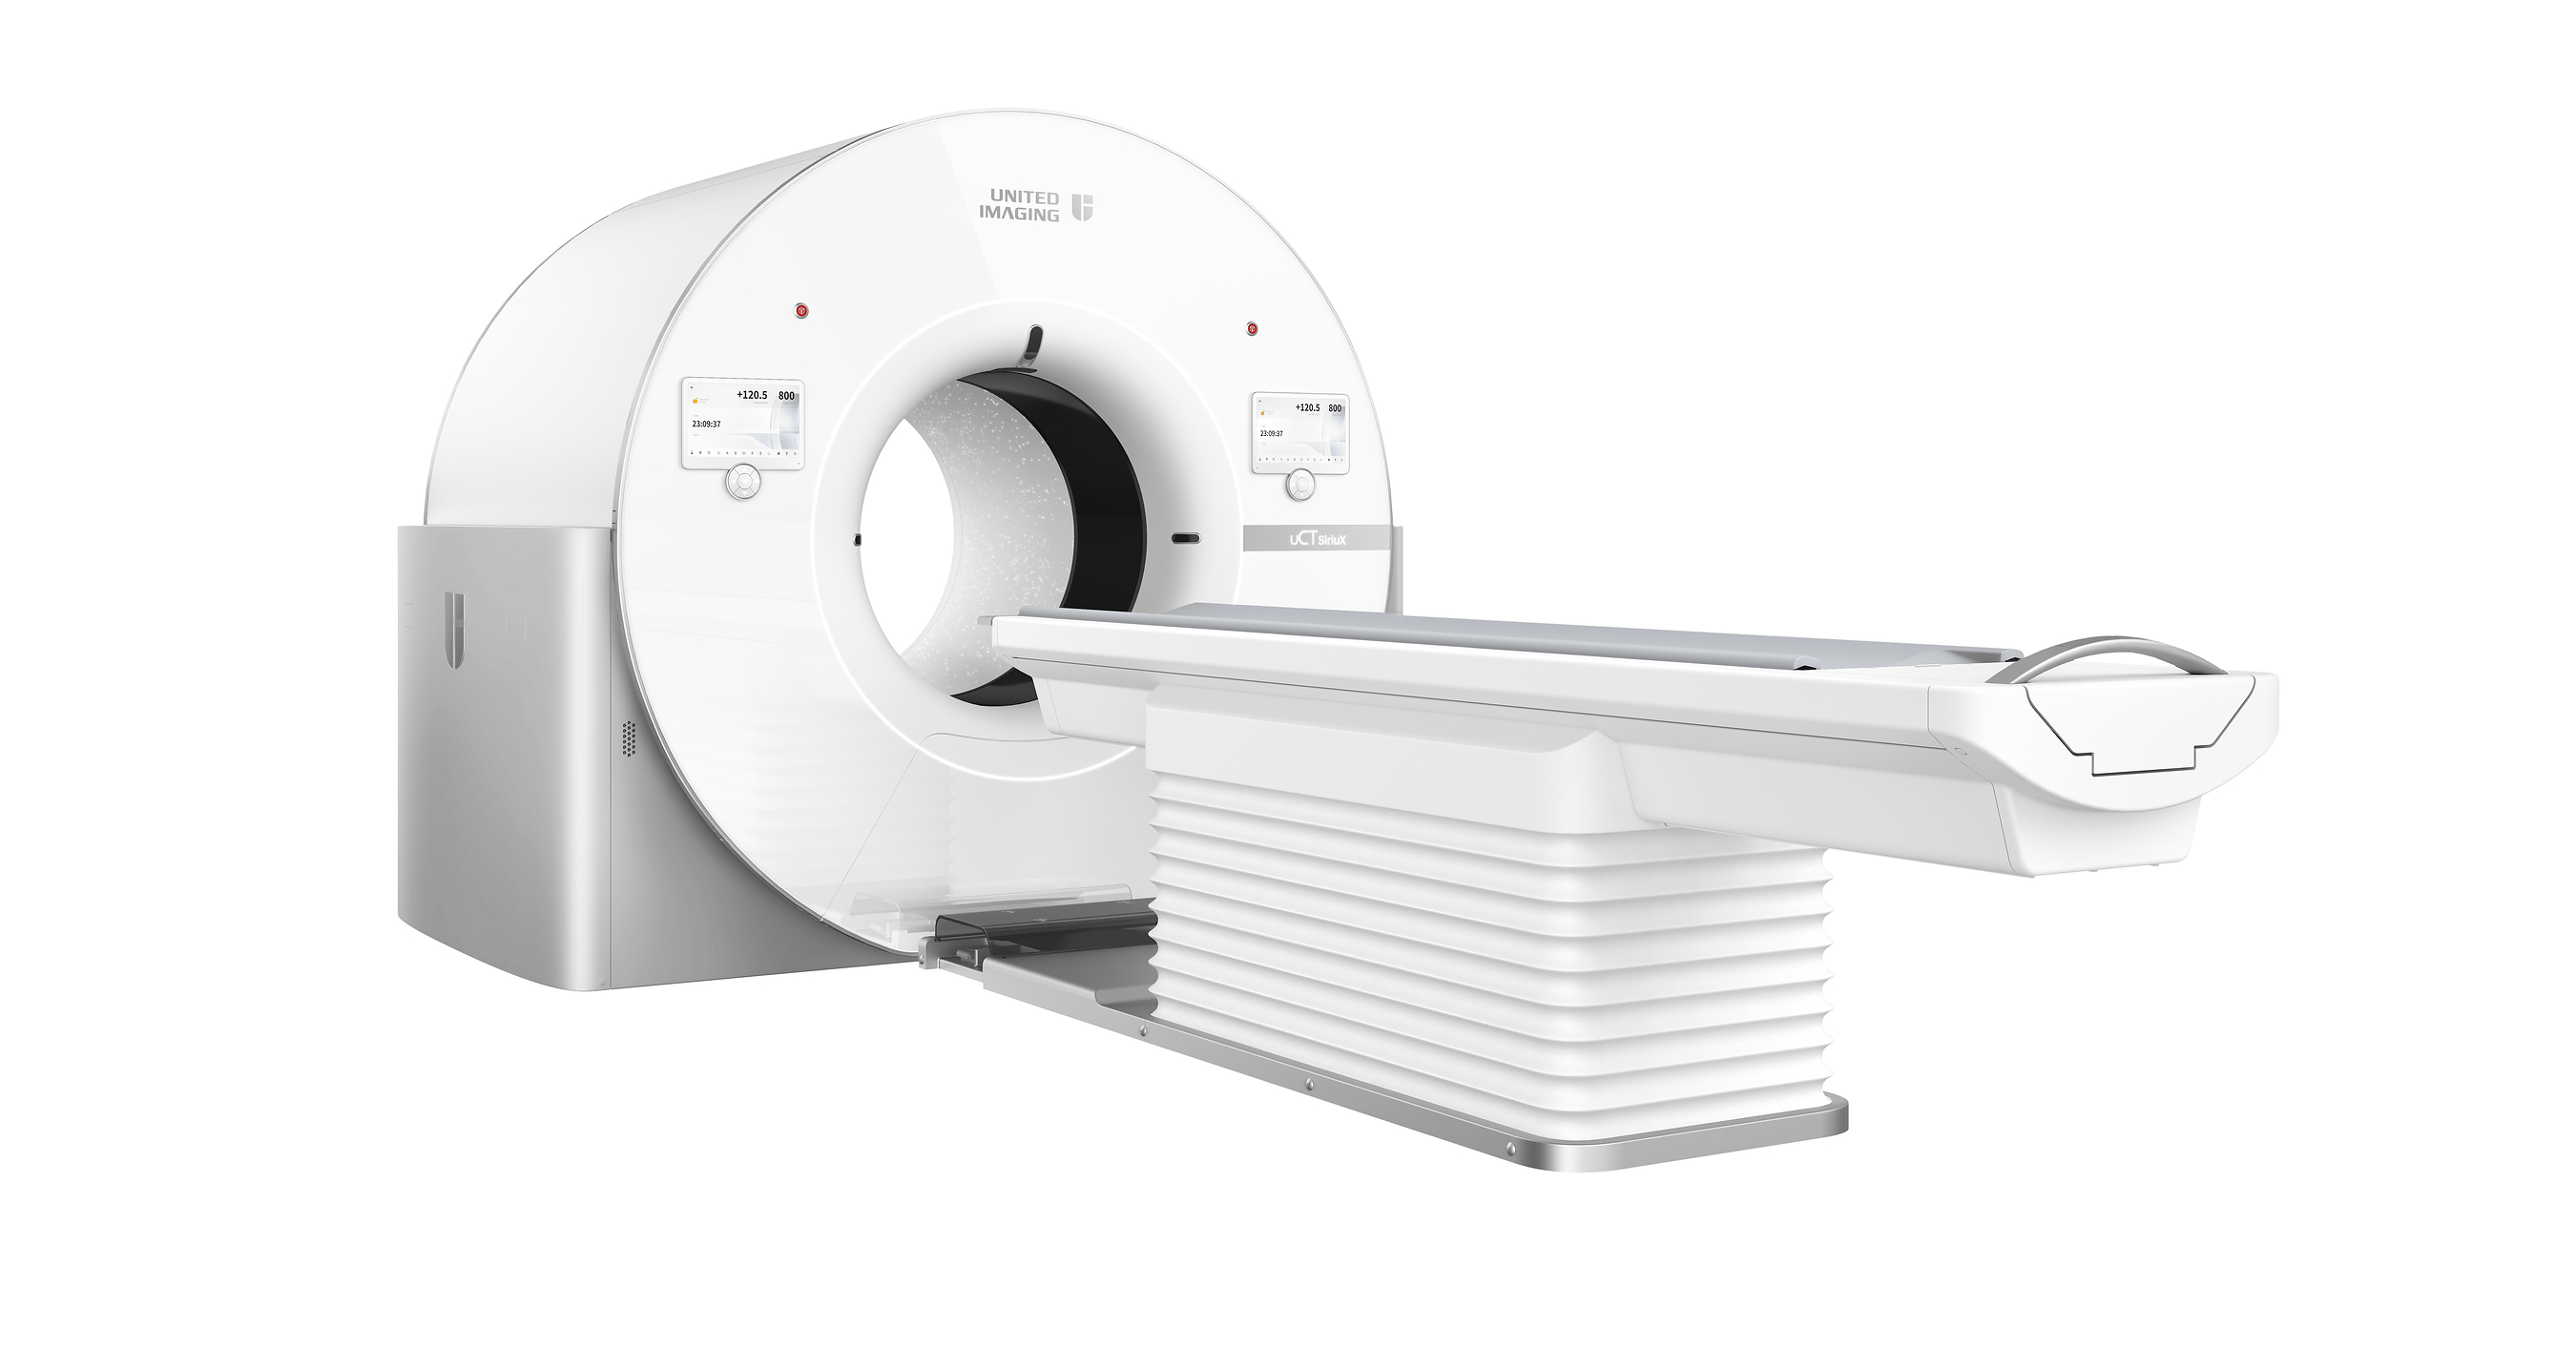
United Imaging received CE Mark certification for the uCT SiriuX and uCT SiriuX Ultrix, enabling commercial availability across Europe for its dual wide-coverage CT family. The platform’s Twin-Ring Gantry design combines 16 cm Ultrix detectors and two liquid-metal-bearing X-ray tubes to support synchronized whole-organ dynamic imaging, 16 cm ultra-high-resolution imaging, and whole-body spectral imaging for material characterization. This regulatory clearance is a positive step toward clinical adoption, though the article provides no revenue or financial impact figures.
Analysis
This is more of a commercial-option event than an immediate earnings event. CE access creates a path to European tenders, but CT procurement is a slow-motion process: reference-site adoption, service uptime, reimbursement fit, and radiologist preference typically determine whether “first-of-its-kind” becomes material revenue or just a marketing line. In the next 1-3 quarters, the main effect is likely on pipeline quality and valuation sentiment; the P&L impact probably shows up 6-18 months later, if at all.
The competitive read-through is most relevant for premium CT incumbents such as GE HealthCare and Siemens Healthineers, where the threat is less unit displacement than ASP pressure in the high-end segment. If the platform truly increases temporal and spectral performance, it could force competitors to defend premium pricing with heavier R&D and more aggressive bundles, which compresses near-term margin on new installs. The second-order beneficiary could be European hospital systems that gain a plausible alternative source, improving bargaining power against the incumbent duopoly.
The key risk is that CE mark is only the entry ticket: hospitals still buy on evidence, uptime, and service economics, not architecture labels. If the first wave of European installs is small, delayed, or concentrated in demonstration sites, the stock may fade after the initial headline reaction. The thesis would be falsified by weak booking conversion over the next two reporting cycles, or by any sign that reliability and workflow integration create clinical friction.
Contrarian view: the market may be overestimating how quickly a technically superior scanner translates into share gains. At the same time, it may be underestimating the option value if this becomes a reference platform for future tender wins and a broader upgrade cycle across oncology and cardiac imaging. The asymmetry is better as a watch item than a large risk-on expression until order data becomes visible.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- Do not chase the headline in the first 1-2 sessions; wait for evidence of European orders or named hospital reference wins before adding exposure to IDYLF.
- If channel checks confirm procurement traction, buy IDYLF on a 5-10% pullback with a 3-6 month horizon; upside is tied to booking surprise rather than near-term revenue, while downside is limited if adoption remains symbolic.
- Pair trade idea: long IDYLF / short GEHC or SEMHF on confirmed early Europe demand, targeting modest multiple compression in incumbents if premium CT pricing comes under pressure over the next 2-4 quarters.
- Set a watch item for the next two earnings calls: order backlog, installed-base commentary, and service response rates; a lack of conversion by then would argue the market has overvalued the CE mark.
More News
- CNBC Daily Open: Sanctions, strikes and the road to $100 oil
- Apple's $2000+ iPhone, Oil Gain Stokes Inflation Fear | Bloomberg Businessweek Daily 9/8/2026
- Dell (DELL) Q2 2027 Earnings Call Transcript
- Palo Alto Networks (PANW) Q4 2026 Earnings Call Transcript
- Marvell shares have soared 241% in a year. CEO says this is a key reason why
- Microsoft breaks Patch Tuesday record with 974-CVE deluge