
El grupo hotelero uzbeko TEG completa su fusión con una empresa estadounidense
Source: PR Newswire
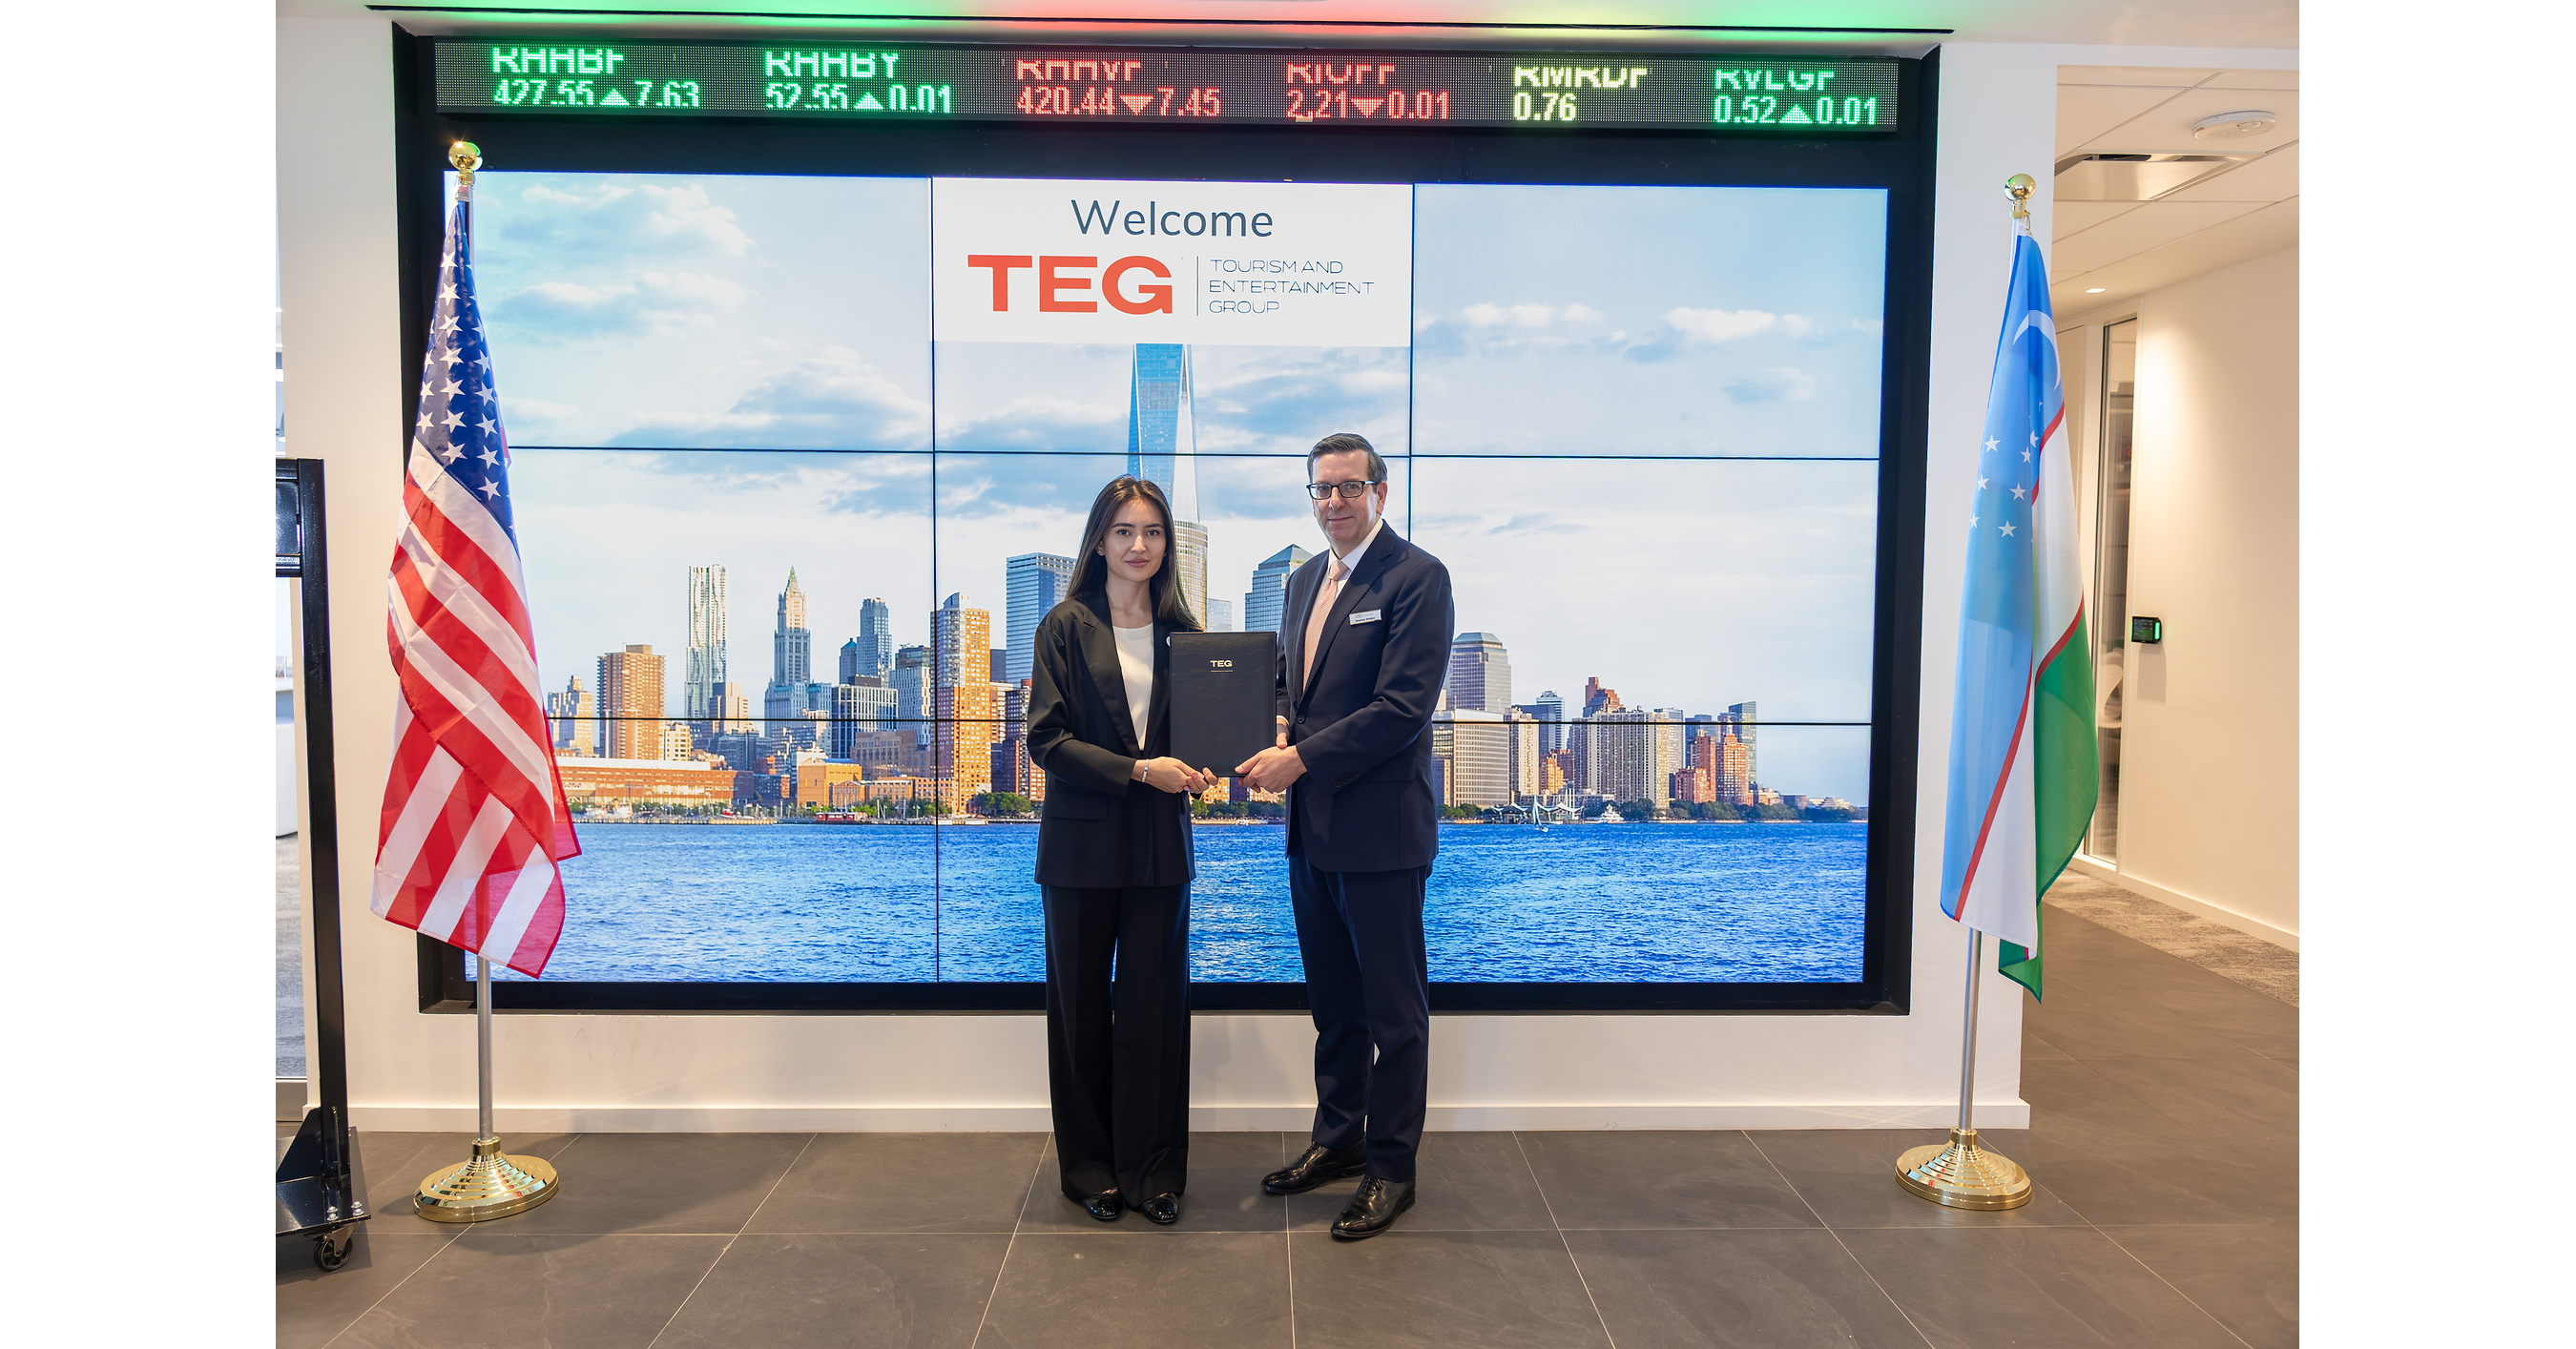
Uzbekistan-based TEG completed its merger with U.S. company StageWise Strategies, becoming the operating company of TEG Overseas, Inc.; its common shares are expected to trade on OTC markets. TEG reported 2025 revenue of $42.9 million, up 22% year over year, and net profit of $14.4 million, up 215%. The company plans to use access to U.S. capital markets to support acquisitions and expand its hospitality and MICE portfolio, amid Uzbekistan’s 11.7 million foreign tourist arrivals in 2025, nearly 47% above the prior year.
Analysis
The investable signal is not the tourism-growth narrative but the quality and monetization of the newly public vehicle. TEG’s reported earnings and growth are company-reported; before underwriting them, verify audited consolidated statements, cash conversion, debt and related-party transactions, plus the post-merger share count, lockups and public float. OTC trading can make headline valuation and exit liquidity poor proxies for fundamental value. The stated acquisition plan also creates dilution and execution risk: capital-market access is not equivalent to attractively priced, durable funding.
For HLT and WH, TEG’s branded properties could be a small source of franchise or management economics, but the article provides no fee terms or materiality. This is not a basis to alter either company’s earnings view. The more relevant second-order risk is local: rapid hotel and event-space expansion could intensify competition for labor, land and guests, limiting pricing even as arrivals rise. Conversely, conference demand can support weekday occupancy and reduce reliance on leisure seasonality if capacity and air connectivity keep pace.
Near term, the OTC listing may attract speculative attention but is vulnerable to thin-float volatility. Over 1–3 months, filings, merger capitalization and evidence of cash generation matter more than tourist-arrival headlines. Over 6–18 months, FX convertibility, country/policy risk, financing terms and acquisition discipline will determine whether growth creates shareholder value. The contrarian point: strong arrivals do not guarantee operator returns; capacity investment can absorb demand and impair returns before occupancy catches up. No listed HLT/WH trade is justified on this announcement alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.55
Key Decisions for Investors
- Do not change HLT or WH positions on the announcement: any TEG-related brand economics are unquantified. Revisit only if filings establish material fee exposure or a meaningful change in brand commitments.
- Keep TEG Overseas on a watchlist, not as an executable recommendation, until its OTC ticker, audited post-merger financials, share count/free float, debt, lockups and related-party disclosures are verified; avoid treating press-release earnings as normalized cash earnings.
- Over the next 1–3 months, track SEC filings and acquisition funding terms. Treat equity issuance, high-cost debt, weak operating cash conversion or material related-party transactions as thesis-negative; verified cash generation without substantial dilution would improve the case.
- For the 6–18 month tourism thesis, monitor hotel supply additions, air/rail capacity, FX convertibility and policy changes alongside arrivals. Rising capacity with weakening occupancy or pricing would falsify the assumption that tourism growth translates into attractive operator returns.
More News
- Anthropic's third-quarter revenue is said to hit $16.8 billion ahead of IPO
- Why is Samsung Electronics stock plunging today?
- SK Hynix seeks U.S. chip equipment exports to China tied to new factory
- Dell stock plunges 11%, leading data center sell-off on concerns about 'enterprise AI timing'
- US Stocks Tumble as Chip Rout Deepens
- UBS considers leaving Switzerland over capital rule plans, WSJ reports