
SoLo Funds Surpasses $100 Million in Revenue on Just $53 Million Raised: The Most Capital-Efficient Milestone in Fintech History
Source: PR Newswire
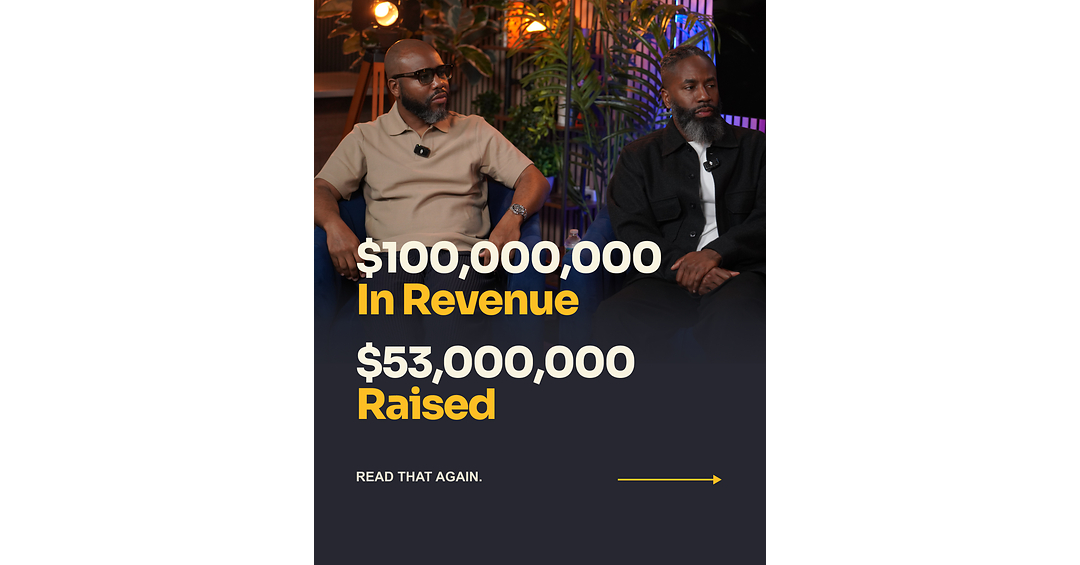
SoLo Funds surpassed $100M in total revenue after raising $53M in equity—nearly 2x revenue vs. equity capital raised—highlighted as exceptional capital efficiency versus peers like Revolut (~$340M), Chime (~$300M), and Robinhood (~$540M) that raised ~6–10x more before reaching the same revenue level. Since 2018, SoLo has facilitated ~$2B in transactions, onboarded ~3M members, and enabled over $760M in capital provided peer-to-peer. The article frames demand as durable despite fintech regulatory scrutiny, supported by risk/AI models that improve lending decisions and repayment performance.
Analysis
This is a private-company proof-point, not a market-moving earnings event. The investable signal is a slight rotation toward fintechs that can show organic growth and positive unit economics without constant equity dilution; in consumer finance, that only matters if lifetime loss-adjusted contribution margins are stable through a full credit cycle. Revenue efficiency alone is weak evidence unless it is paired with audited credit performance, cohort retention, and funding cost discipline.
If the model is real, the first beneficiaries are public fintechs with durable distribution and balance-sheet flexibility: SOFI, PYPL, HOOD and NU can all claim some version of capital-light scaling, while AFRM benefits only if investors want to pay up for underwriting tech rather than capital intensity. The likely losers are high-burn lenders and “AI underwriting” names where the market still underestimates loss severity; UPST is the cleanest relative short on any knee-jerk enthusiasm because better model efficiency does not eliminate cyclical default risk. Second-order, stronger demand for short-duration consumer credit may tighten spreads in subprime lending, but it also increases adverse selection as competitors chase the same borrower pool.
The contrarian view is that this is mostly a marketing release: without audited charge-offs, gross margin, and regulatory durability, the ‘capital efficiency’ claim could be front-loaded revenue from a narrow product set. Over 1-3 months, the key catalyst is third-party verification; over 6-18 months, the thesis breaks if credit losses rise, repeat borrowing softens, or CFPB/state scrutiny constrains the model.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.45
Key Decisions for Investors
- No direct trade in SBDS/SLNFF/SLXXF; treat as illiquid/watchlist names only unless there is a liquid OTC venue with tight spreads and verified borrow.
- Relative-value long SOFI / short UPST into the next earnings window: own the capital-efficient, diversified platform; fade the higher-beta underwriting story. Target ~2:1 upside/downside if fintech multiples re-rate toward profitability, with thesis invalidated if UPST shows materially better loss trends.
- If you want a cleaner expression of ‘fintech quality wins,’ use long PYPL vs short a basket of unprofitable consumer lenders; the trade only works if the market continues rewarding margin durability over growth optics.
- Set a watch alert for audited loss rates, delinquency vintages, and funding mix in any follow-up filing; do not add risk until those metrics confirm the press release.
More News
- Musk says Terrafab chip factory could outperform rivals despite challenges
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Stocks saw new highs and big declines: How the volatile AI trade moved last week's market
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- Last-Minute Lawsuit Upends Cable One’s $480 Million Mega Broadband Deal
- The world needs Ukraine’s grain. Its farmers are running out of reasons to plant
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Tools for Independent Research Firms: A Publishing System
- Weekly Update: Options, Earnings Call Transcripts, AI Chat, Bookmarks & More