
Banyan Group Announces Acquisition of Newmark Hotels & Reserves, Adding 26 Hotels, Lodges, and Reserves Across Seven African Countries
Source: PR Newswire
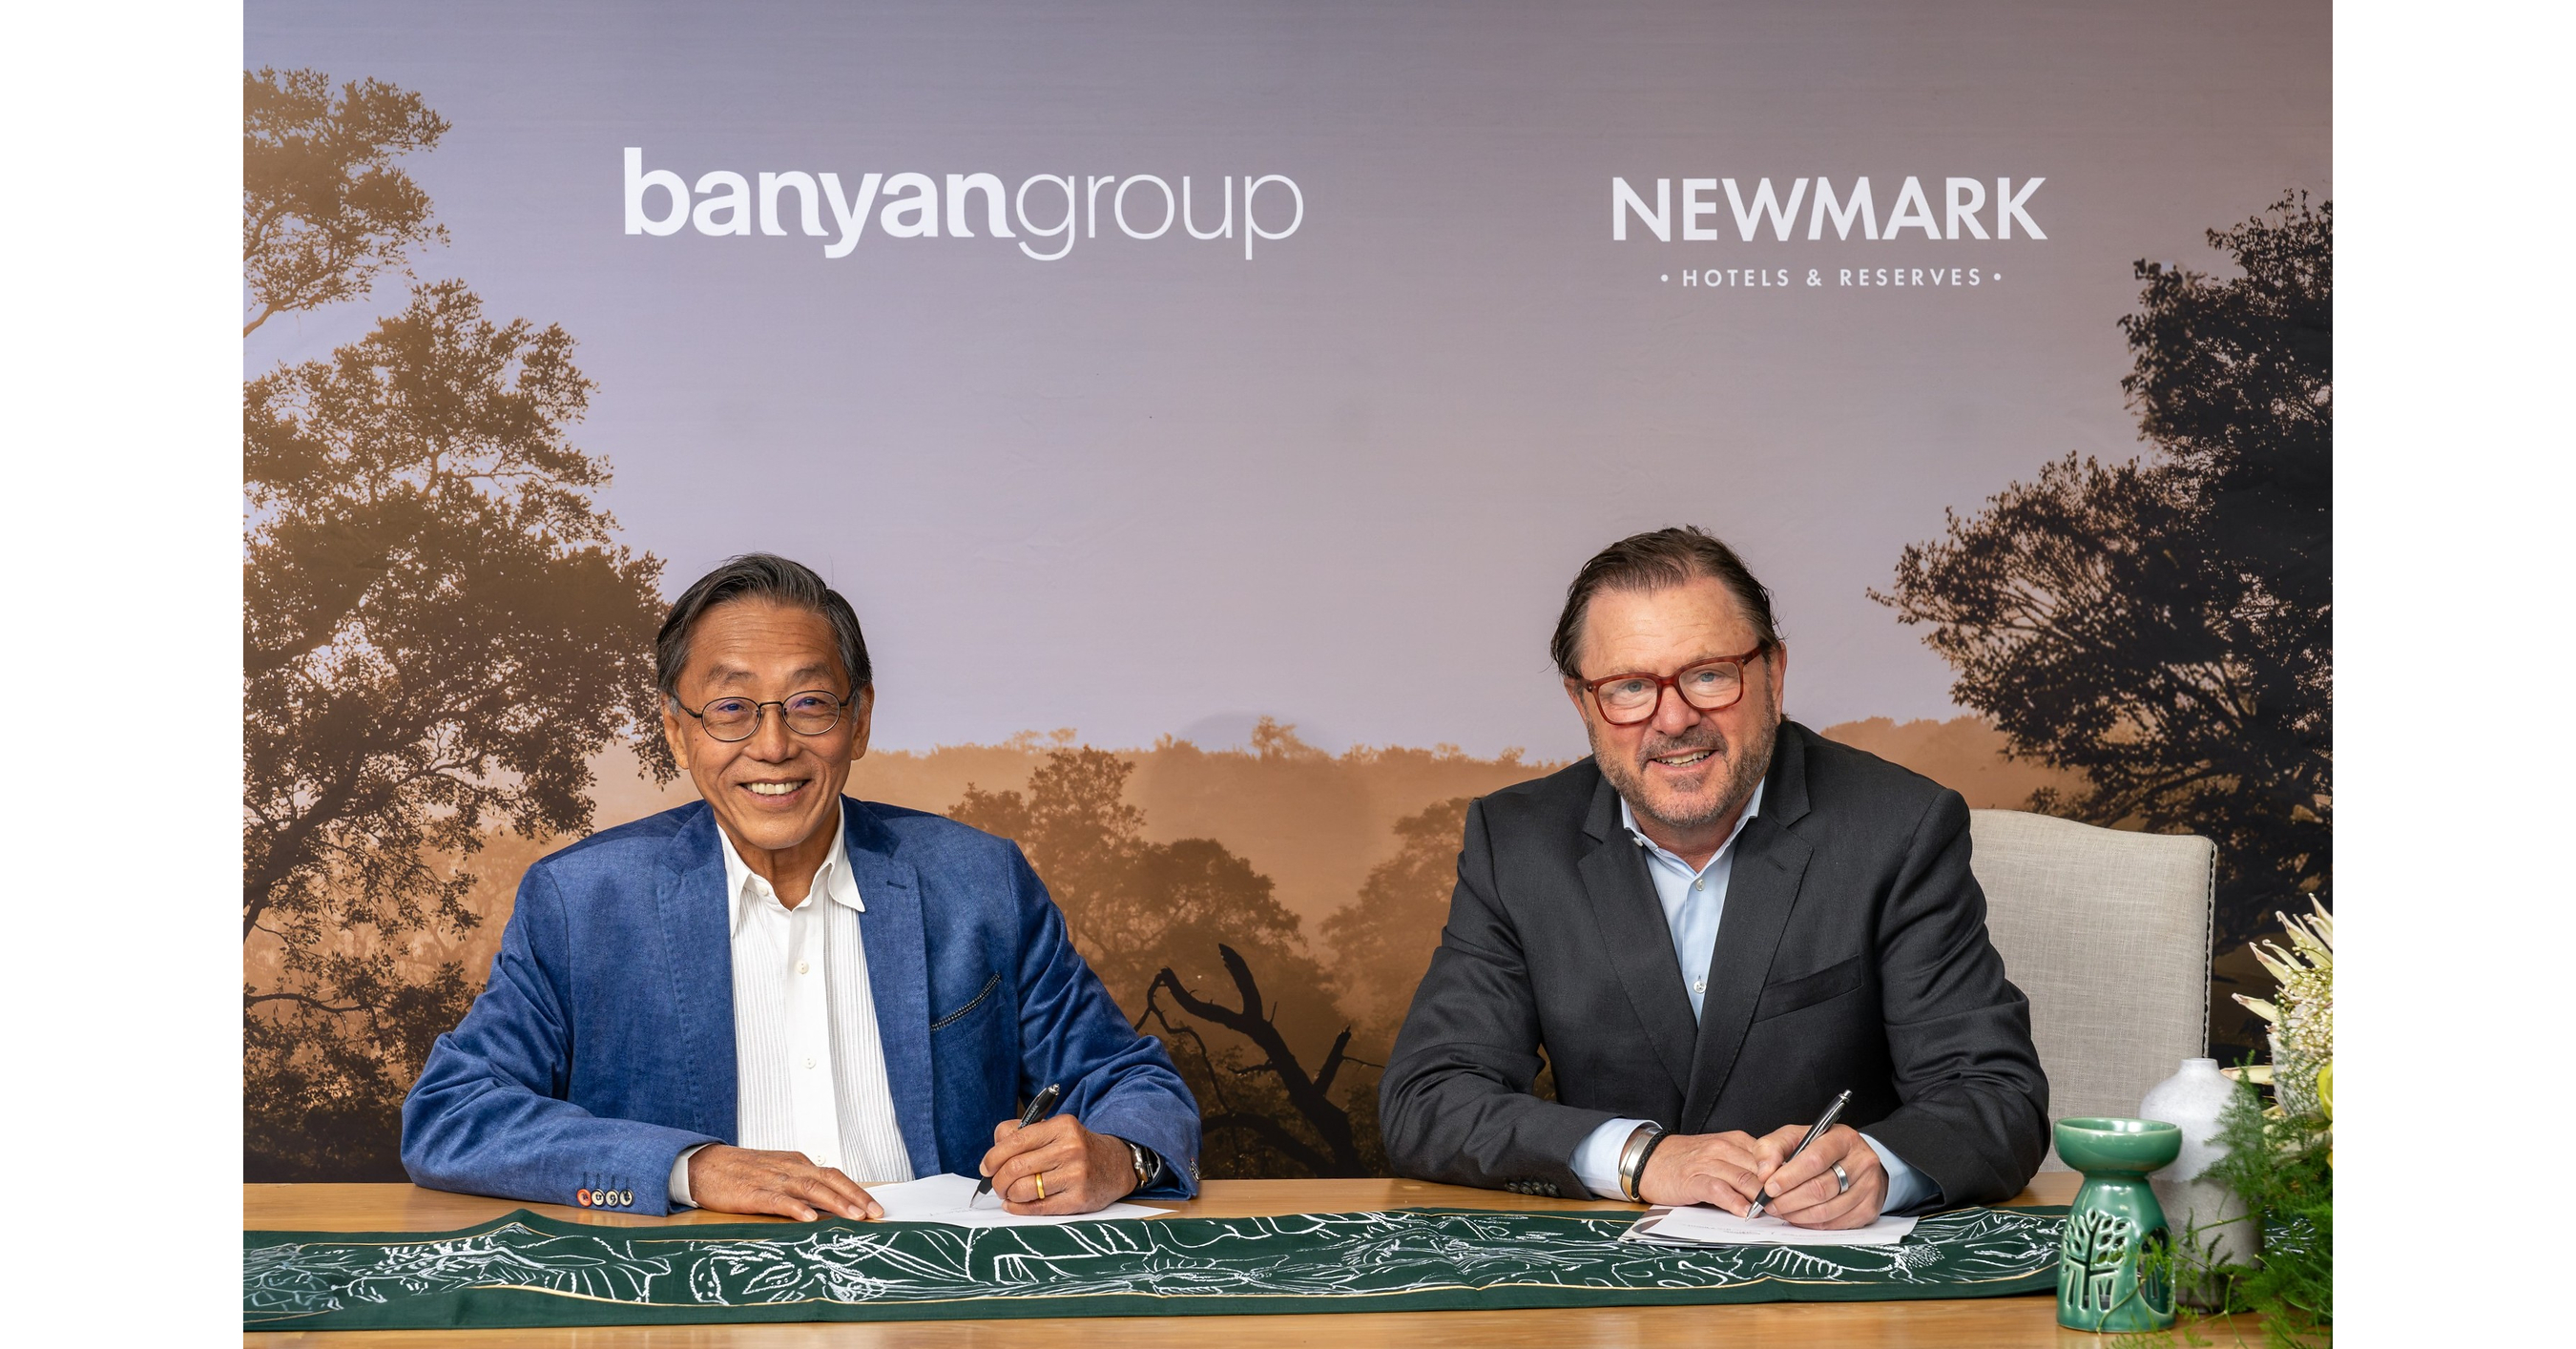
Banyan Group will acquire a majority stake in Cape Town-based Newmark Hotels & Reserves through a phased structure that will lead to full ownership over time, adding 26 managed hotels, lodges and reserves across seven African countries. The transaction expands Banyan's portfolio to nearly 130 hotels, resorts and reserves across 28 countries and strengthens its nature-based and wildlife hospitality platform in Africa. The deal targets a tourism market where international arrivals reached 81 million in 2025, up 8% year on year, with the regional travel and tourism economy projected to grow another 5.4% in 2026.
Analysis
The investable read-through is more favorable for Banyan Tree Holdings (SGX: B58) than the supplied NMRK identifier: NMRK is U.S. commercial-real-estate services company Newmark Group and has no disclosed economic connection to the African hotel operator. The absence of disclosed consideration, funding mix, EBITDA, management-fee base, and earn-out terms prevents a near-term EPS/ROIC conclusion; a phased purchase can be value-accretive only if the acquired contracts are durable and incremental central-sales/loyalty revenue exceeds integration and incentive costs.
B58’s strategic upside is asset-light distribution leverage rather than immediate owned-asset earnings. Bringing independent lodges into a global booking and loyalty ecosystem can lift international occupancy and ADR with limited incremental capex, but the benefit will likely emerge over 1-3 booking seasons, not in the next quarter. The key competitive pressure falls on regional independent operators that lack global demand capture; listed South African lodging proxies Sun International (SUI SJ) and City Lodge (CLH SJ) may face modest pressure at the premium leisure end if Banyan’s channels improve conversion in safari and resort destinations.
Consensus may overvalue the Africa-growth narrative before proof of monetization. Nature-based travel is capacity constrained by airlift, political/security perceptions, FX convertibility and conservation-related operating costs; these can overwhelm brand-distribution gains in individual markets. Over 6-18 months, successful cross-selling would support B58’s fee-revenue mix and a modest multiple re-rating, whereas rising central costs, property-owner churn, or weak RevPAR uplift would expose the deal as primarily portfolio expansion without earnings quality improvement.
Moelis (MC) should not be bought on this announcement alone: advisory attribution and fee economics are not disclosed, and a single middle-market mandate is immaterial to forward estimates. Watch B58’s next results for acquired fee/EBITDA contribution, integration costs, net-debt movement, and evidence of loyalty-platform bookings; those data points—not the announced property count—determine whether the transaction changes valuation.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.58
Ticker Sentiment
Key Decisions for Investors
- No trade in NMRK; treat the ticker association as a data-quality error. NMRK’s commercial-real-estate-services earnings have no apparent exposure to this transaction.
- Place B58 on a 1-3 month watchlist rather than initiating on the release. Consider a starter long only if management discloses consideration and the acquired platform is funded without material leverage while guiding to positive first-full-year EBITDA/fee contribution; invalidate on elevated leverage, material integration charges, or no quantified synergy framework.
- For African lodging exposure, monitor a relative-value signal: long B58 versus short SUI SJ or CLH SJ only after evidence of sustained international-booking/RevPAR outperformance at Banyan-affiliated African properties. Use a 6-12 month horizon; exit if regional airlift, FX restrictions, or security disruptions depress inbound demand broadly.
- Do not position in MC solely on advisory involvement. Reassess only if subsequent disclosures indicate a broader pipeline of hospitality cross-border mandates large enough to affect quarterly advisory revenue.
More News
- Nike bets on a millennial Arnault heir after bleeding $200 billion and being ousted from the S&P 100
- H.I.G. Capital Signs Definitive Agreement to Sell General Datatech
- Our top 10 things to watch in the stock market Thursday
- California AG Says Paramount-WBD Merger Would Hurt the State
- This AI-picked stock jumps 18% on Amazon’s $8 billion power deal
- US to Sell F-35s to Saudi Arabia in $24.3 Billion Deal