
Digital Mirror Pioneer YFORE Unveils Full Intelligent Mirror Lineup in North America
Source: PR Newswire
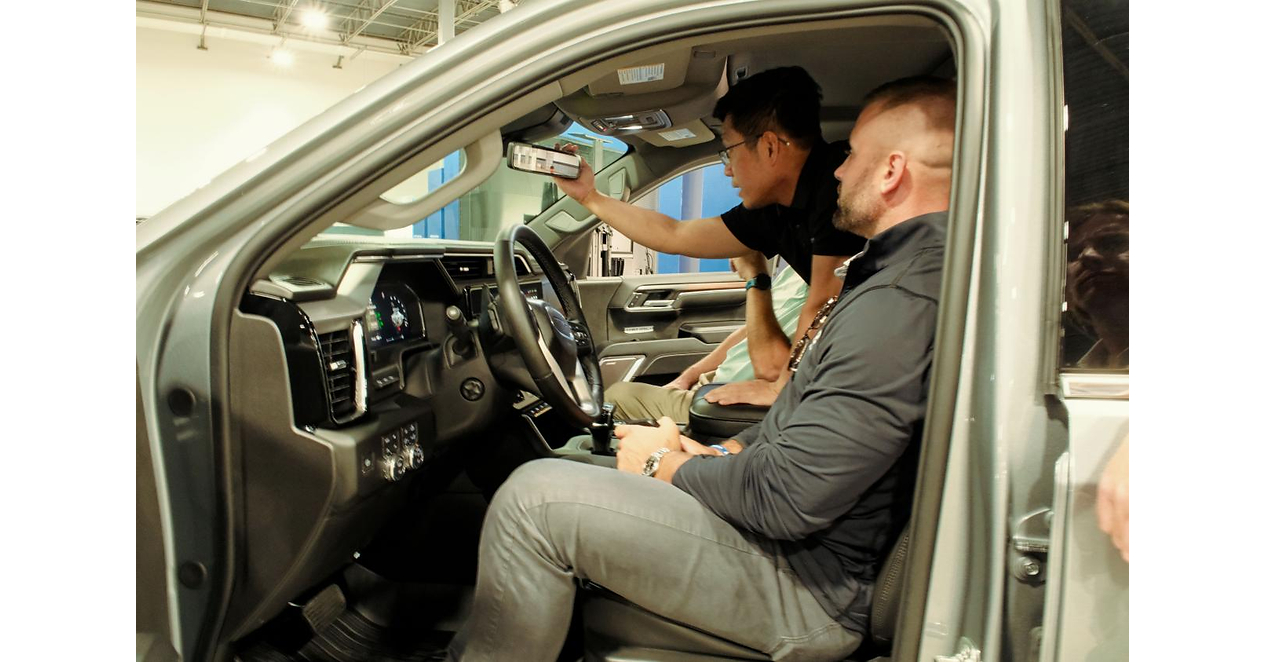
YFORE Technology commissioned a new U.S. manufacturing facility near Atlanta and simultaneously launched its full digital mirror lineup across North America. The centerpiece is a multifunctional interior mirror combining DMS and OMS for Euro NCAP five-star safety compliance, plus Face ID, gesture interaction, and in-cabin conferencing. The company highlights up to 8MP inputs at ≤25ms latency and brightness >2,250 cd/m², aimed at deployment across 60+ vehicle models for 16+ automakers.
Analysis
This is more a distribution and localization signal than a near-term earnings event. The first-order read is modestly negative for incumbents with legacy mirror content because a lower-cost, locally manufactured alternative can pressure take rates and pricing in a category that is already being structurally squeezed by cockpit consolidation. The second-order effect is more interesting: if OEMs accept a single module that bundles mirror, driver monitoring, and occupant monitoring, it can accelerate content concentration around a smaller set of Tier-1s and chip away at fragmented mirror-only suppliers over the next 12-18 months.
The likely beneficiaries are OEMs and platform integrators that want to reduce harness complexity and tariff/logistics risk, plus semiconductor/optics vendors that ride the attached sensing stack. The hurt is concentrated in legacy mirror and interior trim franchises, especially where margins depend on low differentiation and plant proximity, which makes this more of a pricing threat than a volume threat. For Gentex (GNTX) and Magna (MGA), the near-term risk is not displacement everywhere, but incremental spec losses on new-platform awards if YFORE’s local capacity proves real and is paired with NCAP-compliance messaging.
The key contrarian point: the market may overestimate how fast OEMs switch suppliers in safety-critical cabin electronics. Validation cycles, PPAP qualification, and software integration usually push revenue recognition out by quarters, so the stock impact is likely muted until actual SOP wins appear. What would falsify the bearish read is evidence of meaningful North American nominations, repeat SOPs, or margin-accretive content expansion; absent that, this is mostly a watch item, not a thesis changer.
Catalyst path matters: in the next 1-3 months, listen for OEM award language and any commentary from GNTX/MGA on DMS/OMS pricing. Over 6-18 months, the risk is broader platform substitution as digital mirrors become a gateway product for in-cabin sensing. If YFORE’s U.S. footprint is genuinely scalable, it can compress cycle times and weaken the "China-only supplier" discount that has protected some incumbents.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Key Decisions for Investors
- Watchlist, not a trade: monitor GNTX and MGA on upcoming earnings for commentary on DMS/OMS attach rates, pricing, and North America nominations; avoid forcing a position until actual award data confirms share shifts.
- If OEM award announcements emerge, consider a 3-6 month relative short GNTX vs. long a diversified auto-tech basket (e.g., MGA or APTV) to isolate mirror-content pressure from broader vehicle production beta.
- Set an alert for any evidence of YFORE SOPs with top-tier OEMs in North America; that would be the first point at which a short GNTX thesis becomes actionable, with thesis validity tied to pricing/margin commentary rather than product launches.
- For investors already long auto suppliers, hedge a small portion with short-dated puts on GNTX into earnings only if management signals accelerating competition in mirror/sensing content; otherwise expected impact is too small for standalone options premium.
- No immediate sector trade in AAPL/MBLY/ADSK-style autonomy proxies; the signal is about cabin integration and Tier-1 sourcing, not a broad ADAS re-rating.
More News
- ‘If nothing is done, it’s almost inevitable’: Ukraine’s Yuriy Ryzhenkov on why steelmaking is on the brink of collapse as Russian bombing intensifies
- Why is SK Hynix stock sliding today?
- TikTok CEO sees major scientific breakthroughs from AI within three years
- IIF CEO on Rising Global Debt
- TSMC expected to report sixth straight quarter of record profit thanks to AI boom
- CXMT: How big is its market threat to Samsung, SK Hynix and Micron?