
Lockheed Martin: Q3 Sparked Euphoria, But Factory Physics Matters More Than Paper Billions
Source: seekingalpha.com
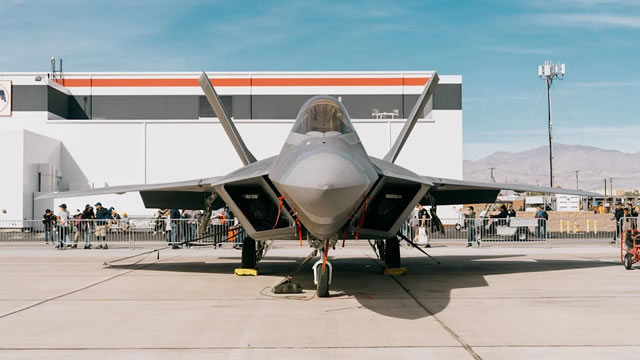
Lockheed Martin reported strong Q3 2026 results, raised annual guidance, and reached a record $292B backlog, driven by a major Patriot missile contract. Missiles and Fire Control is the company’s only significant source of physical growth; expanded capacity is expected to add $10B in annual revenue by 2031. Output ceilings in Aeronautics, Rotary, and Space limit organic growth to 4–6% annually, largely from missile exports and inflation indexing.
Analysis
The key issue is conversion, not backlog size: a large order book supports visibility only if appropriations, component supply, and delivery slots let Lockheed turn awards into recognized revenue without diluting returns. Concentrated expansion in Missiles and Fire Control raises execution risk and could shift the growth mix toward a single program family; capacity additions are not evidence of attractive incremental margins until contract economics and required investment are clear. A further risk is that higher Patriot output competes for skilled labor and scarce components across programs, potentially delaying deliveries elsewhere. If deliveries slip, the backlog can remain high while cash conversion disappoints.
Near term, guidance and order momentum may support sentiment, but the more consequential 1–3 month checks are funded awards, production-rate milestones, and segment margin/cash-flow commentary. Over 6–18 months, successful ramp execution could strengthen Lockheed’s position in air-defense procurement; it may also intensify competition for budgets and capacity faced by Raytheon, Northrop Grumman, and other defense suppliers. The contrarian point: investors may capitalize the announced revenue opportunity too early, while underweighting the time, investment, and execution required to deliver it. Conversely, a narrow focus on production constraints could understate the value of durable demand if funding and delivery performance hold.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.55
Ticker Sentiment
Key Decisions for Investors
- Do not chase the headline alone. Treat LMT as a conditional earnings-momentum long, adding only after subsequent disclosures confirm production-rate progress and stable or improving Missiles and Fire Control margins and cash conversion.
- Track funded contract awards, annual delivery volumes, segment margins, capital expenditure, and working-capital use. The announced capacity-linked revenue opportunity is an alert, not a bankable forecast, until these indicators corroborate it.
- Falsify the constructive view if management reduces delivery expectations, segment margins weaken during the ramp, or cash conversion deteriorates despite backlog growth; reassess promptly rather than treating backlog as protection.
- Watch procurement funding and supply-chain delivery schedules over the next 1–3 months. Delayed appropriations or persistent component bottlenecks would extend the growth timeline and could pressure defense-sector sentiment; successful ramp milestones would support the 6–18 month thesis.
More News
- Dow Heads for 3rd Weekly Win Despite Tech Turmoil
- Next week brings major risks for the stock market, just as the AI trade keeps faltering
- US-Iran war, then and now: How the landscape has changed since February
- With earnings in rearview mirror, SpaceX-Tesla merger chatter takes center stage
- Looters hit 3,000 French businesses. Within hours, the haul was trending on Vinted under the riot’s date
- Apple’s $2,000 iPhone Duo Debuts With Limited Supply