
The Diverse Appeal of Tourism and Cuisine in Japan Showcased at U.S. Event
Source: PR Newswire
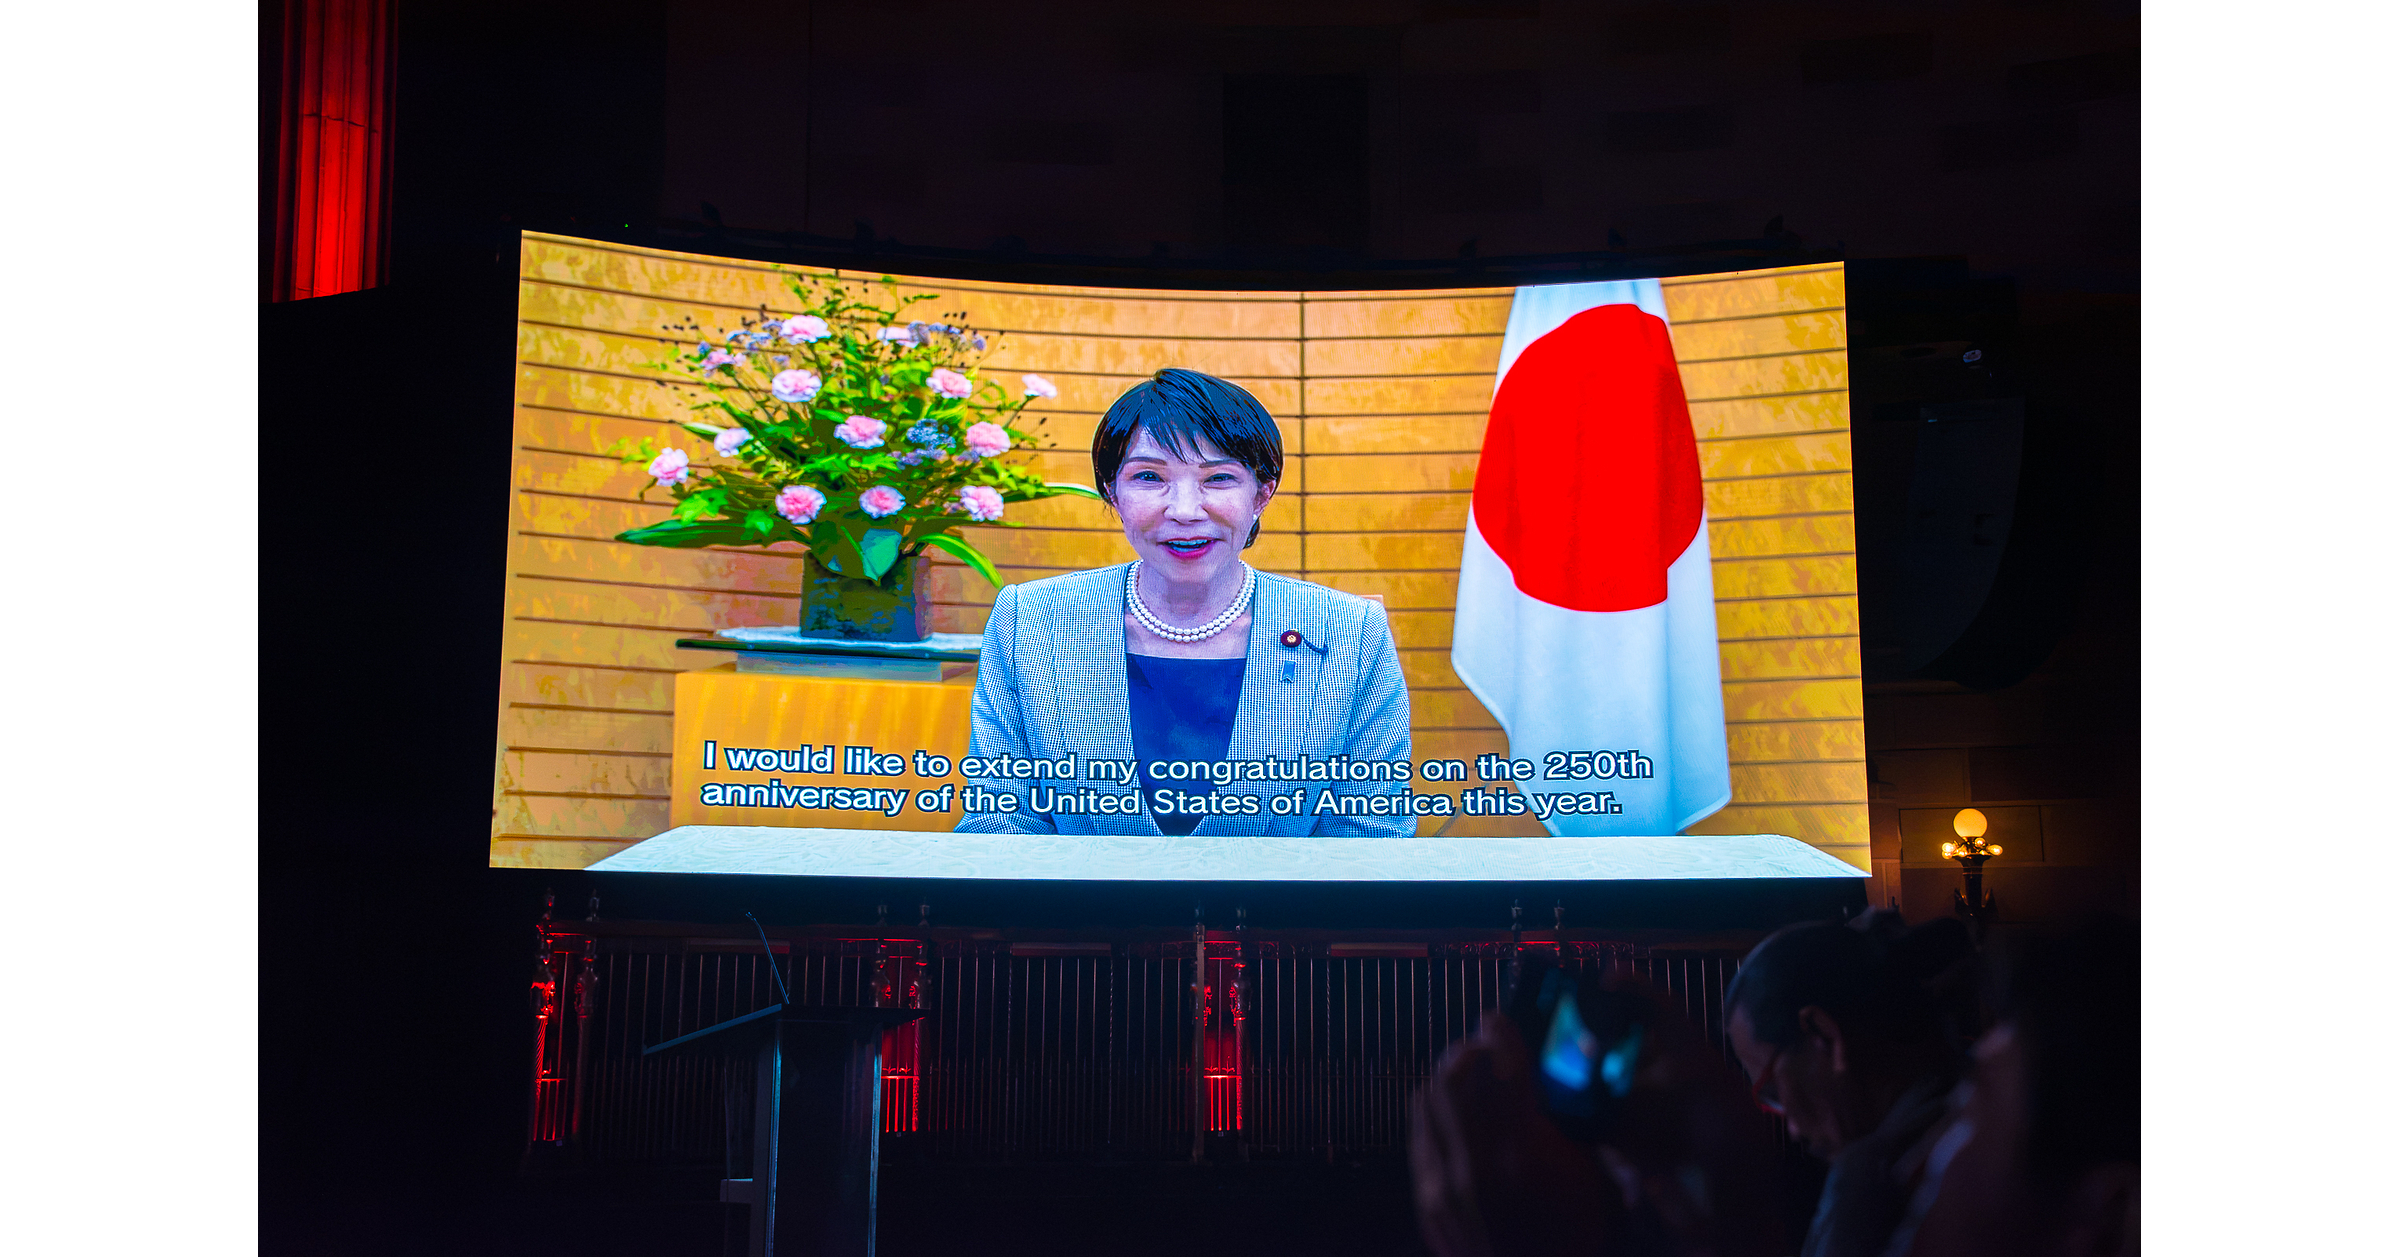
Japan's Tourism Agency hosted a Japan-U.S. Tourism and Culinary Night in New York attended by about 220 tourism, media, political and business representatives to promote inbound travel. The campaign highlighted newly UNESCO-listed Asuka and Fujiwara sites, regional food and cultural offerings, and United Airlines' planned direct service from San Francisco to destinations including Hokkaido and Okinawa. The event also promoted GREEN×EXPO 2027 in Yokohama, but represents promotional activity rather than a material near-term market catalyst.
Analysis
This is not a near-term earnings catalyst for UAL: incremental Japan leisure demand will be immaterial against consolidated capacity, and route profitability depends far more on premium-cabin yield, cargo contribution, and seasonal load factors than destination marketing. The relevant signal is that United is pursuing differentiated international network breadth, which can modestly support unit-revenue outperformance versus domestic-heavy peers if regional Japan service captures high-yield connecting traffic rather than merely diverting passengers from Tokyo routes.
The more investable read-through is for a gradual extension of Japan’s inbound-tourism cycle into secondary destinations, where room supply and airport infrastructure are tighter. That should favor Japanese lodging, rail, and airport operators more directly than a U.S. carrier, but most are not accessible through the supplied ticker set. For UAL, the thesis becomes actionable only if trans-Pacific revenue per available seat mile and international premium-cabin booking trends improve in 1Q-2Q results; a promotional event alone does not alter consensus EPS.
Contrarian risk is that expanded regional service dilutes yields if demand is predominantly price-sensitive leisure traffic or if the yen strengthens enough to reduce U.S. traveler affordability. A weaker Japanese currency and sustained U.S. consumer spending would support the route economics over 6-18 months, while a U.S. travel slowdown would expose the fixed-cost nature of long-haul capacity quickly.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Ticker Sentiment
Key Decisions for Investors
- No standalone trade on this item; treat it as a low-signal network-development datapoint rather than a revenue catalyst.
- Maintain a conditional bullish watch on UAL over the next 1-3 months: consider adding only if management reports improving trans-Pacific PRASM and stable international load factors while maintaining full-year EPS guidance. The upside case is multiple support from international mix; falsification is trans-Pacific yield deterioration or capacity-led margin pressure.
- For an existing UAL long, use the next quarterly earnings release as the decision point: retain exposure if international revenue growth exceeds capacity growth and premium-cabin trends remain positive; reduce if incremental Asia capacity is associated with lower unit revenue.
- Avoid extrapolating this into a broad U.S. airline trade. Domestic pricing, fuel, labor costs, and corporate travel remain materially larger earnings drivers for UAL than incremental leisure service to regional Japanese destinations.
More News
- United Airlines goes after top frequent flyers at Delta, American with status match
- Nike Warns Sales Slump Will Worsen This Fiscal Year
- Iran says it receives US response to latest proposal as Washington pulls out of Iraq
- Robotaxi operators will face fines for blocking first responders
- Google unveils latest AI model, but Wall Street wants a breakout personal agent
- Most Americans say US-Israel war on Iran not worth fighting: Poll