
HABANOS, S.A. HAT DEN MONTECRISTO FRAGATA VORGESTELLT, EINEN NEUEN REISEHUMIDOR EXKLUSIV FÜR DEN DUTY-FREE- UND REISEHANDEL
Source: PR Newswire
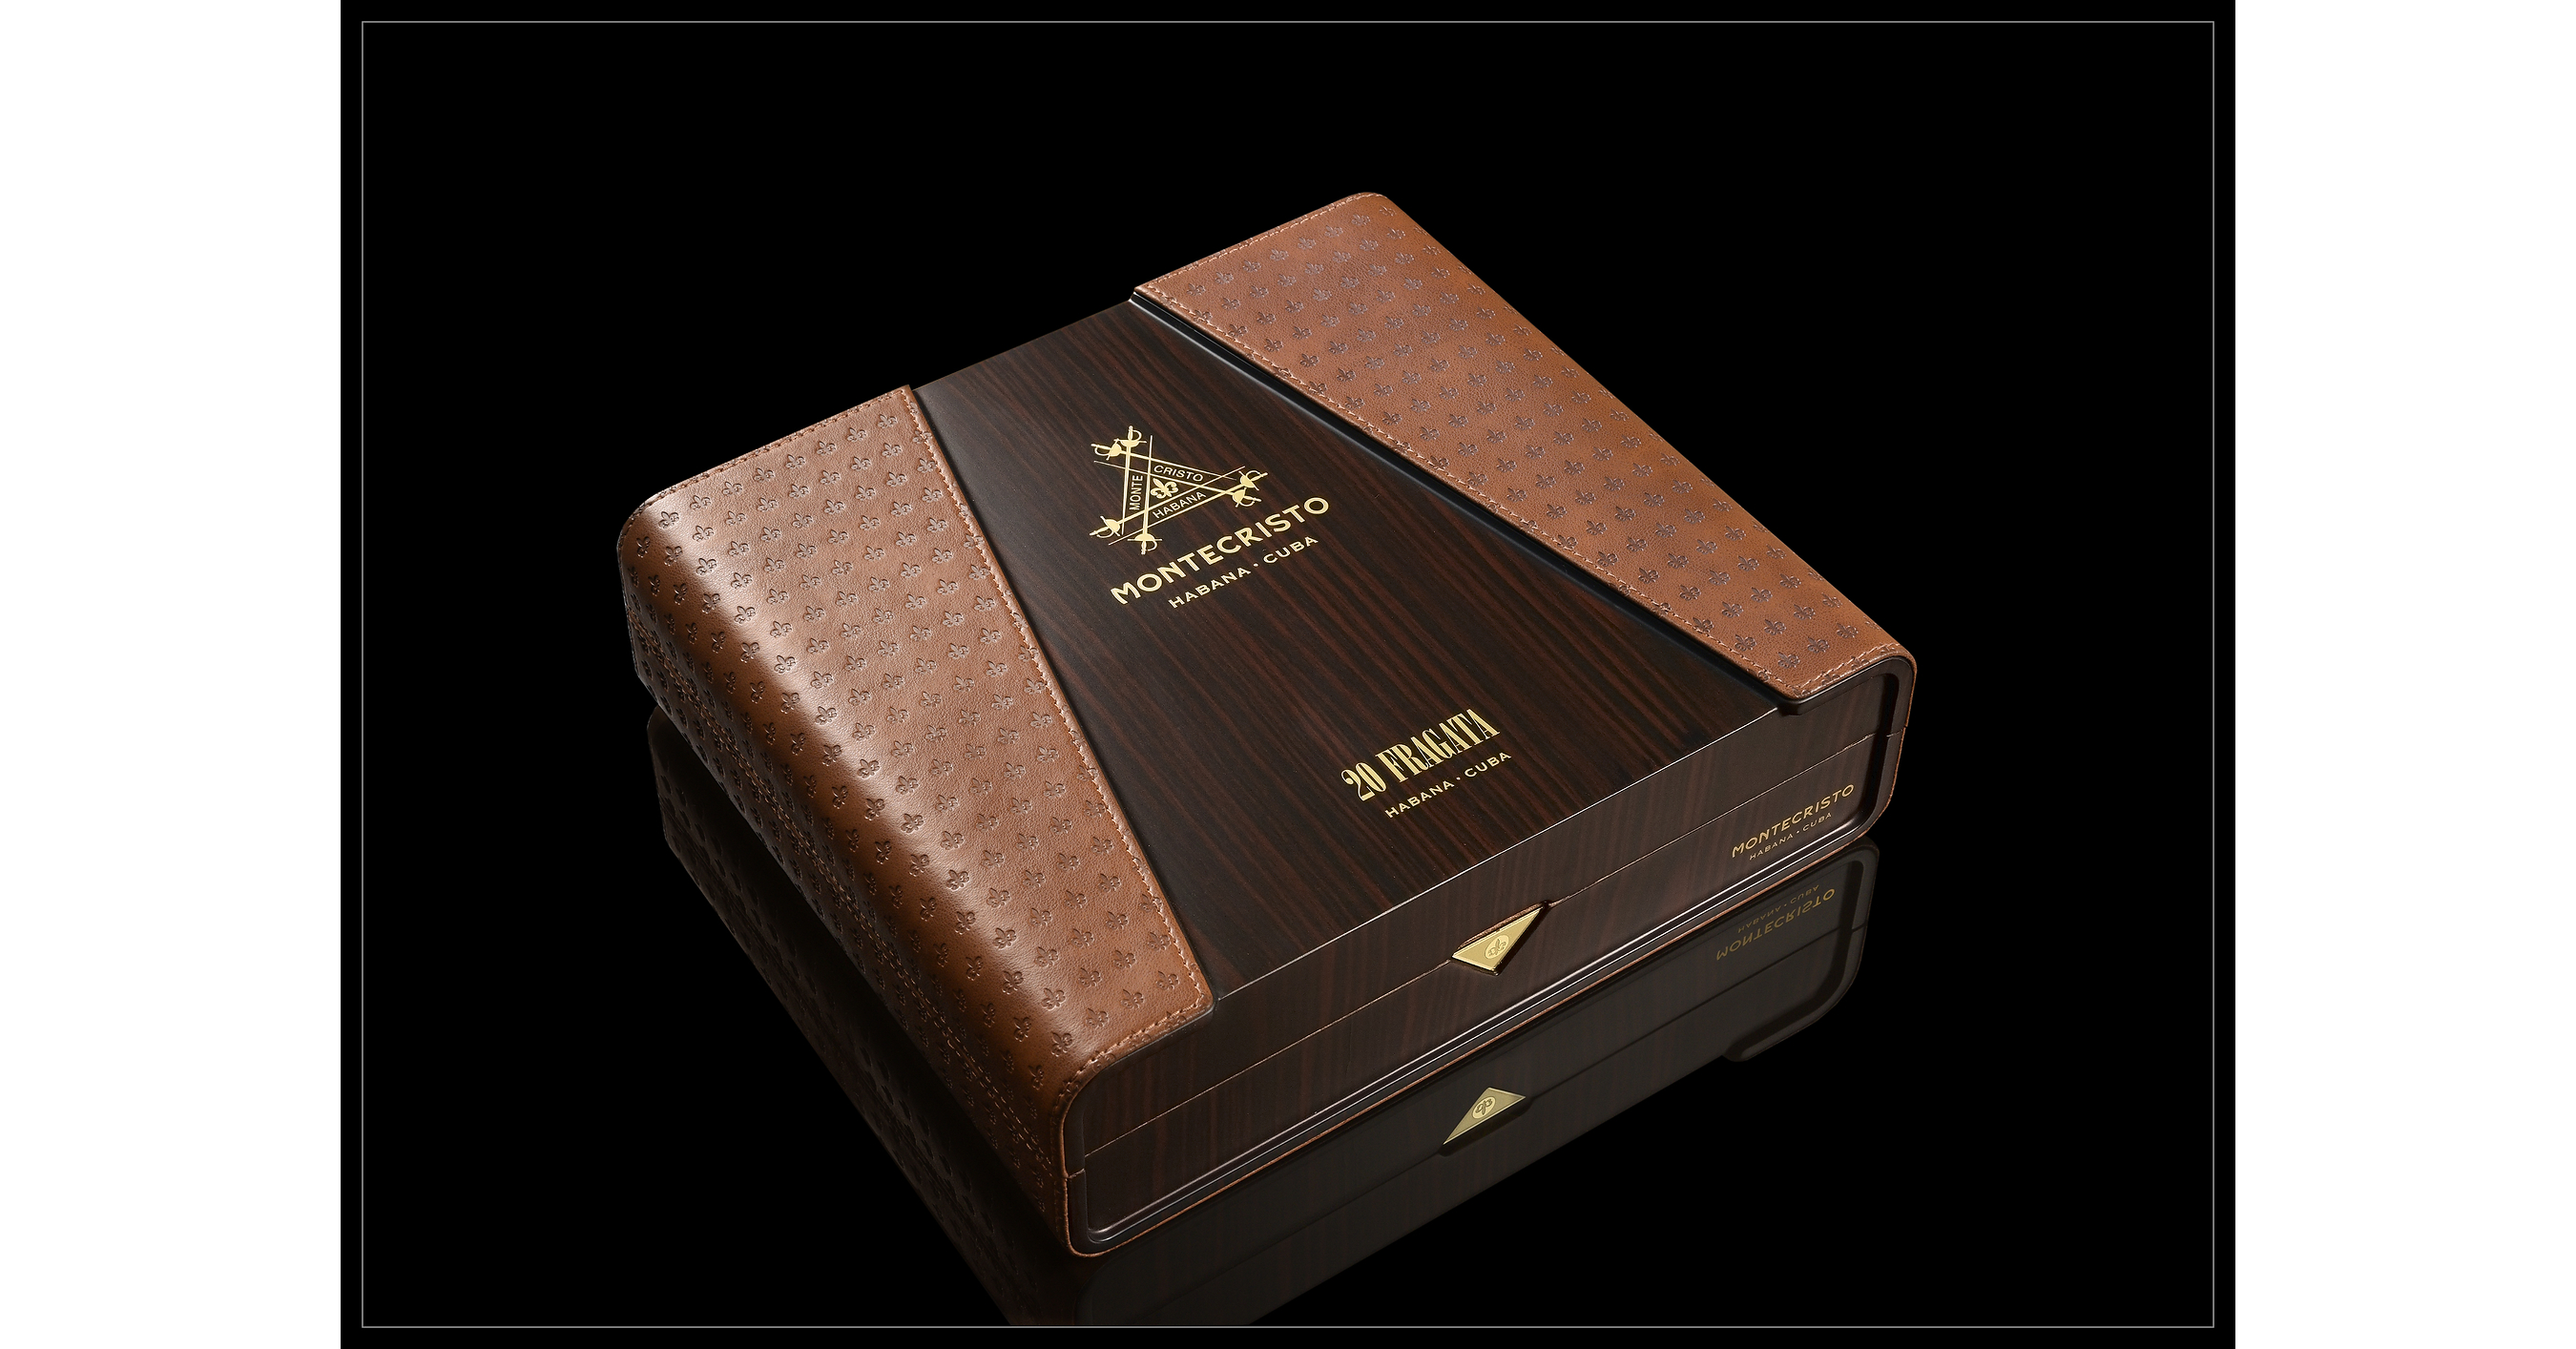
Habanos, S.A. launched the Montecristo Fragata, a duty-free and travel-retail-exclusive luxury travel humidor containing 20 cigars in a new 140 mm, ring-gauge-54 Duke format. The product, priced at a recommended $1,280/€1,100 per box ($64/€55 per cigar), extends Montecristo's travel-retail portfolio following the brand's 90th anniversary. The launch reinforces Habanos' premium positioning but is unlikely to materially affect broader markets.
Analysis
This is a mix-management signal rather than a meaningful demand catalyst. The relevant listed read-through is Avolta (AVOL.SW), whose airport retail economics benefit disproportionately from high-ticket, low-space products: a premium cigar case can lift sales density and gross-profit dollars without incremental store footprint. However, a single supplier SKU will be immaterial to group revenue; any near-term equity reaction would be unjustified absent evidence of broader premium-category acceleration in airport spend.
The more useful second-order indicator is whether travel-retail operators can sustain luxury basket growth while passenger volumes normalize. If affluent international travelers continue trading up, AVOL.SW and luxury-exposed airport operators AENA.MC and ADP.PA gain through concession sales-linked rent and stronger tender economics over the next 6-18 months. Conversely, restrictions on smoking, tighter airport tobacco-display rules, or weaker long-haul Chinese/European traveler spending would make tobacco one of the first discretionary categories to weaken, with the effect concentrated in travel-retail mix rather than airport passenger counts.
Contrarian view: exclusivity can create initial collector demand but also caps distribution and repeat purchasing, so it is not evidence of a broad premium-consumption inflection. The unusually high unit price makes sales vulnerable to foreign-exchange effects and duty-free pricing gaps versus local markets. Treat this as a watch item for upcoming travel-retail disclosures, not a standalone tobacco or airport trade catalyst.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No standalone trade on this launch; expected financial impact is below materiality for listed travel-retail and airport operators.
- Maintain AVOL.SW on a 1-3 month watch list: upgrade only if quarterly reporting shows airport luxury/tobacco category growth exceeding passenger growth by more than 3-5 percentage points and gross-margin expansion. Falsifier: category mix decelerates despite rising traffic.
- For an existing travel-recovery book, prefer a modest long AVOL.SW versus short a broad European consumer-discretionary basket over 6-12 months only if premium spend per passenger remains resilient; the hedge protects against a general soft-landing consumption slowdown while isolating airport captive-demand economics.
- Monitor AENA.MC and ADP.PA concession-revenue-per-passenger trends over the next two reporting periods. A decline in retail revenue per passenger alongside stable traffic would signal traveler basket compression and argue against adding airport exposure.
More News
- Nike Warns Sales Slump Will Worsen This Fiscal Year
- Google unveils latest AI model, but Wall Street wants a breakout personal agent
- Most Americans say US-Israel war on Iran not worth fighting: Poll
- Wilbur Ross was Trump’s first-term tariff hawk. Now he says refunds give importers ‘an extra profit’ and pay them ‘more than the money’ they laid out
- Cullinan initiates FDA filing for lung cancer drug zipalertinib
- Nike's troubles are mounting, and sales could fall further