
MSA Safety bringt en A1X auf den Markt: den WinGrip-Vakuumanker der nächsten Generation für die Flugzeugwartung
Source: PR Newswire
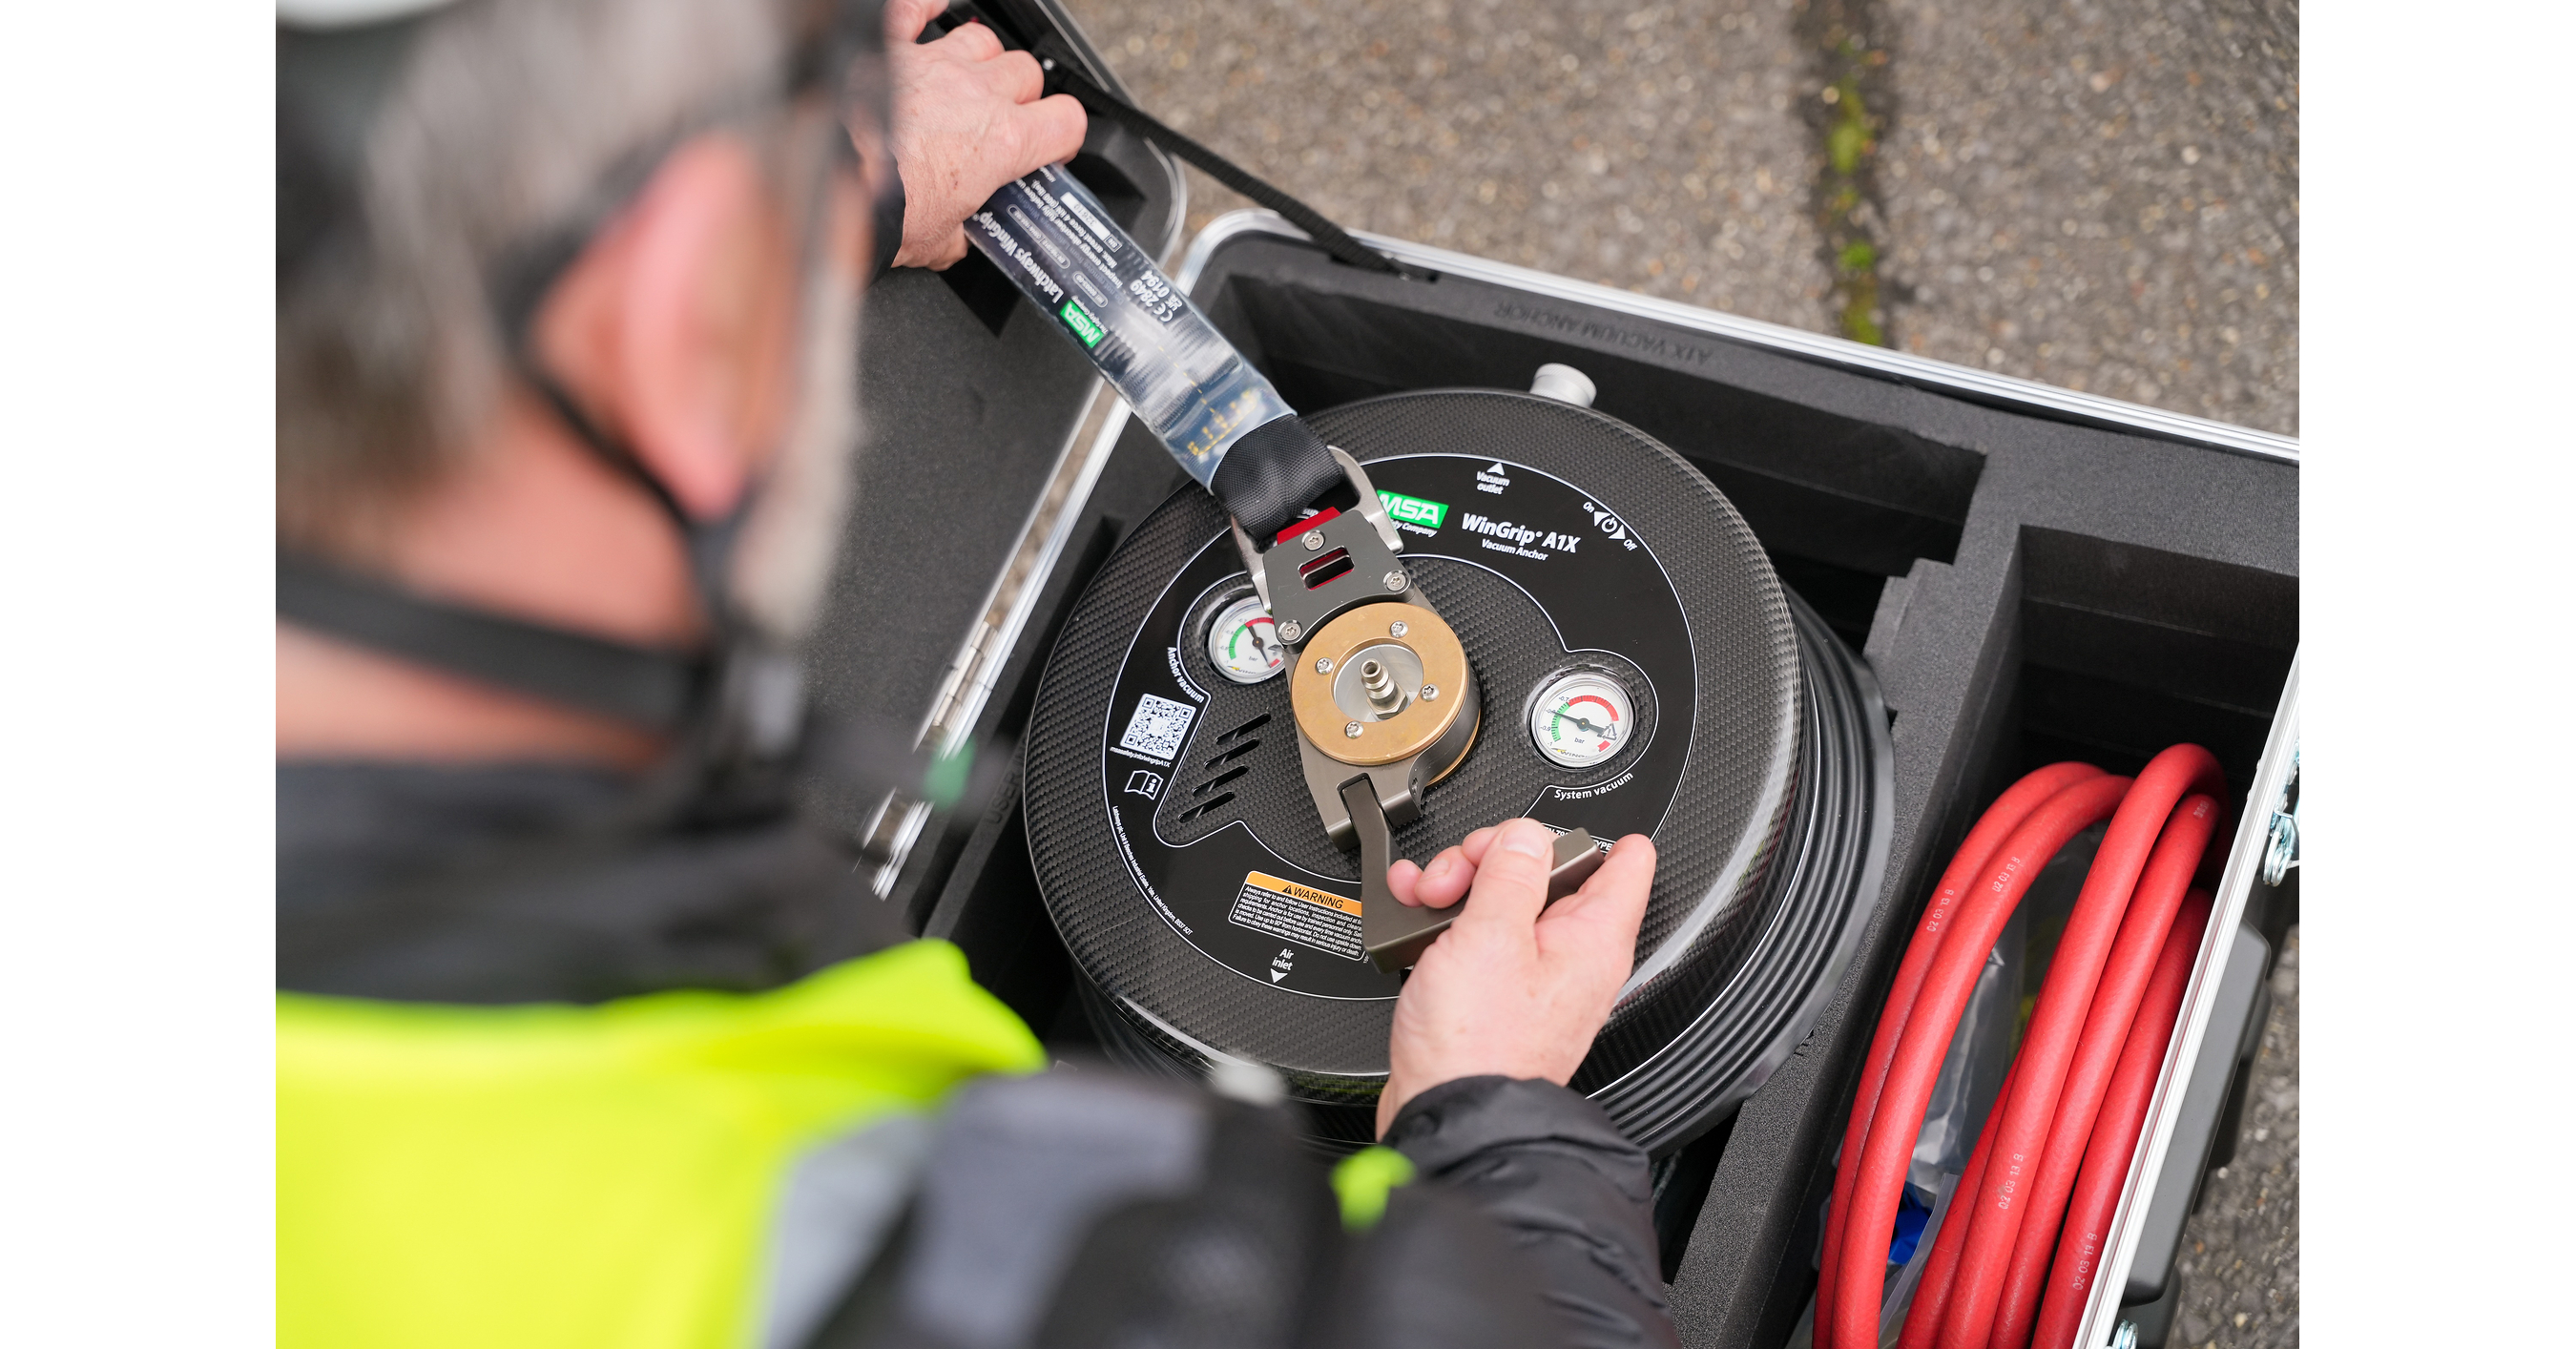
MSA Safety launched the A1X WinGrip vacuum anchor for aircraft maintenance, a 7 kg unit that is 35% lighter than its predecessor and has a 350 mm diameter versus 480 mm previously. Its redesigned pneumatic system doubles the number of anchoring positions achievable per gas cylinder, while smaller suction cups expand compatibility to business, private and commercial aircraft. The product, approved for use by major aircraft manufacturers including Airbus and Boeing, will be displayed at MRO Europe in October 2026; the release provides no revenue or guidance impact.
Analysis
This is strategically constructive for MSA’s aviation vertical but unlikely to alter consolidated estimates without evidence of fleet-level MRO adoption. The economic value is less the hardware unit sale than a potential shift from fixed fall-protection infrastructure toward portable, recurring replacement/service demand; that can support mix and pricing if MSA bundles PPE, cylinders and inspection support. The broader aircraft addressable base expands the sales funnel, but aviation MRO purchasing cycles are qualification-driven, making conversion more likely over 6-18 months than in the next quarter.
Near term, MRO Europe demonstrations are a commercial-validation catalyst rather than an earnings catalyst. Independent evidence to watch is named airline/MRO customer wins, distributor stocking, and management disclosure of aviation growth or gross-margin contribution; absent these, the launch should not justify multiple expansion in MSA. Honeywell (HON), 3M (MMM), and specialized fall-protection vendors face limited direct displacement initially, while BA and Airbus (AIR) have negligible financial sensitivity: improved maintenance workflow is operationally helpful but too small relative to OEM delivery, supply-chain, and aftermarket drivers.
The contrarian view is that the product’s portability may cannibalize some higher-ticket installed or full-line-system deployments, limiting revenue per maintenance site even if units grow. Conversely, if labor constraints force MROs to prioritize single-technician workflow and turn-time reduction, adoption could exceed a conventional safety-equipment replacement cycle. The thesis is falsified if early customers continue to require fixed infrastructure or if certification/airframe-specific operating restrictions limit use on the smaller-aircraft segment.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Ticker Sentiment
Key Decisions for Investors
- No standalone BA or AIR trade: the implied maintenance-efficiency benefit is immaterial versus their primary earnings drivers over the next 1-3 months.
- Maintain MSA on a 6-18 month watchlist rather than chase launch-day strength. Upgrade only after at least two independently disclosed MRO/airline deployments or management quantifies aviation order growth and confirms no gross-margin dilution.
- For an existing MSA long, use the October MRO Europe event as a checkpoint: add only if customer demonstrations translate into orders or distributor commitments; reduce incremental exposure if the messaging remains product-led without commercial metrics.
- Monitor HON and MMM only for signs of portable-anchor price competition; a meaningful risk to MSA’s thesis would be discounting or rival portable systems that prevent premium pricing. No pair trade is warranted with current information.
More News
- Why popular airplanes are getting scrapped years early
- Could France’s debt crisis spread across Europe?
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Iran says won’t allow US warships to get close as Trump ponders new attacks
- Biotech stocks are surging. How investors can play the new drug innovation boom
- Braskem creditors, shareholders near deal on $11bn debt restructuring
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Reading Conviction in the Tape: What Level 3 Order Book Data Really Tells Discretionary PMs
- AI Tools for CFA Charterholders: An Evidence Standard