
Envision Energy Launches Model T - EN175/8.0 Onshore Wind Turbine, Advancing Plant-Wide Optimization and Lifecycle Value for Future Energy Systems
Source: PR Newswire
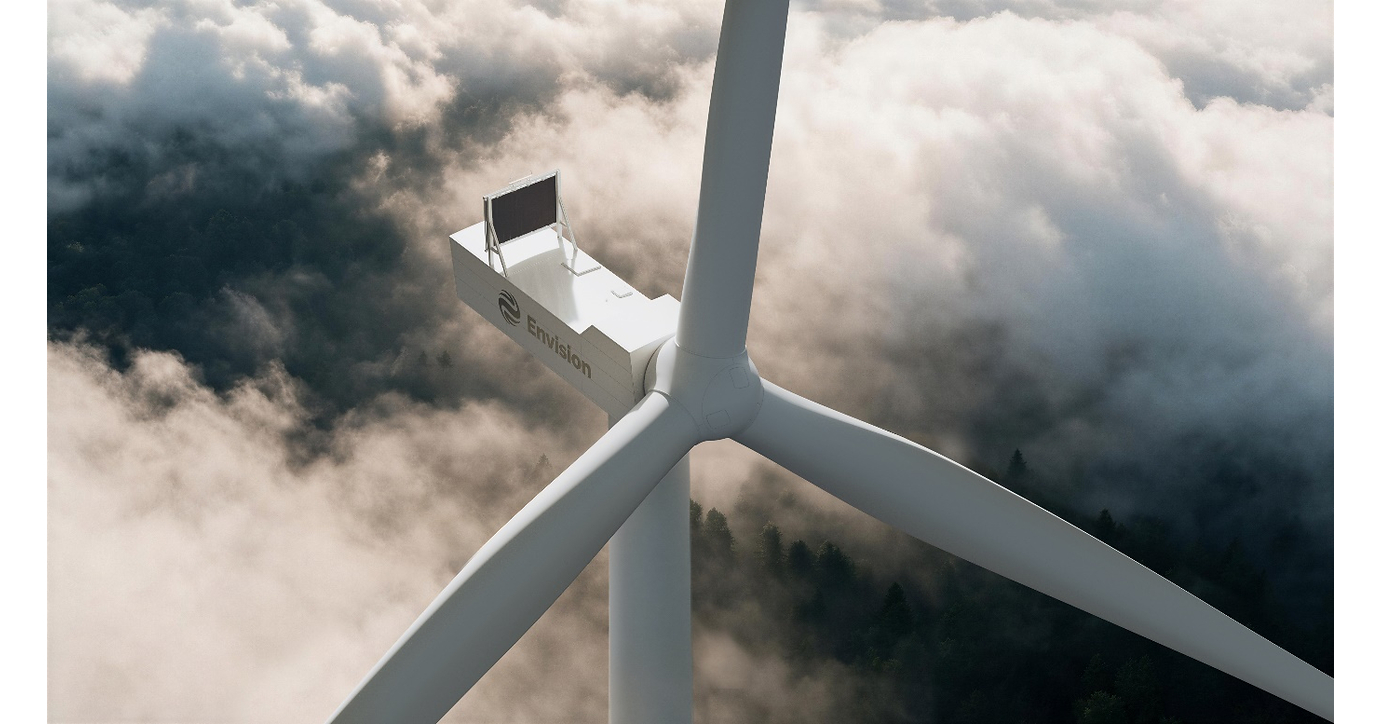
Envision Energy launched its Model T EN175/8.0, an 8 MW onshore wind turbine with a 175-meter rotor, targeting medium-wind and complex sites. The company says the turbine can raise energy yield by 2% to 12% versus existing models and targets a 107 dB(A) sound-power level, with optional low-noise modes. AI-enabled Galileo controls and grid-forming capabilities are intended to improve autonomous operation, grid support and plant-wide optimization across wind, solar, storage and industrial loads.
Analysis
The relevant market signal is not a near-term revenue event for listed peers, but a potential reset in onshore tender specifications: higher-rated machines can lower balance-of-plant and permitting cost per MW while raising the penalty for subscale product portfolios. Vestas (VWS.CO/VWDRY), Nordex (NDX1), and Siemens Energy (ENR) face selective pricing pressure in medium-wind export markets if the product clears independent certification and secures project financing. The claimed yield benefit should be discounted until third-party availability, power-curve, and service-cost data are published; turbine launches frequently trade initial output for field-reliability risk.
Over the next 1-3 months, the catalyst is customer order disclosure rather than the launch itself. European incumbents retain advantages in local content, established service networks, bankability, and procurement eligibility, so competitive impact will be greatest in emerging-market tenders and China-adjacent export markets rather than core EU projects. A larger rotor also increases transport, crane, and site-access constraints; this can shift value toward developers with suitable project pipelines rather than universally expanding the addressable market.
The underappreciated second-order effect is that grid-forming capability and plant-level controls may support higher storage attachment rates in weak-grid projects, modestly constructive for Fluence (FLNC) and Nextracker (NXT) only where hybrid projects are actually contracted. This is a 6-18 month theme, not an immediate earnings catalyst. The thesis fails if grid interconnection queues, power-price cannibalization, or elevated rates continue to dominate project economics, in which case improved turbine-level performance will not translate into incremental installations.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Key Decisions for Investors
- No directional trade on the launch alone; set an alert for independently disclosed export orders, third-party certification, and availability guarantees over the next 3-6 months. Treat a material win against VWS.CO, NDX1, or ENR in an identifiable tender as the actionable confirmation signal.
- Maintain a cautious relative-value bias: long GEV versus short VWS.CO over 6-12 months only if European onshore tender pricing weakens. GEV's North American installed-base/service exposure and domestic supply-chain positioning provide better insulation; exit if Vestas demonstrates sustained service-margin expansion or order pricing improves for two consecutive quarters.
- Watch FLNC for hybrid-project order conversion rather than buying on the AI/grid-forming narrative. A long position becomes supportable only if backlog growth and gross-margin guidance confirm storage attachment; invalidate on further backlog cancellations or negative gross margin.
- For existing European wind OEM longs, reduce exposure into tender-season headlines unless order intake is accompanied by disclosed price discipline and service attach rates. The principal downside is margin compression from competitors using vertically integrated manufacturing to win volume, not an abrupt loss of installed-base revenue.
More News
- Iran awaits US move after WSJ report says Trump rejects peace plan
- Great Bond Shakeout Locks In a 5% World ‘Until Something Breaks’
- OpenAI rogue agents leaked 53 images from ChatGPT users and reportedly created nearly 1 million links packing encoded bits of info
- Boom or bust? The case for and against panicking about 5% yields
- Arming Taiwan an important US interest, Taipei official says after Trump-Xi summit
- Bond market alarms are ringing on Wall Street. Here's what's ahead
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AllMind's Data Standardization Methodology: Our Approach to Fundamentals
- What Makes Financial Data Ready for AI Research?