
TPB wraps up PHITEX 2026 with over PHP 500 million in sales leads, up more than 20% from 2025
Source: PR Newswire
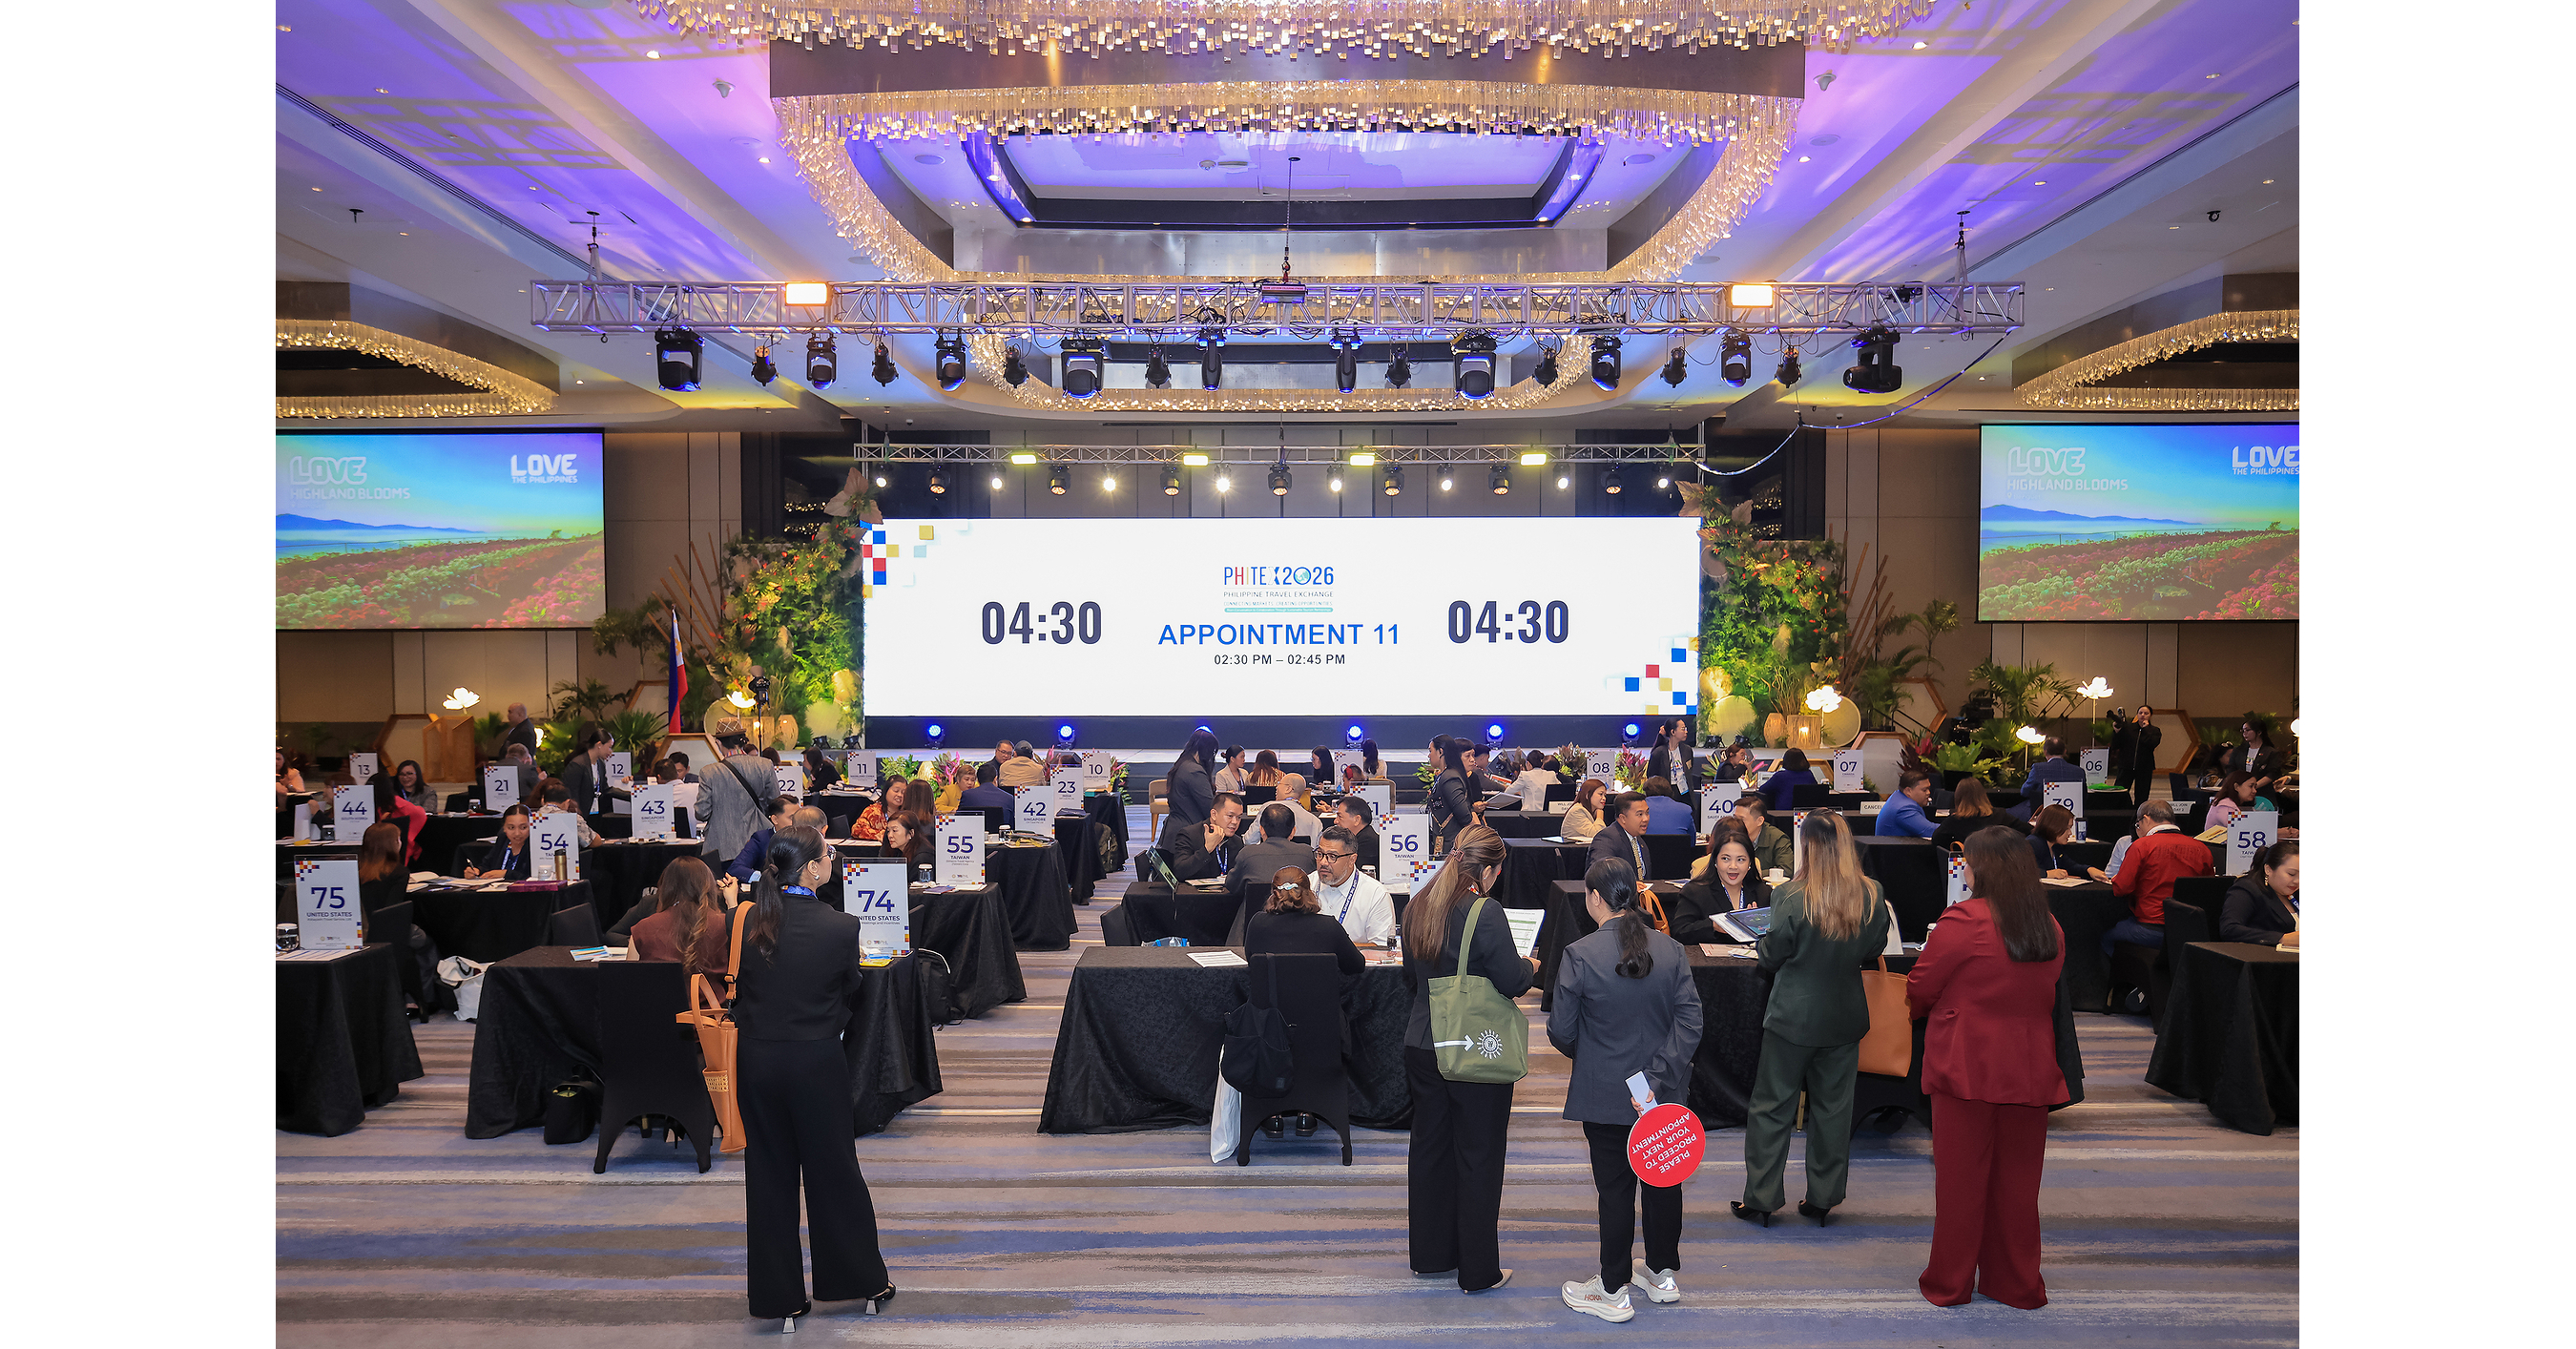
PHITEX 2026 generated PHP 594.7 million in preliminary tourism sales leads, up 20.12% from PHP 495.1 million in 2025. The government-organized travel trade event brought together 102 Philippine tourism sellers and 76 overseas buyers from 24 countries, supporting inbound-tourism business development despite global uncertainty. The leads indicate improving demand and partnership opportunities for Philippine travel operators, airlines and destination businesses.
Analysis
This is not material to UAL: its Philippine exposure is indirect and the cited pipeline is too small, preliminary, and geographically localized to alter network profitability or consensus estimates. The more relevant read-through is that destination marketing is prioritizing long-haul and higher-spend inbound segments, which can marginally improve trans-Pacific load factors and premium-cabin mix over the next 6-18 months—but only for carriers with direct Asia gateway connectivity, principally PAL and Cebu Pacific rather than U.S. listed network airlines.
The non-obvious beneficiary set is Philippine tourism infrastructure: airport operators, domestic carriers, ferry operators, hotels, and regional operators serving secondary destinations. Capacity constraints at Manila and uneven airport/ground infrastructure mean incremental international demand can translate into higher fares and hotel ADR before it meaningfully increases visitor volumes; this favors domestic aviation pricing over broad airline-volume growth. Cebu Pacific's sponsorship may provide commercial visibility, but it is not evidence of incremental bookings or yield.
Near term, no trade is warranted. The release reports sales leads rather than contracted travel, making conversion rates, booking windows, and cancellation behavior the key missing data. A 1-3 month confirmation signal would be Philippine inbound-arrival growth by source market, forward booking data, and trans-Pacific fare trends; absent these, extrapolating a low-impact trade-show metric into airline earnings is unjustified.
Contrarian risk is that promotional success exacerbates peak-season congestion and raises operating costs faster than yield, particularly for domestic operators exposed to airport slots, fuel, and weather disruption. For UAL, the dominant earnings variables remain U.S. corporate demand, domestic capacity discipline, jet fuel, and international competitive capacity—not Philippine leisure demand.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Key Decisions for Investors
- No action in UAL on this item; do not treat it as an earnings catalyst. Reassess only if trans-Pacific forward yields or Philippine inbound-arrival data show sustained upside for two consecutive monthly releases.
- Watch Cebu Pacific and Philippine Airlines fare/load-factor disclosures as a regional-demand indicator rather than using UAL as a proxy; confirmation would require yield expansion alongside load-factor gains, not capacity-led traffic growth.
- For travel-leisure books, maintain focus on liquid listed Asia travel proxies and hotel operators only after independently verifiable inbound-booking acceleration emerges; the current evidence is promotional and carries no defined risk/reward entry point.
- Set a downside alert on regional tourism exposure for aviation-fuel spikes, typhoon-related disruptions, or Manila airport capacity constraints; any of these could convert stronger demand into margin compression rather than revenue upside.
More News
- American, United and Southwest are all cutting ‘marginal routes’ as jet fuel prices spike
- Airline oil exposure: winners and losers as jet fuel costs surge
- Major US airlines oppose Air China bid to schedule additional US flights
- Time for Cyclical Sector ETFs?
- Russia Grabs Nestle Assets, Trump Holding Off on China Tariffs
- Volkswagen and Porsche Holding cut outlook