
Nexio Power Secures 77-Acre Anderson, Texas Campus for Commercial Truck Production
Source: PR Newswire
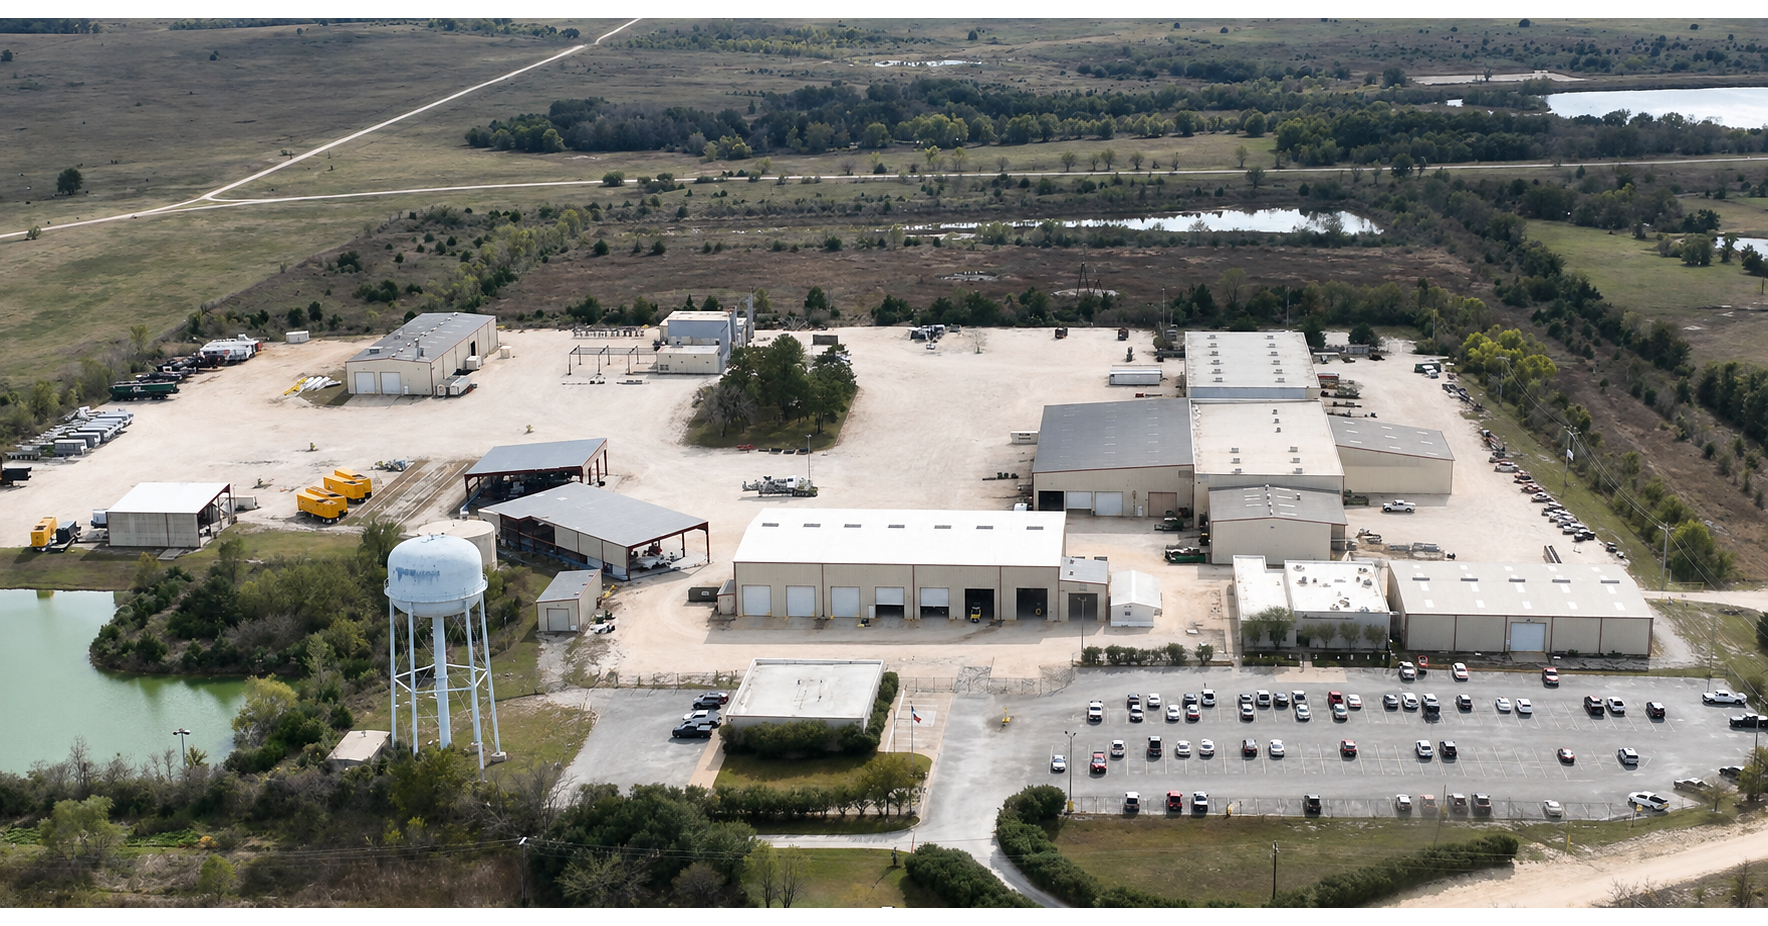
Nexio Power secured a 77-acre industrial campus in Anderson, Texas with about 180,000 sq ft of immediately available production and finishing/testing capacity to support near-term truck production, while Lufkin serves as a longer-range campus plan. The site is pre-equipped with heavy-duty infrastructure (including 13 overhead cranes up to 25 tons and paint/blast plus an 11-bay test complex with 300,000-gallon water storage), enabling faster ramp and added repair/refurbishment capability. While the news is operational rather than financial, the incremental capacity and execution runway modestly de-risks the company’s production scaling.
Analysis
This reads as an execution de-risking event, not a demand validation event. For a capital-intensive OEM, locking in a ready-made production footprint usually pulls forward fixed costs before utilization is proven, which means the market should care less about “capacity” and more about whether orders, deposits, and working capital are arriving fast enough to absorb overhead over the next 2-4 quarters.
The second-order implication is that the company is now more exposed to financing discipline than to construction risk. If volume ramps, the benefit accrues to the propane ecosystem and local industrial service providers; if it does not, the campus becomes stranded capacity and the equity story shifts from growth to dilution risk. That is why the real beneficiaries are not obvious public comp names, while the main losers would be any bullish narrative built purely on manufacturing readiness.
The contrarian read is that the market may overrate “factory news” as commercialization proof. For niche heavy-vehicle platforms, the usual failure mode is not technology, it is slow fleet adoption and low gross-margin visibility; absent third-party order evidence, this kind of announcement can actually increase skepticism because it raises the bar for utilization. The key falsifier is near-term disclosure of customer-backed backlog or repeat fleet conversions; otherwise, the 6-18 month risk is that the site becomes an expensive proof-of-concept rather than a scalable asset.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Ticker Sentiment
Key Decisions for Investors
- No new position in HUSA on this headline; treat the move as a watch item only until the company discloses customer backlog, deposits, or financing terms that prove utilization.
- If you want exposure to the broader commercial-vehicle buildout theme, favor established OEMs like OSK or PCAR on pullbacks rather than chasing speculative alternative-fuel names; this announcement does not change competitive share in the next 1-2 quarters.
- Set an alert for any third-party order wins or financing event over the next 30-90 days; if management can show repeatable demand and positive gross margin, only then revisit a small long in the name or its closest listed proxy.
- If HUSA rallies on sympathy with the article, consider fading strength rather than buying it; the risk/reward is poor unless there is independent evidence of revenue conversion.
More News
- One Singapore ship was sunk, but here's why others are still transiting the Strait of Hormuz
- Order to limit Starshield for Ukraine came from inside White House: Reuters reports
- The IPO drought is driving private equity-owned companies to the debt market to pay investors
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- BOE Chief Says Energy Shock Delays 2% Inflation Target
- FDA approves Enspryng for thyroid eye disease treatment