
CordenPharma Appoints Dr. Jean-Luc Herbeaux as Chief Executive Officer to Lead Next Phase of Growth
Source: PR Newswire
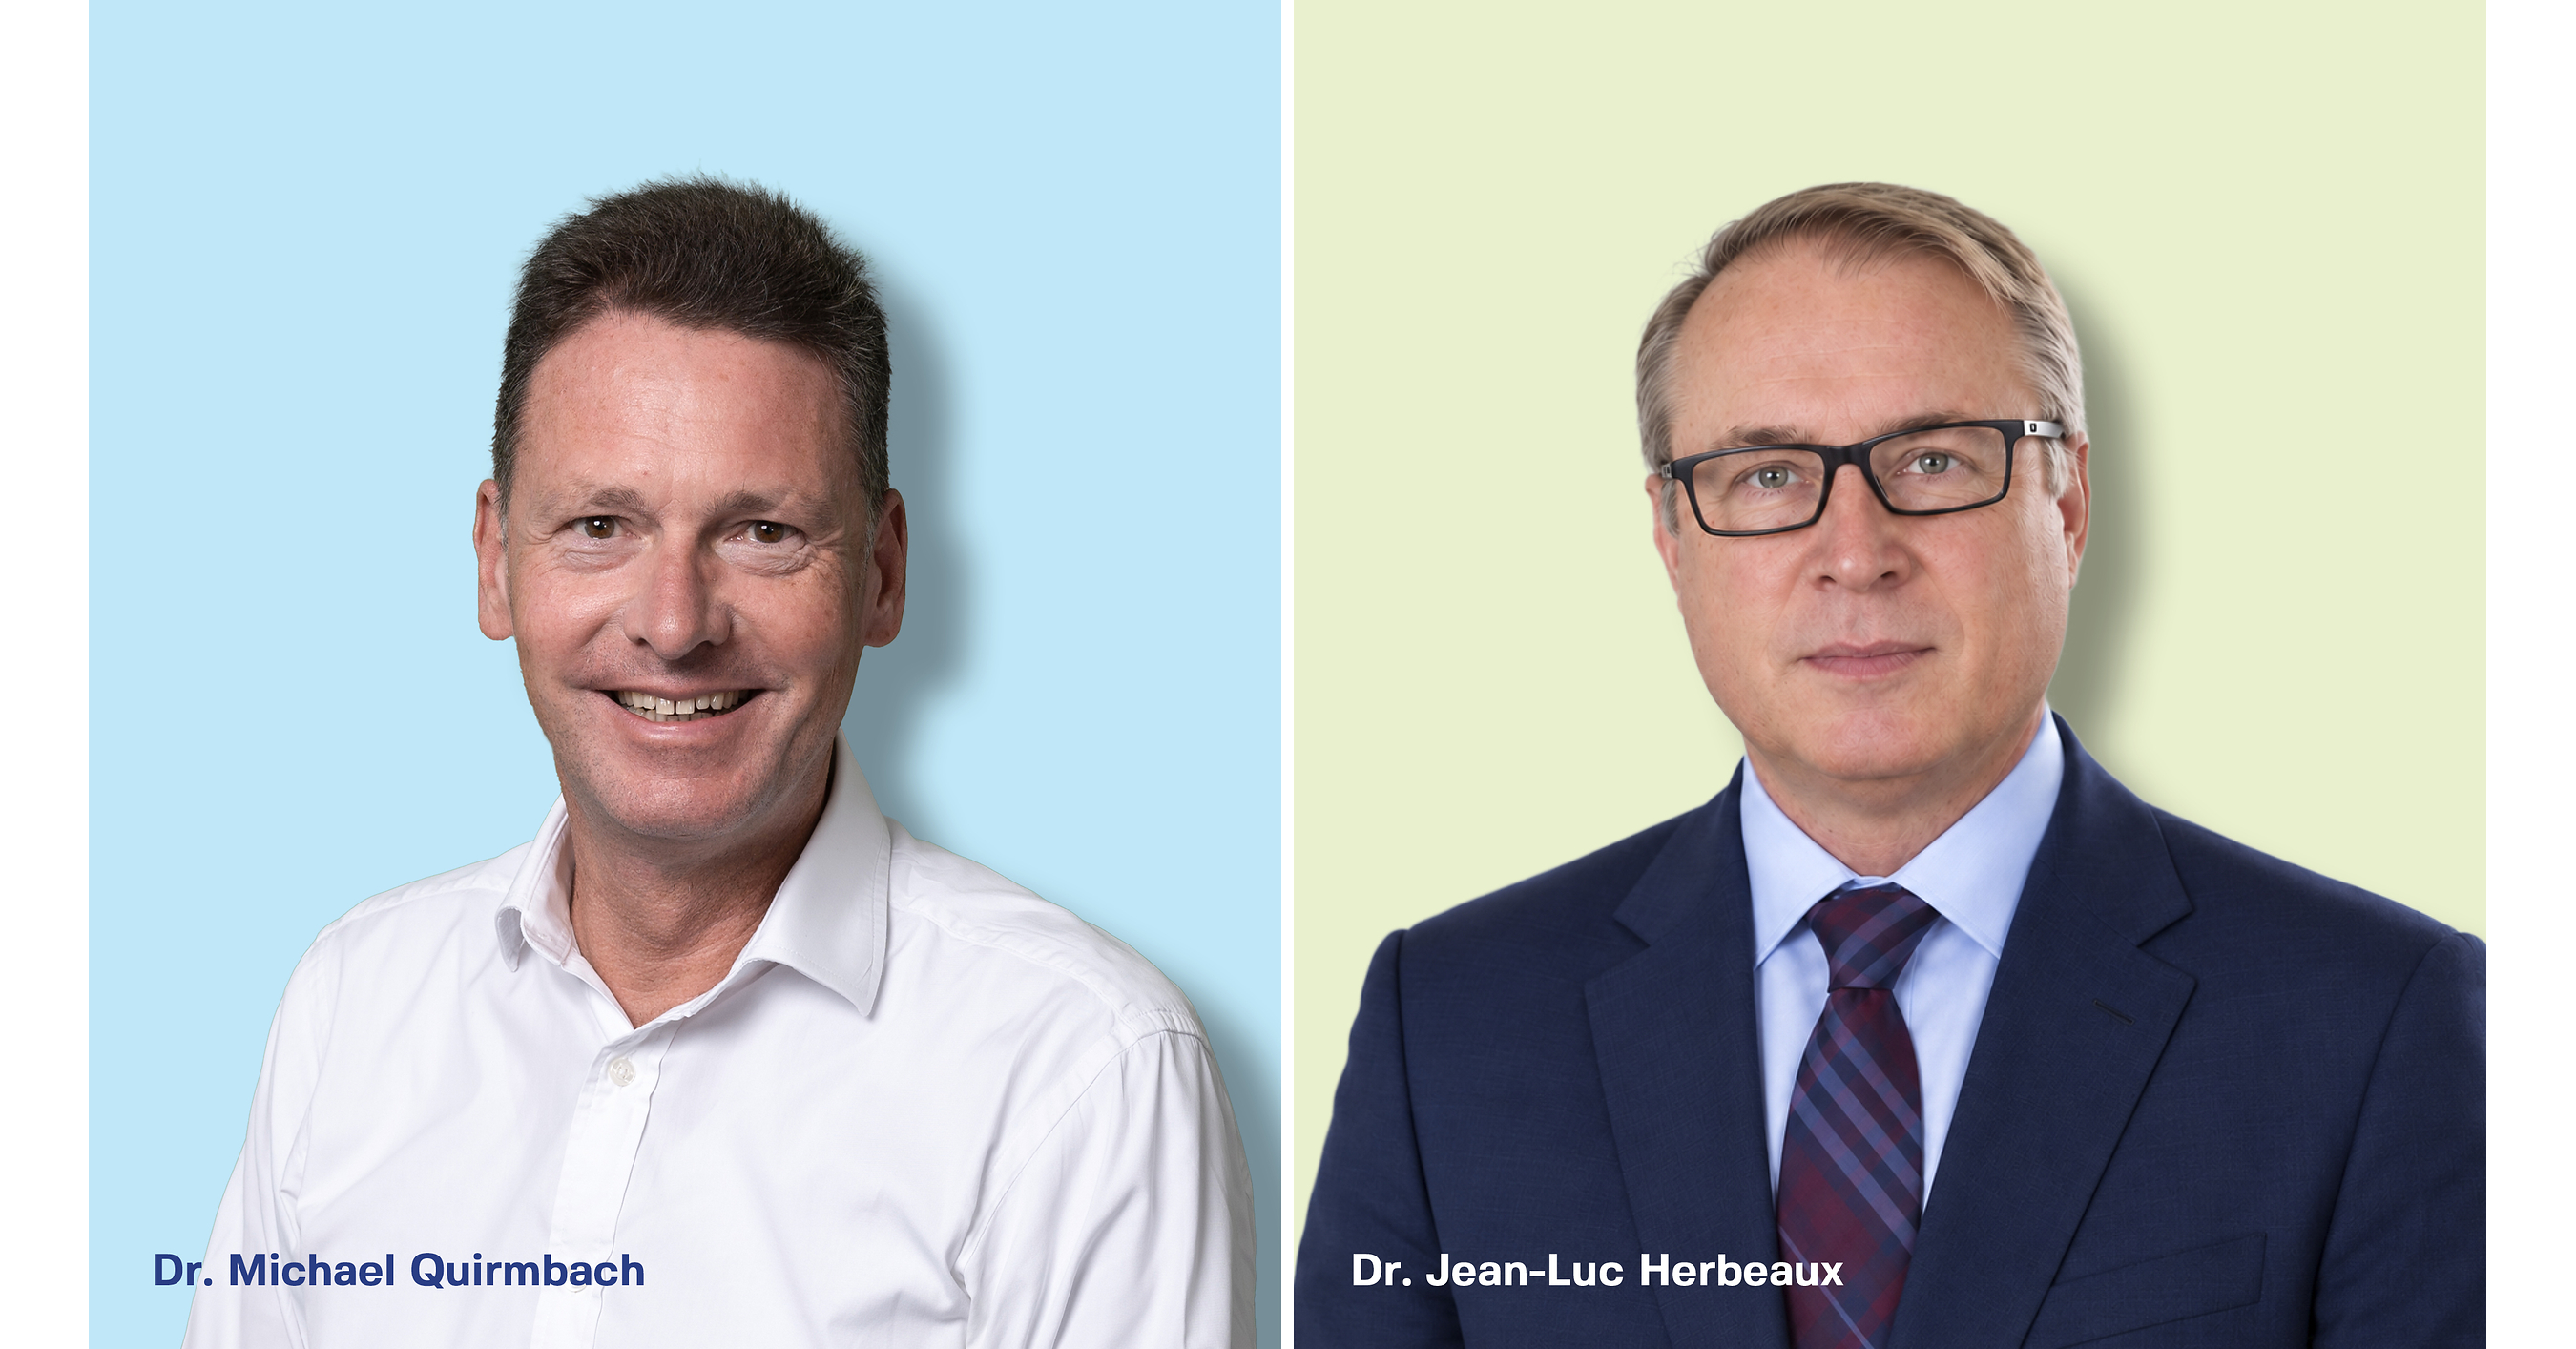
CordenPharma appointed Jean-Luc Herbeaux, formerly CEO of Hovione, as CEO effective 1 October 2026, while outgoing CEO Michael Quirmbach will remain a board member and senior advisor. The planned succession follows a major expansion phase in which annual revenue rose from €245 million to more than €1 billion over Quirmbach's 12-year tenure; 2025 sales were €960 million. Herbeaux will execute the next growth phase following the AmbioPharm peptide-CDMO acquisition and continued global manufacturing-capacity investment.
Analysis
This is not a fundamental catalyst for EVK: the executive departed Evonik well before this appointment, and CordenPharma is privately owned. The relevant read-through is competitive rather than direct—an operator with both CDMO and specialty-chemicals experience may accelerate Corden’s push into higher-value peptide, oligonucleotide and lipid-formulation capacity, where customer switching costs are high once a program reaches late-stage development. That could modestly tighten competitive bidding for publicly listed European outsourcing peers such as Lonza (LONN) and Siegfried (SFZN), but no near-term earnings estimate change is supportable from a personnel announcement.
The more consequential second-order issue is execution after a capacity-and-M&A buildout. A CEO with operating credentials may prioritize plant utilization, integration and commercial conversion over another acquisition, which would reduce the probability of an immediate PE-sponsored bolt-on cycle but increase pressure on competitors whose growth assumptions rely on sustained outsourced demand. Over 6-18 months, evidence of peptide/LNP order conversion or improved utilization would be more relevant to listed suppliers of specialty lipids and process inputs than EVK; absent disclosed capex, backlog, or customer wins, this remains a watch item rather than a tradable signal.
Consensus should resist treating the leadership change as proof of accelerating growth. PE-owned CDMOs can preserve an expansion narrative while carrying underutilized new capacity, and complex-modality demand is uneven across clinical cohorts. The thesis is falsified positively by disclosed commercial-scale awards, utilization gains, or a new capacity program; it is falsified negatively by price competition, delayed customer transfers, or another acquisition that raises integration and leverage risk.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No directional EVK position on this news; maintain neutral exposure because the appointment has no identifiable revenue, margin, or capital-allocation linkage to EVK. Reassess only if Evonik discloses a commercial relationship, capacity contract, or management commentary tying its pharma-services portfolio to Corden.
- Place a 1-3 month diligence alert on LONN and SFZN for pricing, utilization, and peptide/oligonucleotide backlog commentary. A disclosed Corden commercial win at scale would be a modest competitive negative for peers, but do not short absent evidence of lost orders or guidance pressure.
- For 6-18 month thematic exposure, favor LONN over smaller European CDMO peers only if its next results show resilient biologics/complex-modality order intake and stable margins despite capacity additions across the sector; exit or avoid if utilization or pricing guidance is cut.
More News
- Grab aims for 'next level' in financial services with purchase of buy-now pay-later platform Atome
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks
- Exclusive-Malaysia talks to rival airlines as it monitors AirAsia’s financial health, sources say
- Factbox-Private equity, foreign investors fuel Aussie M&A activity in 2026
- Is Amazon Stock a Buy After Its Best Quarter in Years?
- Australia’s Reliance Worldwide agrees to Brookfield’s $2.9 billion buyout bid