
K-Beauty Brand Hanhoo Expands National Retail Footprint
Source: PR Newswire
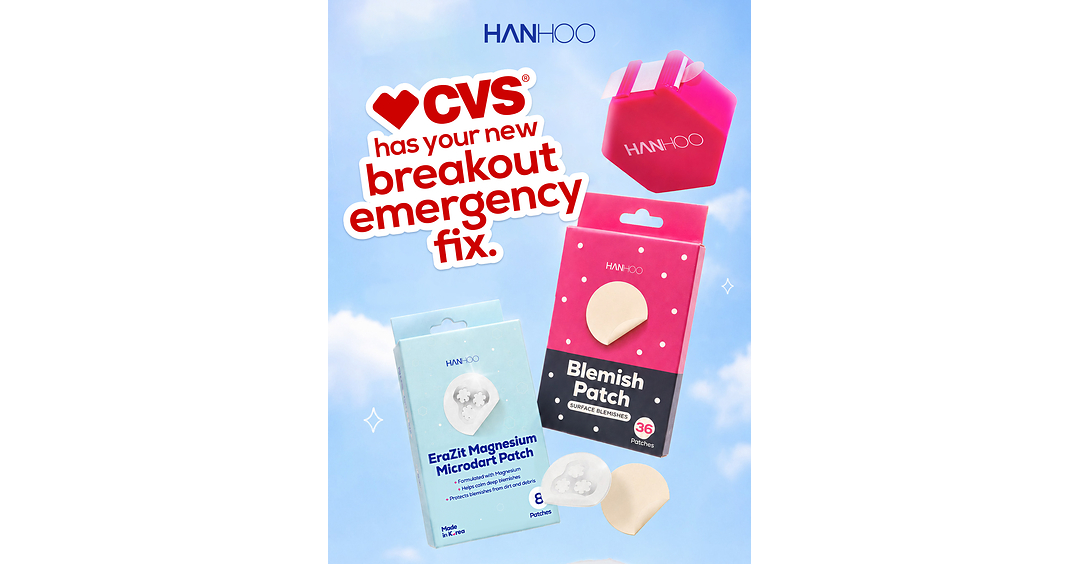
Hanhoo launched its Korean-inspired acne-patch collection in more than 600 CVS Pharmacy locations and on CVS.com, with products priced from $5.49 to $11.49. The expansion follows 34.5% year-over-year growth in the brand's U.S. retail footprint and includes its portable On The Go Blemish Patch dispenser. The distribution win broadens consumer access but is unlikely to have material public-market impact.
Analysis
This is immaterial to CVS Health's consolidated earnings, but it is directionally supportive of front-store category productivity: low-ticket, high-repeat acne accessories can improve basket attachment and gross-profit dollars per shelf foot if they pull consumers into the beauty aisle rather than merely displace existing patch brands. The key issue is substitution. CVS likely benefits only if the assortment expands the acne-patch category or raises conversion among younger shoppers; otherwise, the economics are mostly a reallocation away from incumbents such as Hero Cosmetics/Mighty Patch, Peace Out, and private-label offerings.
The near-term market implication is effectively zero for CVS (CVS); a limited-door skincare launch cannot alter the pharmacy-benefit, insurance, or cost-restructure earnings drivers that set its multiple. Over 1-3 months, the relevant read-through is whether CVS continues adding low-price K-beauty brands across consumables, which could modestly improve front-store traffic but also signal greater promotional intensity and margin pressure for legacy mass skincare suppliers. The 6-18 month structural risk for branded acne incumbents is that hydrocolloid patches are increasingly commoditized: differentiated packaging may support velocity, but low barriers to sourcing and private-label replication limit durable pricing power.
Contrarian view: the headline's retail-footprint metric is not evidence of consumer sell-through, and the quoted growth rate should not be treated as a demand indicator without comparable-door productivity, replenishment data, or evidence of expanded shelf allocation. A successful launch would matter more as a signal that CVS can win younger beauty shoppers from ULTA and Target than as a standalone revenue event; failure would likely be absorbed through normal assortment resets with no financial consequence to CVS.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- No standalone position in CVS on this development. Maintain existing CVS underwriting on medical-cost trends, Aetna utilization, PBM policy risk, and restructuring execution; do not revise EPS or valuation assumptions absent evidence that front-store same-store sales or gross margin is improving.
- Set a 1-3 month channel-check alert for CVS.com ranking, promotional cadence, out-of-stock rates, and incremental shelf facings versus Mighty Patch and private-label acne patches. Treat sustained top-category placement and repeat replenishment as a modest positive signal for CVS front-store traffic, not a material earnings catalyst.
- For consumer-beauty portfolios, monitor privately held Hero Cosmetics and public mass-beauty proxies including ELF and ULTA for increasing acne-patch discounting or shelf-loss commentary. Avoid a directional short based solely on this launch; the thesis requires independently verified price compression or retailer-reset data.
- Falsify any positive CVS category thesis if upcoming front-store comparable sales remain weak, beauty gross margin contracts, or management attributes traffic softness to discretionary health-and-beauty consumption. Those indicators would show that new assortment is cannibalistic rather than incremental.
More News
- In photos: China's Xi hardens Taiwan warning as country celebrates week-long National Day holiday
- Google rolls out Gemini 4 Argon, its most advanced AI model
- Goldman pushes Fed rate hike to December after cooler inflation
- NIO reports 37,408 vehicle deliveries in September, up 7.7% YoY
- Meta stock enjoys best month since 2022 on AI momentum
- Huawei unveils Mate 90 phones, leans on homegrown chip design to offset US curbs