
TGM EXPANDS INSTITUTIONAL CAPITAL FORMATION CAPABILITIES WITH APPOINTMENT OF INDUSTRY VETERAN TIM ANDERSON
Source: PR Newswire
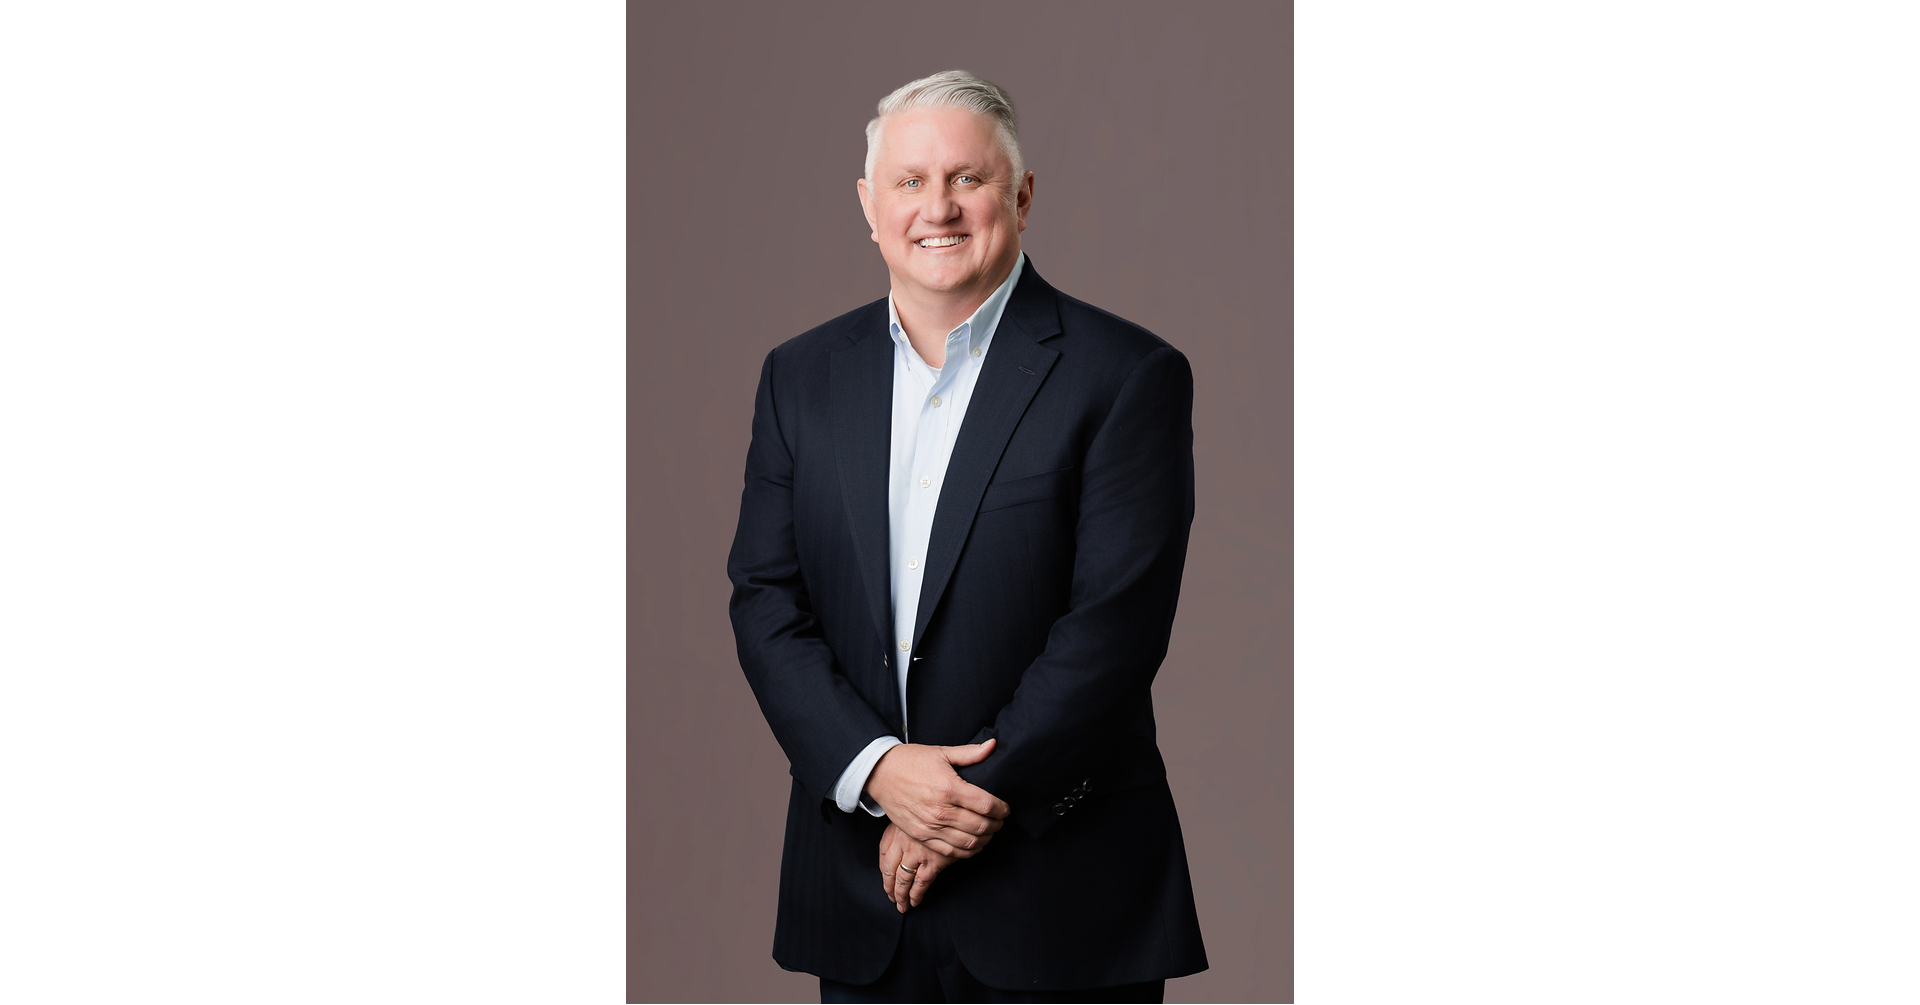
TGM appointed Tim Anderson as Managing Director to lead institutional business development and capital formation, aiming to expand its institutional investor base. Anderson brings more than 25 years of alternatives fundraising experience across hedge funds, private credit and real estate. Founded in 1991, TGM had invested in 141 multifamily properties and one land acquisition across 28 states as of August 31, 2026.
Analysis
This is not a public-markets catalyst: TGM is private, and a senior fundraising hire has no independently verifiable near-term effect on assets under management, fee revenue, transaction capacity, or property-level cash flow. The relevant signal is that the firm may be positioning to raise capital into a dislocated multifamily acquisition market, where refinancing pressure and constrained bank lending can create forced-sale inventory. That opportunity matters only if TGM can demonstrate commitments and deploy capital at materially discounted replacement cost.
MCS has no actionable fundamental linkage to this development. The reference to the Marcus Family Office should not be conflated with The Marcus Corporation; absent a disclosed commercial relationship, the appropriate expected price impact is zero. Avoid any event-driven positioning in MCS based on this release.
For public REITs, the second-order implication is modestly competitive: additional institutional dry powder could eventually support multifamily transaction clearing prices, benefiting apartment asset values but reducing acquisition cap-rate upside for buyers such as MAA, CPT and ESS. Over the next 1-3 months, financing conditions, transaction volumes, and distressed-sale discounts—not personnel announcements—will determine whether private capital is actually returning. A sustained decline in Treasury yields or narrowing private-real-estate credit spreads would accelerate capital formation and reduce the probability of deep asset-price distress over 6-18 months.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No trade in MCS: treat this as unrelated private-manager personnel news; reassess only upon a disclosed partnership, asset-management mandate, or capital relationship involving MCS.
- Set a watch alert on multifamily transaction data and private-fund closes over the next 1-3 months. Consider selective long exposure to MAA or CPT only if apartment transaction cap rates stabilize while same-store NOI guidance remains intact; this would signal that asset-value downside is being contained.
- For a distressed-real-estate thesis, wait for evidence of actual TGM fundraising and acquisitions rather than extrapolating from the hire. Falsification of a constructive multifamily view: renewed long-end rate backup, widening commercial-real-estate credit spreads, or downward revisions to 2027 apartment NOI guidance.
More News
- ‘There’s nothing temporary about a temporary store’: How Spirit Halloween’s CEO took it from 130 stores to 1,550—and swallowed your mall’s Hot Topic
- Thousands of Israelis rally against Netanyahu gov’t days before election
- Jamie Dimon poached Warren Buffett’s protégé to run a $10 billion fund—he says Buffett’s response was ‘at least he’s going to you’
- Election posters, mass tourism and property: Israel’s footprint in Cyprus
- Serbia votes in election pitting longtime leader against student movement
- HSBC sees cautious optimism in VC and PE activity
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- 2026 Global Markets Outlook: Asset Allocation After the Great Disconnect
- Fintool Alternatives After the Microsoft Acquisition