
Chinese Carmakers Grow Market Share in Europe With Hybrid Surge
Source: Bloomberg
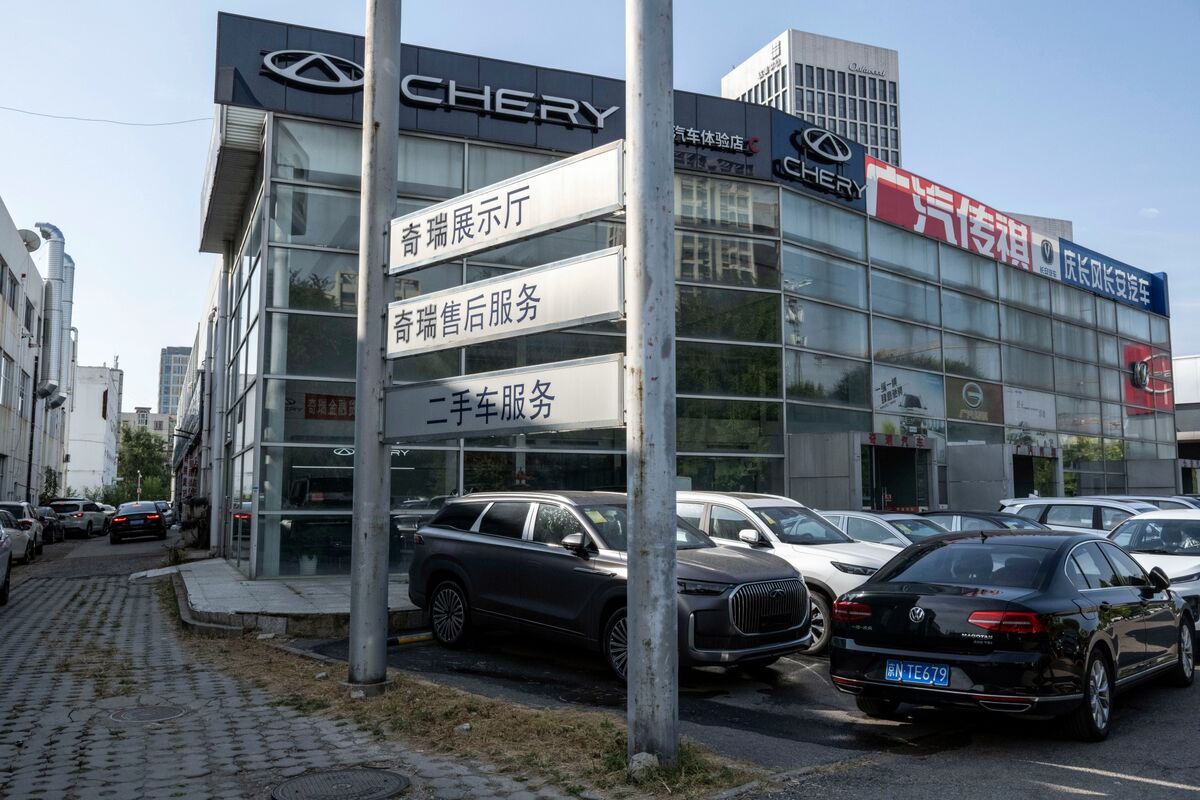
Chinese automakers’ share of Europe’s new-car sales rose above 11% last month, driven by a plug-in hybrid surge. Dataforce reported that a record one-third of plug-in hybrids registered in July were from Chinese brands such as Chery’s Jaecoo. The trend is modestly supportive for European market share shifts but is framed as demand-side data rather than a company-specific earnings catalyst.
Analysis
The key implication is not just share loss, but where the share is coming from: affordable plug-in hybrids attack the most economically fragile slice of European auto demand, where buyers are far more payment-sensitive than powertrain-pure. That puts the most pressure on mass-market incumbents with weak product differentiation and higher fixed-cost leverage — especially when they must defend volumes with incentives, which compresses residual values and dealer margins before it shows up in headline unit data.
The second-order effect is that hybrid adoption is a tactical bridge that lets Chinese OEMs build brand and dealer presence in Europe without waiting for charging infrastructure or full-BEV acceptance. Once a customer is captured on a PHEV, the conversion path to a second purchase can be a structural foothold; that is more dangerous than a single-cycle volume spike. It also raises the bar for European suppliers tied to local OEM platforms, because every lost unit in the entry segment dilutes factory utilization and weakens procurement leverage.
Near term, the market may be underestimating how quickly this turns into earnings revisions: order books and mix should deteriorate first, then pricing, then guidance over the next 1-2 quarters. The contrarian risk is policy — EU trade actions or localization requirements could slow Chinese penetration, but that is a months-to-years process and may simply shift assembly rather than reverse competitive pressure. I would watch for any evidence that European OEMs are protecting share without materially increasing incentives; absent that, the trend looks more durable than a one-month data point.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.05
Key Decisions for Investors
- Short the European mass-market auto basket over the next 1-3 months: VWAGY / STLA / RNO.PA. Best risk/reward is if Q3 guidance highlights incentive pressure and mix deterioration; falsifier is stable EU pricing or a sharp tariff-driven slowdown in Chinese registrations.
- Pair trade: long BMWYY or MBGYY vs short STLA. Premium brands should be relatively insulated from sub-$40k price competition, while Stellantis has more direct overlap with the value/hybrid segment; target is relative outperformance over the next earnings cycle.
- Use put spreads on VWAGY into the next European auto print if implied vol is still below realized incentive volatility. The thesis needs 1-2 quarters to work; cap risk if EU market share stabilizes above current levels.
- Watch-list for CATL and BYD supply-chain beneficiaries only if European localization evidence emerges (new assembly, battery JV, or dealer expansion). Without that, the better expression remains short legacy OEMs rather than long Chinese ADRs.
More News
- ‘If nothing is done, it’s almost inevitable’: Ukraine’s Yuriy Ryzhenkov on why steelmaking is on the brink of collapse as Russian bombing intensifies
- Why is LG Innotek stock plunging today?
- Why is SK Hynix stock sliding today?
- TikTok CEO sees major scientific breakthroughs from AI within three years
- What the Iran war has done to the world’s energy supply, in charts
- TSMC expected to report sixth straight quarter of record profit thanks to AI boom