
UPSHER-SMITH LAUNCHES FLUVOXAMINE MALEATE EXTENDED-RELEASE CAPSULES
Source: PR Newswire
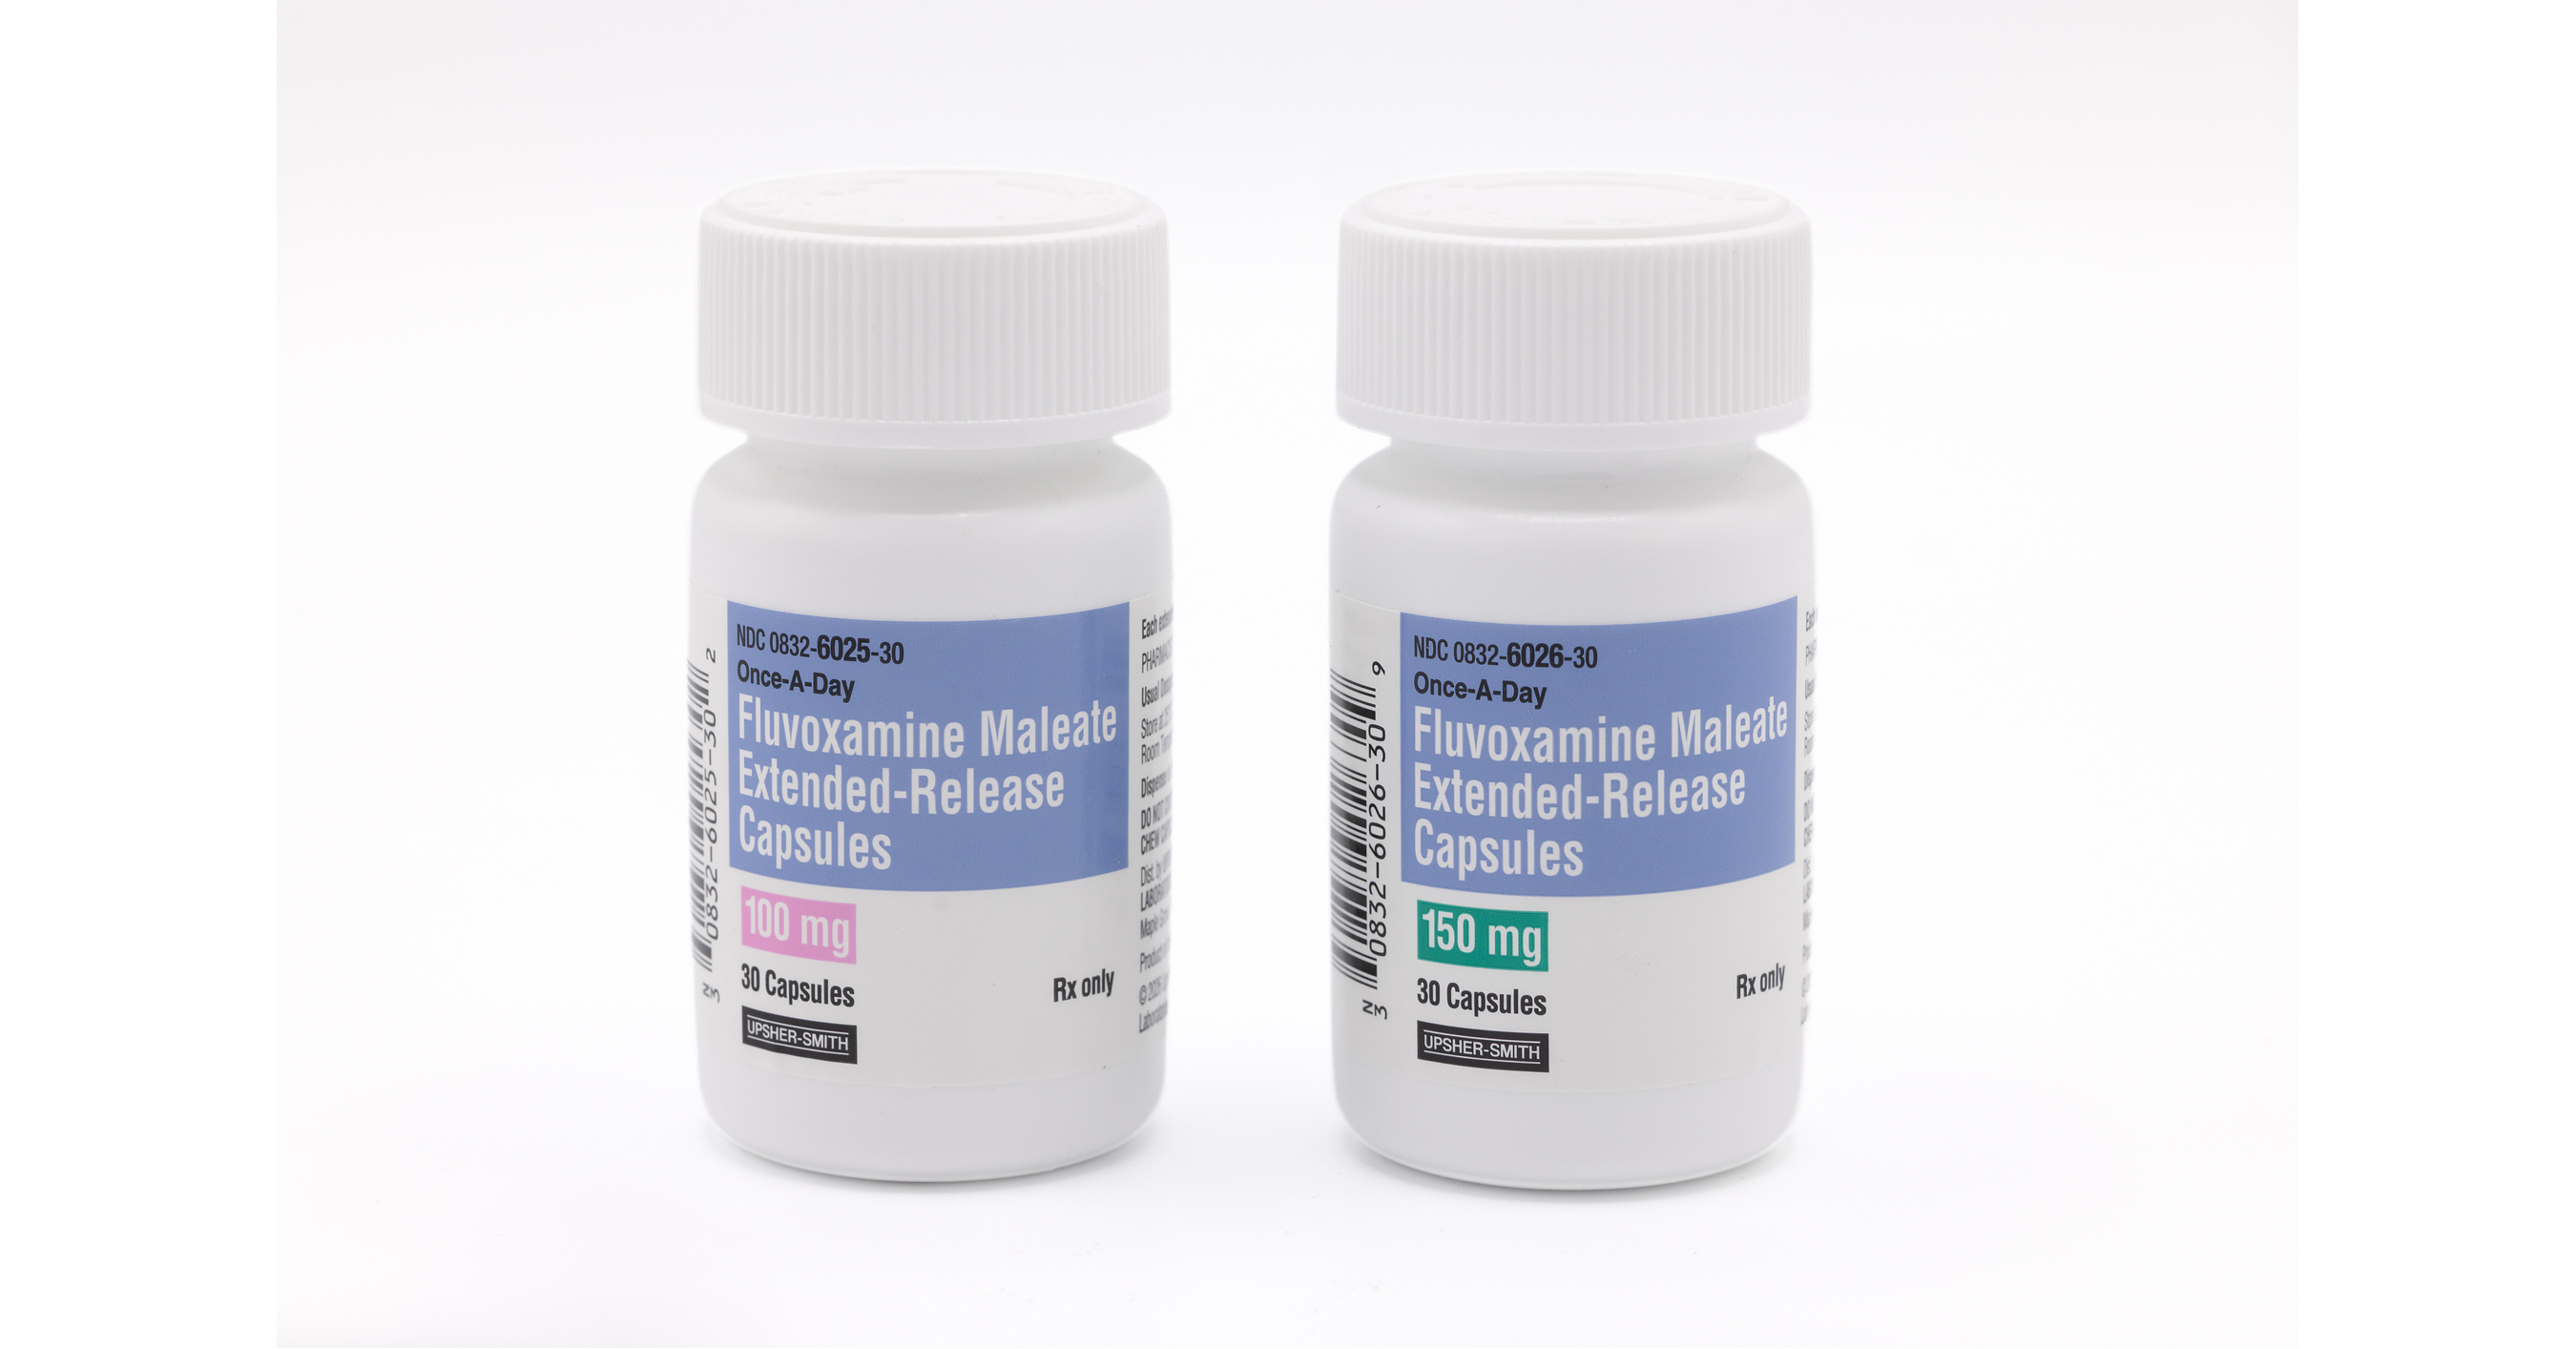
Upsher-Smith, a Bora Pharmaceuticals subsidiary, launched AB-rated generic Fluvoxamine Maleate Extended-Release Capsules in 100 mg and 150 mg strengths, referencing Luvox CR. The addressed U.S. market generated approximately $44.6 million in sales during August 2025 through July 2026, providing a modest new commercial opportunity for the company.
Analysis
This is economically immaterial for IQV: its role is measurement/data infrastructure, not product economics, and there is no evidence that the launch changes IQV’s contract volumes, pricing, or earnings trajectory. The relevant public-market exposure is Bora Pharmaceuticals (6472.TW; BORAY OTC), but the addressable revenue pool is too small to alter consolidated valuation absent evidence that this is part of a repeatable U.S. specialty-generic launch cadence.
The launch modestly raises price-erosion risk for the incumbent supply chain around the branded-reference product and any existing generic suppliers, but the market is likely already concentrated in low-value prescriptions where additional entrants rapidly compress net price. AB substitutability supports pharmacy uptake, yet actual revenue capture depends on wholesaler formulary access, channel inventory loading, and manufacturing reliability—none of which are independently established in the announcement. Initial shipment revenue can precede sustainable demand by one to two quarters.
The non-obvious read-through is strategic rather than financial: successful U.S. launches can improve Bora’s utilization of commercial infrastructure and create cross-selling demand for its CDMO capacity, but only if launches are numerous enough to absorb fixed selling, quality, and distribution costs. Watch quarterly disclosures for U.S. commercial revenue growth, gross-margin progression, and a disclosed pipeline of filed/approved products; without those, the event is not tradeable. A 1–3 month catalyst would be formulary wins or additional launches, while any structural rerating requires proof of recurring, higher-margin commercial contribution over 6–18 months.
Contrarian view: investors may over-credit generic launches for growth while underestimating the speed of post-launch price deflation. A meaningful thesis would be falsified if Bora reports U.S. commercial expansion without margin improvement, signaling that incremental products are merely replacing declining legacy economics rather than generating operating leverage.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No action in IQV: maintain exposure based on clinical-trial volume, RFP activity, and biotech funding—not this launch. Treat any IQV price response as unrelated noise.
- Place BORAY/6472.TW on a watchlist rather than initiating: require evidence in the next two reporting periods of sustained U.S. commercial growth and gross-margin expansion before underwriting operating leverage.
- For a potential long BORAY, wait for confirmation of multiple U.S. launches or disclosed formulary/wholesaler traction; size only after liquidity assessment in the OTC line. Thesis risk is generic price erosion driving commercial revenue growth without EBITDA conversion.
- Monitor incumbent generic antidepressant suppliers only if prescription-data checks show unusually high share capture or price movement; a single small-market entrant does not justify a short without verified channel data.
More News
- Google rolls out Gemini 4 Argon, its most advanced AI model
- Huawei unveils Mate 90 phones, leans on homegrown chip design to offset US curbs
- Meta stock enjoys best month since 2022 on AI momentum
- Bloomberg Tech: OpenAI Seeks $30B as Trump Backs Safety Audits
- OpenAI’s $30B Bet, Trump’s AI Safety Shift and Apple’s Next Act
- Walgreens owner nears $9 billion deal to sell Boots chain- WSJ