
Bitmine Immersion Technologies (BMNR) gibt bekannt, dass der ETH-Bestand 6,05 Millionen Token erreicht hat und sich der Gesamtbestand an Kryptowährungen sowie Barmitteln und marktfähigen Wertpapieren auf 15 Milliarden US-Dollar beläuft
Source: PR Newswire
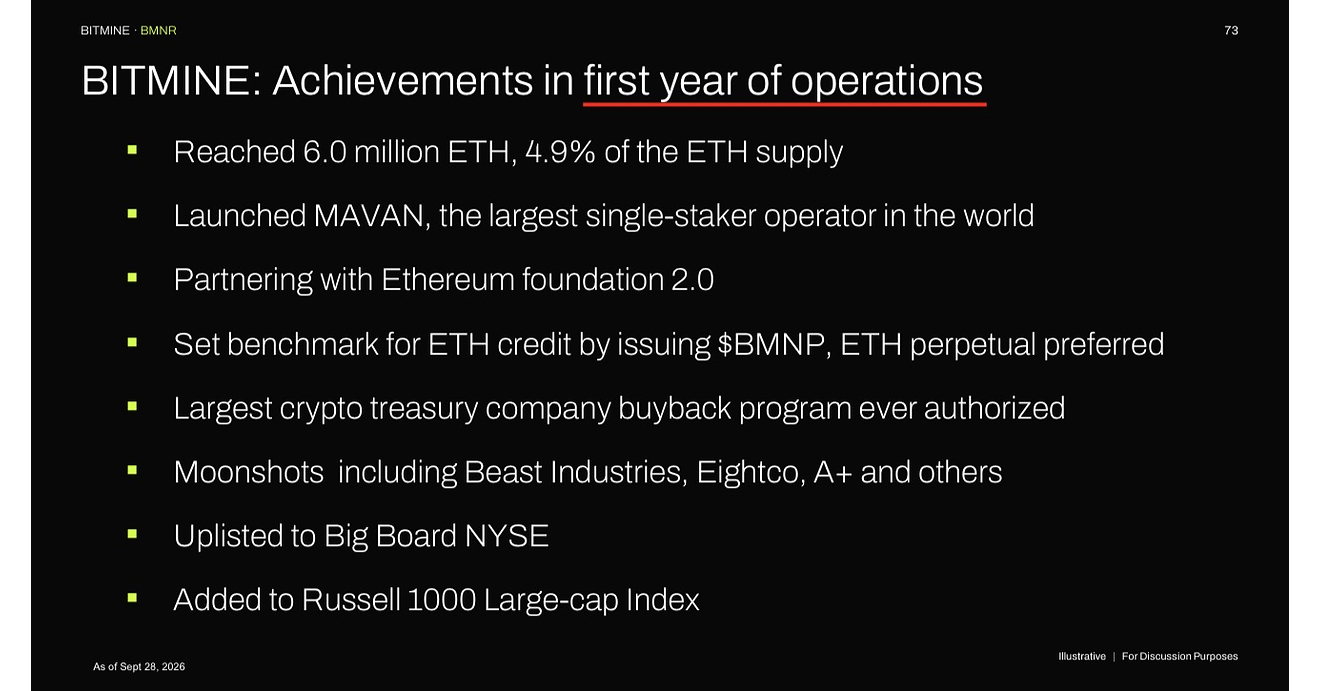
Bitmine reported $15 billion in combined crypto holdings, cash, marketable securities and “moonshots” as of October 25, 2026, including 6,051,933 ETH valued at $2,356 each—4.95% of total ETH supply. It bought back 2.04 million shares last week at an average $22.48 and has repurchased 22.9 million shares in 2026 for $399.6 million; it also reported 5,227,037 ETH staked, with annualized staking revenue estimated at $318 million on current holdings. Management characterized the crypto market as bullish and projected $368 million in annual staking rewards if all its ETH were staked; those outlooks are forward-looking statements.
Analysis
BMNR is best viewed as a leveraged, actively managed ETH vehicle—not simply an operating company with a buyback catalyst. Its equity can diverge sharply from ETH as the market reprices the premium or discount to look-through asset value, expected dilution, and confidence in custody and staking. A repurchase creates per-share value only if shares are bought below defensible NAV per share and funded without costly issuance or impaired liquidity; management’s valuation judgment is not independent evidence of that discount. The central near-term question is therefore the share price versus fully adjusted NAV, including the preferred securities, liabilities, and the liquidity and realizability of non-ETH holdings—details to verify before trading.
Over 1–3 months, ETH direction and equity/NAV spread matter more than the buyback headline. A falling ETH price can overwhelm staking income, while a widening BMNR discount could amplify downside even if ETH stabilizes. Over 6–18 months, third-party MAVAN adoption could diversify economics, but the release provides no independently verifiable customer traction or net margin data. Staking introduces operational, slashing, custody, and liquidity risks; concentrated treasury exposure also makes BMNR vulnerable to ETH drawdowns and regulatory changes. The bullish-cycle argument is management’s view, not confirmation of a market regime. GLXY may face greater competition if institutional staking infrastructure scales, but the article provides no evidence of lost business. No directional trade is justified without BMNR’s current NAV spread and capital structure.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- Treat BMNR as a watch, not a buy on this release. Before taking exposure, calculate current look-through NAV per diluted share, incorporating BMNP, other claims, cash, and any unvested or contingent shares; compare it with the stock price.
- Conditional relative-value idea: consider long ETH exposure rather than BMNR if the objective is ETH beta and BMNR trades at a premium to verified NAV. Reassess if BMNR’s discount becomes material and repurchases demonstrably reduce diluted shares below NAV; ETH drawdowns remain the principal risk.
- Monitor the next filing for repurchase authorization remaining, funding source, diluted share count, and any equity or preferred issuance. A rising share count or buybacks at a premium to NAV would falsify the per-share-accretion thesis.
- Track staking yield net of operating costs, validator incidents, withdrawal liquidity, and third-party MAVAN customers. Without independently reported customer assets and net economics, assign no material valuation uplift to the platform; slashing, outages, or falling ETH rewards would weaken the longer-term case.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- GE Vernova shares slip despite a beat-and-raise. What the sellers are getting wrong
- Microsoft's Big Bets on AI Start to Pay Off
- China’s tech darlings are losing their shine. Here’s what’s behind the sell-off