
Datamaran nombra a Bert Sinnema como director de tecnología
Source: PR Newswire
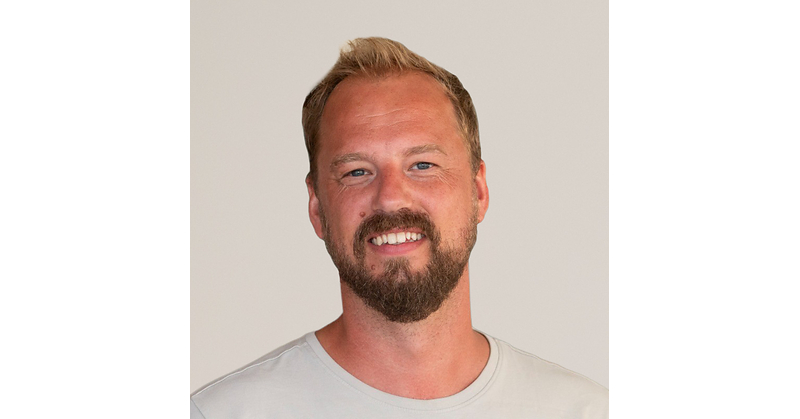
Datamaran nombró a Bert Sinnema como director de tecnología para liderar la visión de producto y la hoja de ruta tecnológica y acelerar el desarrollo de la plataforma impulsada por IA. El anuncio destaca que la empresa está profundizando el uso de IA para ofrecer información más rápida para decisiones sobre riesgo, regulación y expectativas de las partes interesadas. El impacto en mercado se percibe limitado por tratarse principalmente de un nombramiento, con sesgo positivo por la experiencia previa de Sinnema en ciberseguridad e ingeniería.
Analysis
This reads more like a capability signal than a monetization event: a better CTO can improve roadmap execution, but it does not by itself prove faster bookings or lower churn. The first-order market implication is that AI-native governance software is moving from “nice-to-have” to workflow infrastructure, which tends to favor the cloud/model layer more than the application vendor. For MSFT, any incremental Azure inference or security-stack pull-through is real but economically immaterial at current scale; the investment case should not move on this headline alone.
The second-order winners are horizontal platforms that can bundle compliance, identity, and data-governance workflows into existing enterprise contracts. That creates pressure on small point-solution vendors and manual advisory spend: as product velocity rises, customers will try to replace services with software, which compresses margin pools at the low end of the ecosystem. The risk is less “Datamaran wins” than “budget shifts away from niche ESG/compliance services toward bundled enterprise suites like MSFT, NOW, or security platforms such as PANW and CRWD.”
Contrarian view: the market often overreads leadership hires as evidence of product inflection. The real check is 1-2 reporting cycles of proof on deployment speed, renewal quality, and AI feature attach; without that, this is a hiring event, not a rerating catalyst. Falsifier: if upcoming customer commentary shows no improvement in implementation cadence or expansion, any AI-premium narrative in adjacent software names should fade quickly.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No direct MSFT trade on this headline; treat it as non-actionable noise unless Azure/security commentary later shows measurable cross-sell from AI governance workloads over the next 1-3 months.
- Set a watch on MSFT for any mention of Purview, Security, or Azure AI consumption tied to governance/compliance use cases; only revisit a long on a 3-5% pullback if cloud growth and capital intensity remain intact.
- Monitor PANW, CRWD, and NOW into the next earnings cycle for spillover demand in AI policy, data classification, and workflow governance; if management commentary confirms budget migration, consider a relative long versus software beta rather than a standalone directional trade.
- Do not short the private-company narrative outright: the better contrarian position is patience. Reassess only if Datamaran’s next two quarters fail to show faster deployments or stronger expansion, which would invalidate any ecosystem-wide AI governance re-rating.
More News
- Jim Cramer: Why I am taking the other side of the trade that crushed the market Friday
- Microsoft reportedly quits Nscale’s UK data centre weeks before its IPO
- Data Centers Have a New PR Plan: Your Kid’s Field Trip
- The Bond Market Is Sending a Warning to Nvidia Shareholders
- These 3 Green Stocks Have a Growth Story That Goes Far Beyond Washington
- Max Wasserman Stays Long-Term Bullish on AI; Likes GOOGL, MSFT, AVGO
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Palantir (PLTR) Q4 2025 Earnings: 70% Revenue Growth, Then an 11% Single-Day Crash
- AlphaSense Pricing: What Public Contract Data Shows in 2026