
Intuitive announces expanded indication for da Vinci SP in Europe
Source: PR Newswire
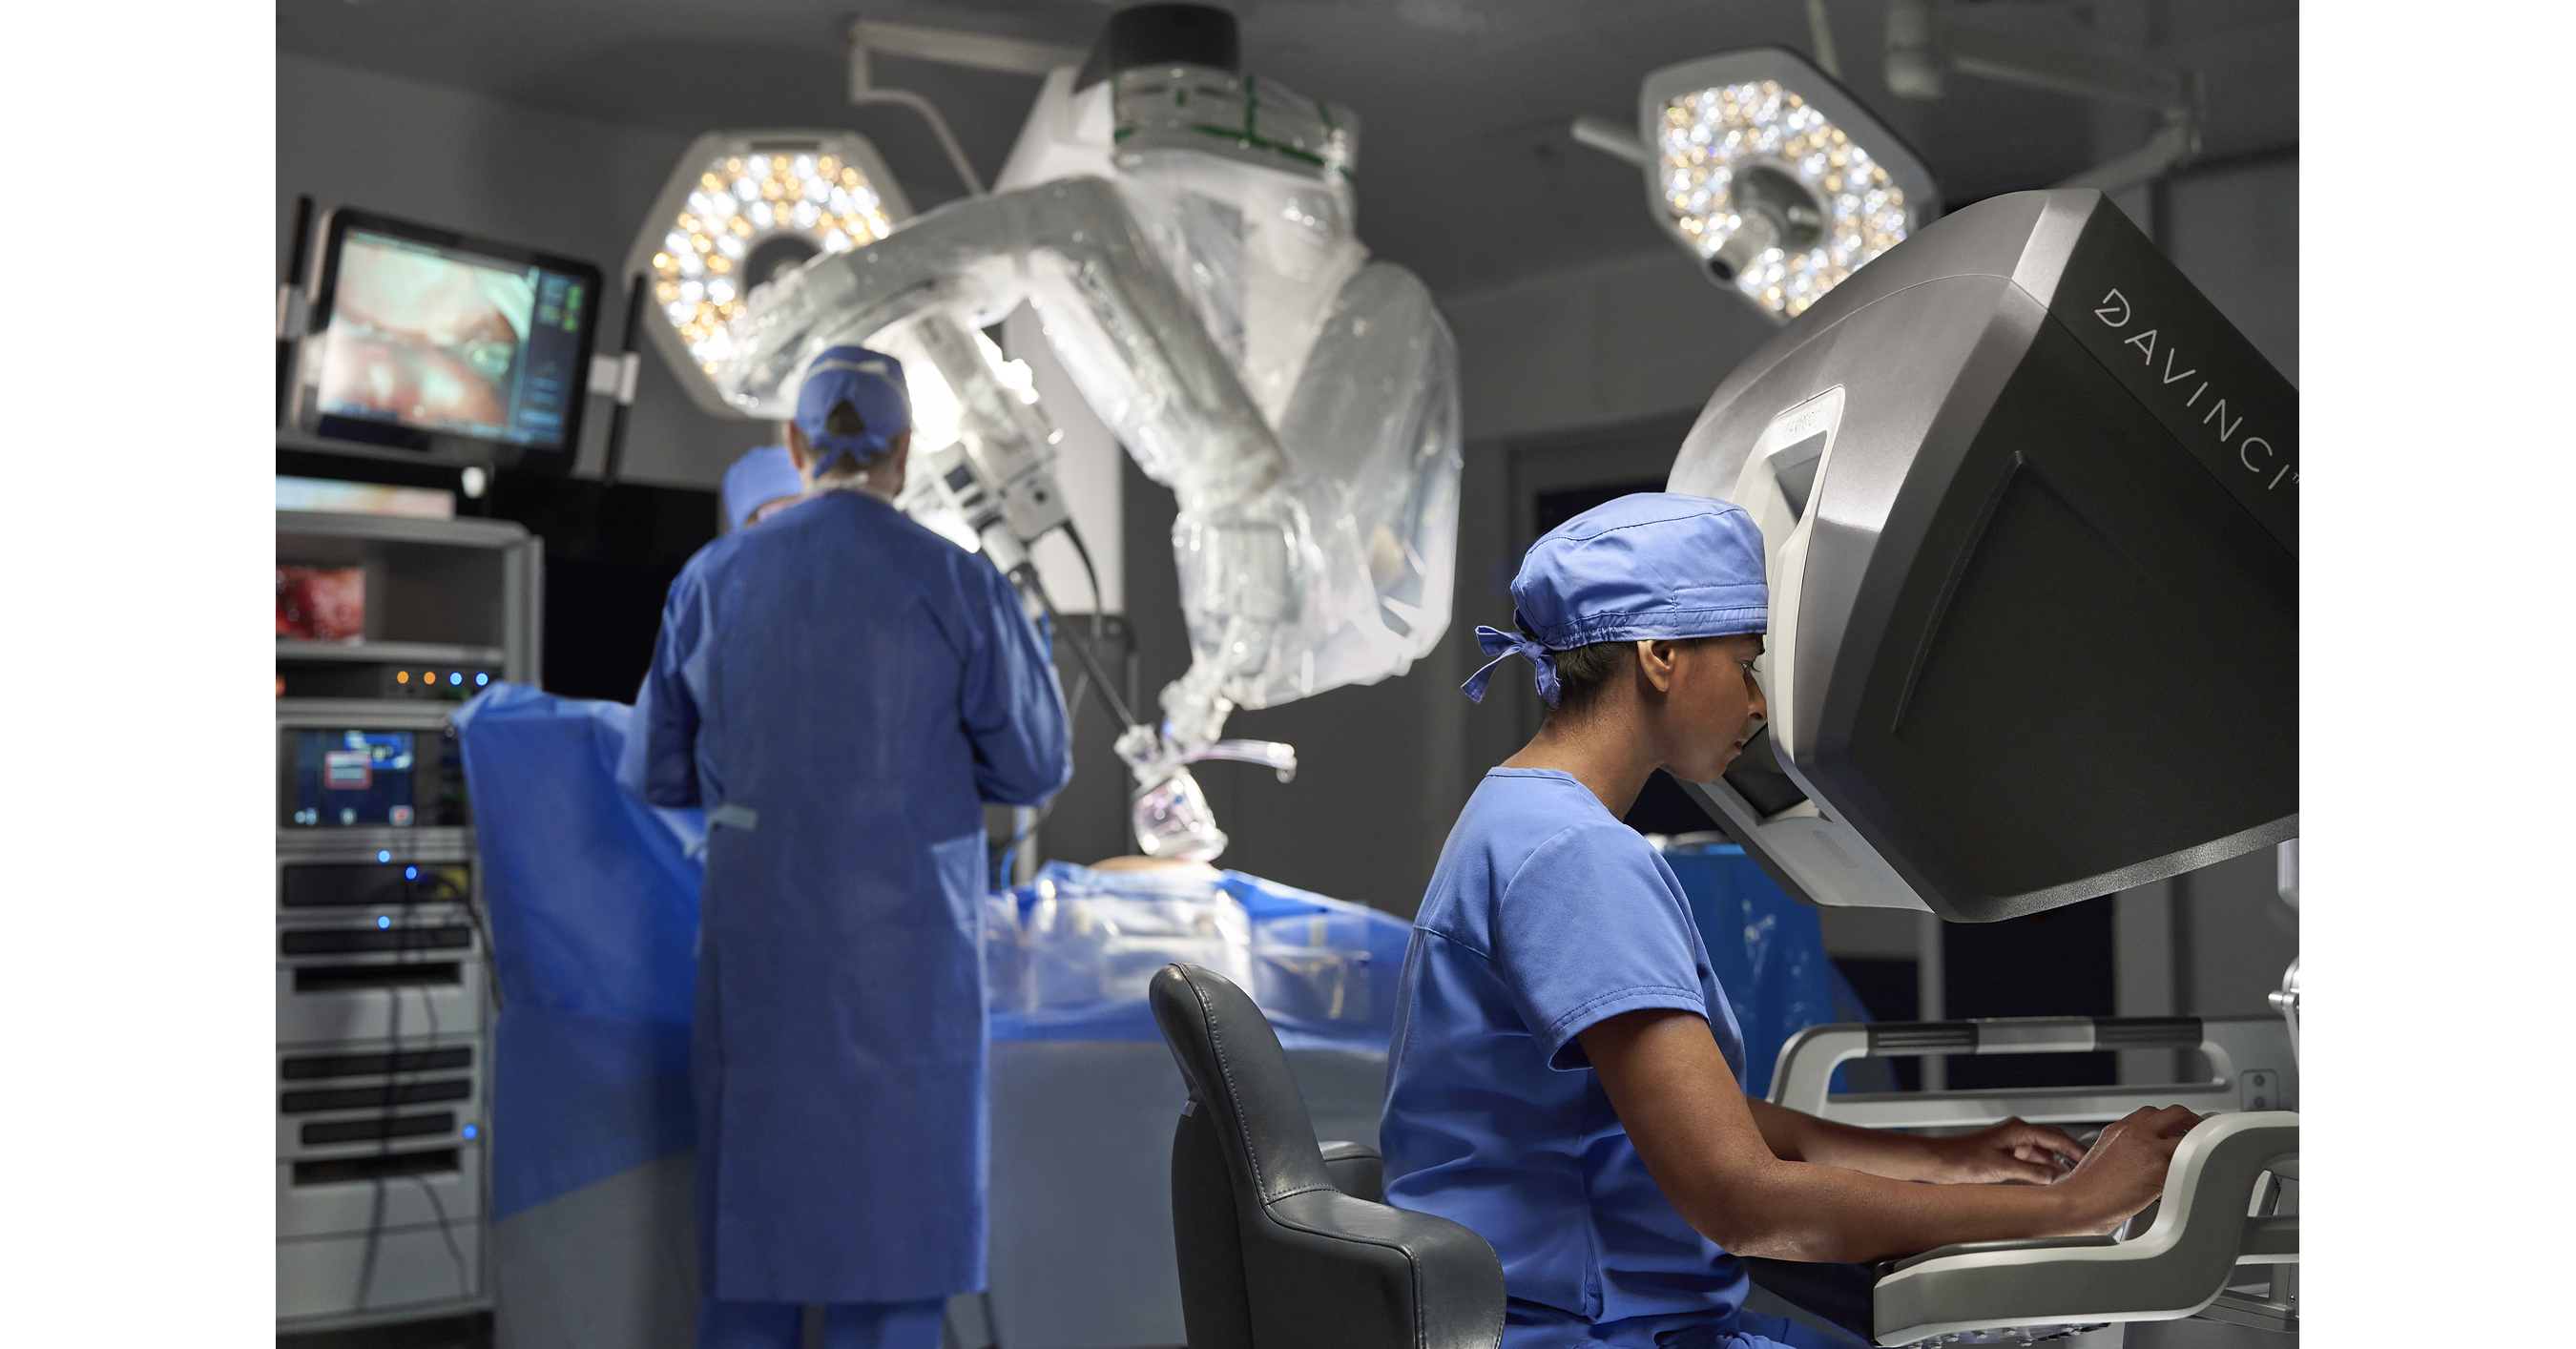
Intuitive received CE mark approval in Europe for transvaginal gynecologic procedures using its da Vinci SP surgical system, representing the system's first such indication globally. The authorization expands SP's European applications and could support adoption in women's health by enabling single-incision or natural-orifice, potentially scarless procedures. The company cited more than 1,000 peer-reviewed publications supporting the system's safety, efficacy and patient outcomes.
Analysis
This is strategically positive for ISRG because natural-orifice gynecology broadens the clinical rationale for SP beyond incremental procedure migration, potentially improving system utilization at installed accounts rather than merely adding a narrow new sales category. The key economic lever is recurring instruments and accessories: if hospitals can route benign gynecology cases through SP, procedure density and consumables pull-through can rise without a proportional increase in capital spending. Europe is also a useful proving ground for surgeon training, reimbursement pathways, and real-world outcomes that could support eventual expansion of higher-value U.S. indications.
The near-term earnings effect is likely immaterial: regulatory clearance does not establish hospital budgets, country-level reimbursement, surgeon credentialing, or clinical adoption. Investors should watch European SP procedure growth, SP placements versus multiport da Vinci placements, and management commentary on incremental gynecology utilization over the next two earnings calls. A meaningful uplift requires evidence that these cases are additive rather than cannibalizing conventional laparoscopic or existing da Vinci procedures.
Competitive implications favor ISRG's installed-base moat, but the announcement alone does not alter the broader robotics valuation debate. Medtronic (MDT) Hugo and Johnson & Johnson's (JNJ) Ottava remain more exposed to capital-cycle execution than to a comparable single-port natural-orifice workflow; however, lower-cost laparoscopy remains the practical substitute in budget-constrained European systems. The contrarian view is that reimbursement and training friction could leave this as an attractive clinical feature with limited revenue conversion for 12-24 months, making any outsized share-price response a potential fade rather than a new fundamental catalyst.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Ticker Sentiment
Key Decisions for Investors
- Maintain, but do not add aggressively to, ISRG on this release; treat it as a 6-18 month utilization optionality rather than a FY2026 estimate-changing event. Add only if subsequent results show accelerating SP procedure growth and management attributes part of the increase to European gynecology.
- Set a catalyst alert for the next two ISRG earnings calls: bullish confirmation requires disclosed SP placement/procedure momentum, stable or rising instruments-and-accessories revenue per procedure, and no deterioration in European capital demand. Absence of these signals falsifies the near-term monetization thesis.
- For a relative-value expression over 3-6 months, favor long ISRG versus short MDT only if ISRG's premium valuation has already compressed on broader medtech weakness; the thesis is superior recurring-revenue conversion and installed-base utilization, not immediate share gains from the clearance.
- Avoid buying short-dated ISRG calls solely on the announcement. The timing of reimbursement, training, and hospital rollout is too uncertain; any options exposure should be longer dated and contingent on confirmation from procedure data.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Microsoft's Big Bets on AI Start to Pay Off
- Google's Gemini 4 Carbon looks like a diamond in the rough
- Microsoft’s strong quarter backs up its stock rebound. Here's our new price target
- Can Southeast Asia pitch itself as an ‘all-in-one’ chip hub?
- As Waymo expands overseas, it remains a niche cash-burning business