
Labcorp Launches Next Generation of Labcorp Global Trial Connect™ to Help Sponsors and Investigator Sites Navigate Clinical Trial Complexity
Source: PR Newswire
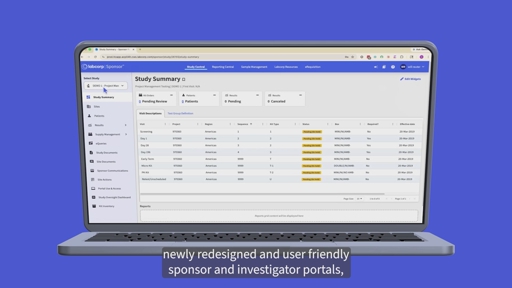
Labcorp (LH) announced enhancements to Global Trial Connect, including a unified Study Oversight Dashboard and a Report Wizard to streamline trial management and reporting. The in-portal kit ordering feature is designed to reduce manual data entry by 75%, while embedded tools add integrated oversight and supply tracking. The update is positioned as part of ongoing investment to improve clinical trial delivery efficiency; impact is likely limited to modest positive perception rather than a direct financial catalyst.
Analysis
This reads as a retention-and-workflow story more than a near-term revenue event. For Labcorp, the economic value is likely in lowering churn inside Biopharma Laboratory Services: once sponsors and sites standardize on a portal that handles ordering, tracking, and reporting, switching costs rise and procurement friction falls. That matters most in a market where central lab work is often rebid on service quality and operational reliability, not just price.
The second-order winner is LH's biopharma segment margin profile, not headline growth. If adoption is real, the company can push more volume through the same customer-facing infrastructure, which should help operating leverage over 1-3 quarters even if the effect is too small to show up as a discrete line item. The competitive pressure lands on smaller central labs and point-solution workflow vendors that lack a broad installed base; feature parity is cheap to copy, but integrated data + kit ordering + study oversight inside one system is harder to dislodge.
The market may overread this as a digital transformation catalyst when it is probably a modest moat extension. The bull case only becomes investable if management can show higher sponsor retention, faster study startup, or lower service costs per trial over the next 2-4 quarters; otherwise this remains a qualitative support for valuation rather than a catalyst for multiple expansion. Falsifiers would be any slowdown in biopharma testing volumes, no improvement in digital adoption metrics, or evidence that competitors match the workflow tools without sacrificing price.
Contrarianly, the bigger risk is not that this fails, but that it does too little to change the competitive equation while investors pay up for the narrative. If the platform is mainly an incremental UX upgrade, the stock should trade on core clinical demand and diagnostics reimbursement, not on the press release. The right framing is a watch item for customer stickiness and margin protection, not a standalone long catalyst.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Ticker Sentiment
Key Decisions for Investors
- No immediate trade: treat this as a low-signal product update and wait for evidence in LH's next biopharma segment disclosure—look for sponsor retention, trial-start timelines, or margin expansion before assigning multiple upside.
- If wanting exposure, use LH as a defensive long only on a pullback toward support, with a 3-6 month thesis tied to modest SG&A leverage in Biopharma Laboratory Services; upside is incremental, so size accordingly.
- Pair trade idea: long LH / short a more execution-sensitive clinical trial services or CRO name on any spread widening if the market starts rewarding workflow integration over pure scale; the trade only works if LH shows customer stickiness while peers lag on digital experience.
- Set an alert for evidence of adoption rather than the press release itself: watch for management commentary on portal utilization, reduction in manual processing, or improved study turnaround in the next earnings call; absent that, fade any short-term pop.
- Falsification trigger: if Biopharma Laboratory Services growth or operating margin fails to improve over the next 1-2 quarters despite this rollout, assume the digital investment is maintenance capex and not a valuation driver.
More News
- Crude Oil Moves Higher; Charles Schwab Shares Fall After Q3 Results
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- Brian Sullivan: Why the 'real' price of oil is likely $30-$40 higher than where it is now
- Penske Automotive agrees to be taken private by Penske, Mitsui
- Faraday Copper completes acquisition of BHP’s San Manuel project
- Supermicro promised a new CFO in December 2024. A $2.5 billion smuggling case and a co-founder’s arrest later, it has one