
Nina Aicardi Joins Okapi Partners as Managing Director
Source: PR Newswire
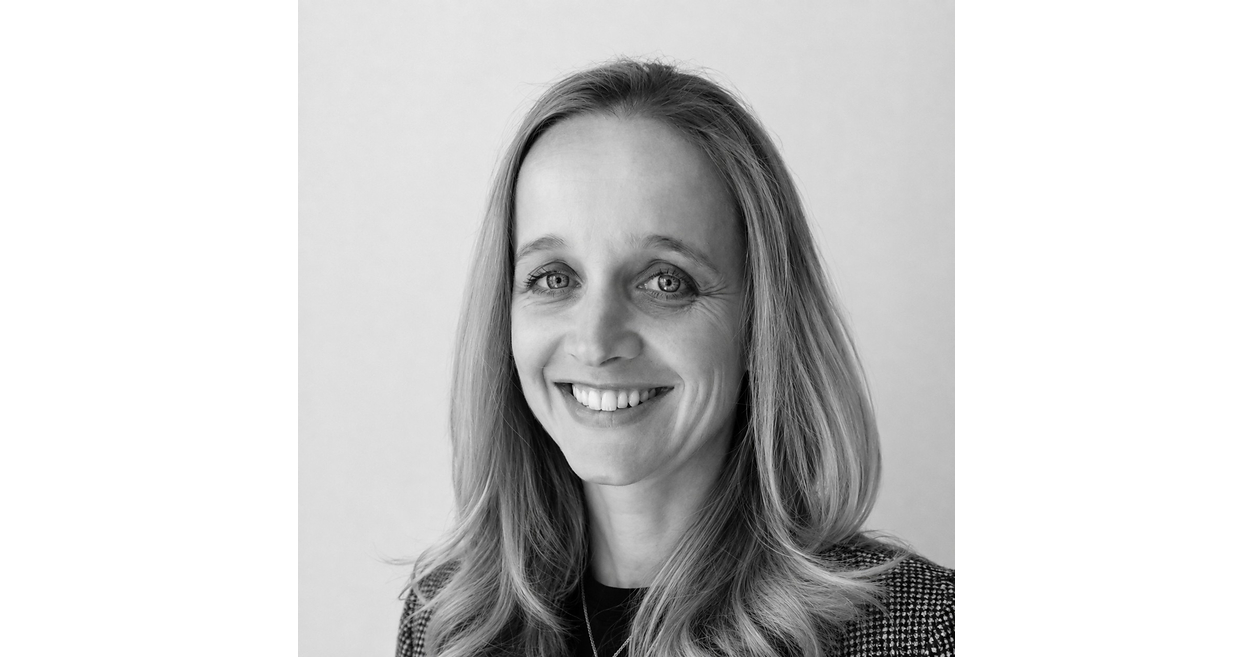
Okapi Partners appointed Nina Aicardi as Managing Director, adding a corporate-governance and proxy-advisory executive with prior leadership roles at T. Rowe Price and ISS. Aicardi will advise corporate and institutional clients globally on proxy contests, shareholder activism, governance matters, M&A situations, and shareholder meetings. The hire modestly strengthens Okapi's advisory capabilities but is unlikely to have a material public-market impact.
Analysis
This is not a fundamental catalyst for TROW: governance personnel turnover does not alter fee revenue, flows, capital returns, or earnings power. The more relevant read-through is that experienced buy-side governance professionals are increasingly monetizing issuer-side advisory expertise, reinforcing the sophistication of company defenses in contested votes and M&A situations. That modestly raises execution cost and informational asymmetry for activists, particularly in small- and mid-cap campaigns where shareholder identification and vote-turnout mechanics can determine outcomes.
For the next 1-3 months, the practical implication is to demand a wider expected-return threshold before entering publicly announced activist targets: a credible dissident slate may need clearer operational evidence, stronger ownership support, or a larger valuation discount to overcome better-prepared issuer campaigns. Event-driven funds should monitor 13D filings, universal-proxy contests, and special-committee processes rather than treat this hire as a directional signal. Over 6-18 months, continued institutionalization of proxy-defense capabilities could favor repeat activist platforms with proprietary investor relationships and operating credibility, while reducing win rates for smaller, financially engineered campaigns.
Contrarian view: the market may overestimate the durability of defensive advantages. Better issuer counsel can improve messaging and solicitation, but it cannot offset persistent underperformance, poor capital allocation, or an economically superior bid once large holders coalesce. There is no standalone TROW trade; the relevant watch item is whether TROW's governance team changes voting behavior or stewardship disclosures following the departure, which would need to be evidenced in future proxy-season voting records rather than inferred from the personnel move.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Key Decisions for Investors
- No directional action in TROW; maintain existing thesis based on net flows, equity-market levels, fee-rate pressure, and capital return. Reassess only if subsequent stewardship reporting shows a material shift in contested-election or M&A voting patterns over the next two proxy seasons.
- For announced activist situations over the next 1-3 months, favor long targets only where the dissident has disclosed meaningful ownership, a concrete board slate, and a readily measurable operating or capital-allocation catalyst; avoid relying solely on headline activist involvement.
- Build an event-driven watchlist around universal-proxy contests in small/mid-cap issuers. Require a larger discount to independently supported breakup value or strategic-bid value before underwriting a long, as issuer-side solicitation quality may lower dissident win probability.
- If proxy-defense and solicitation spending begins to rise broadly in contested issuers, consider it a margin headwind for smaller public companies rather than a sector-wide governance trade; validate through quarterly SG&A commentary and contest-specific filings.
More News
- Biotech stocks are surging. How investors can play the new drug innovation boom
- Braskem creditors, shareholders near deal on $11bn debt restructuring
- Instacart reportedly discussed selling itself with DoorDash and Uber
- Thousands of Israelis rally against Netanyahu gov’t days before election
- ‘There’s nothing temporary about a temporary store’: How Spirit Halloween’s CEO took it from 130 stores to 1,550—and swallowed your mall’s Hot Topic
- J&J prostate cancer drug shows promising tumor responses in early trial
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AllMind Fixed Income Compass for October 2025: Navigating Policy Divergence and Political Risk
- AI Equity Research Tools for RIAs and Wealth Managers