
VinFast Certified Pre-Owned Program Delivers Exceptional Financing Value with APRs Starting at 2.99%
Source: PR Newswire
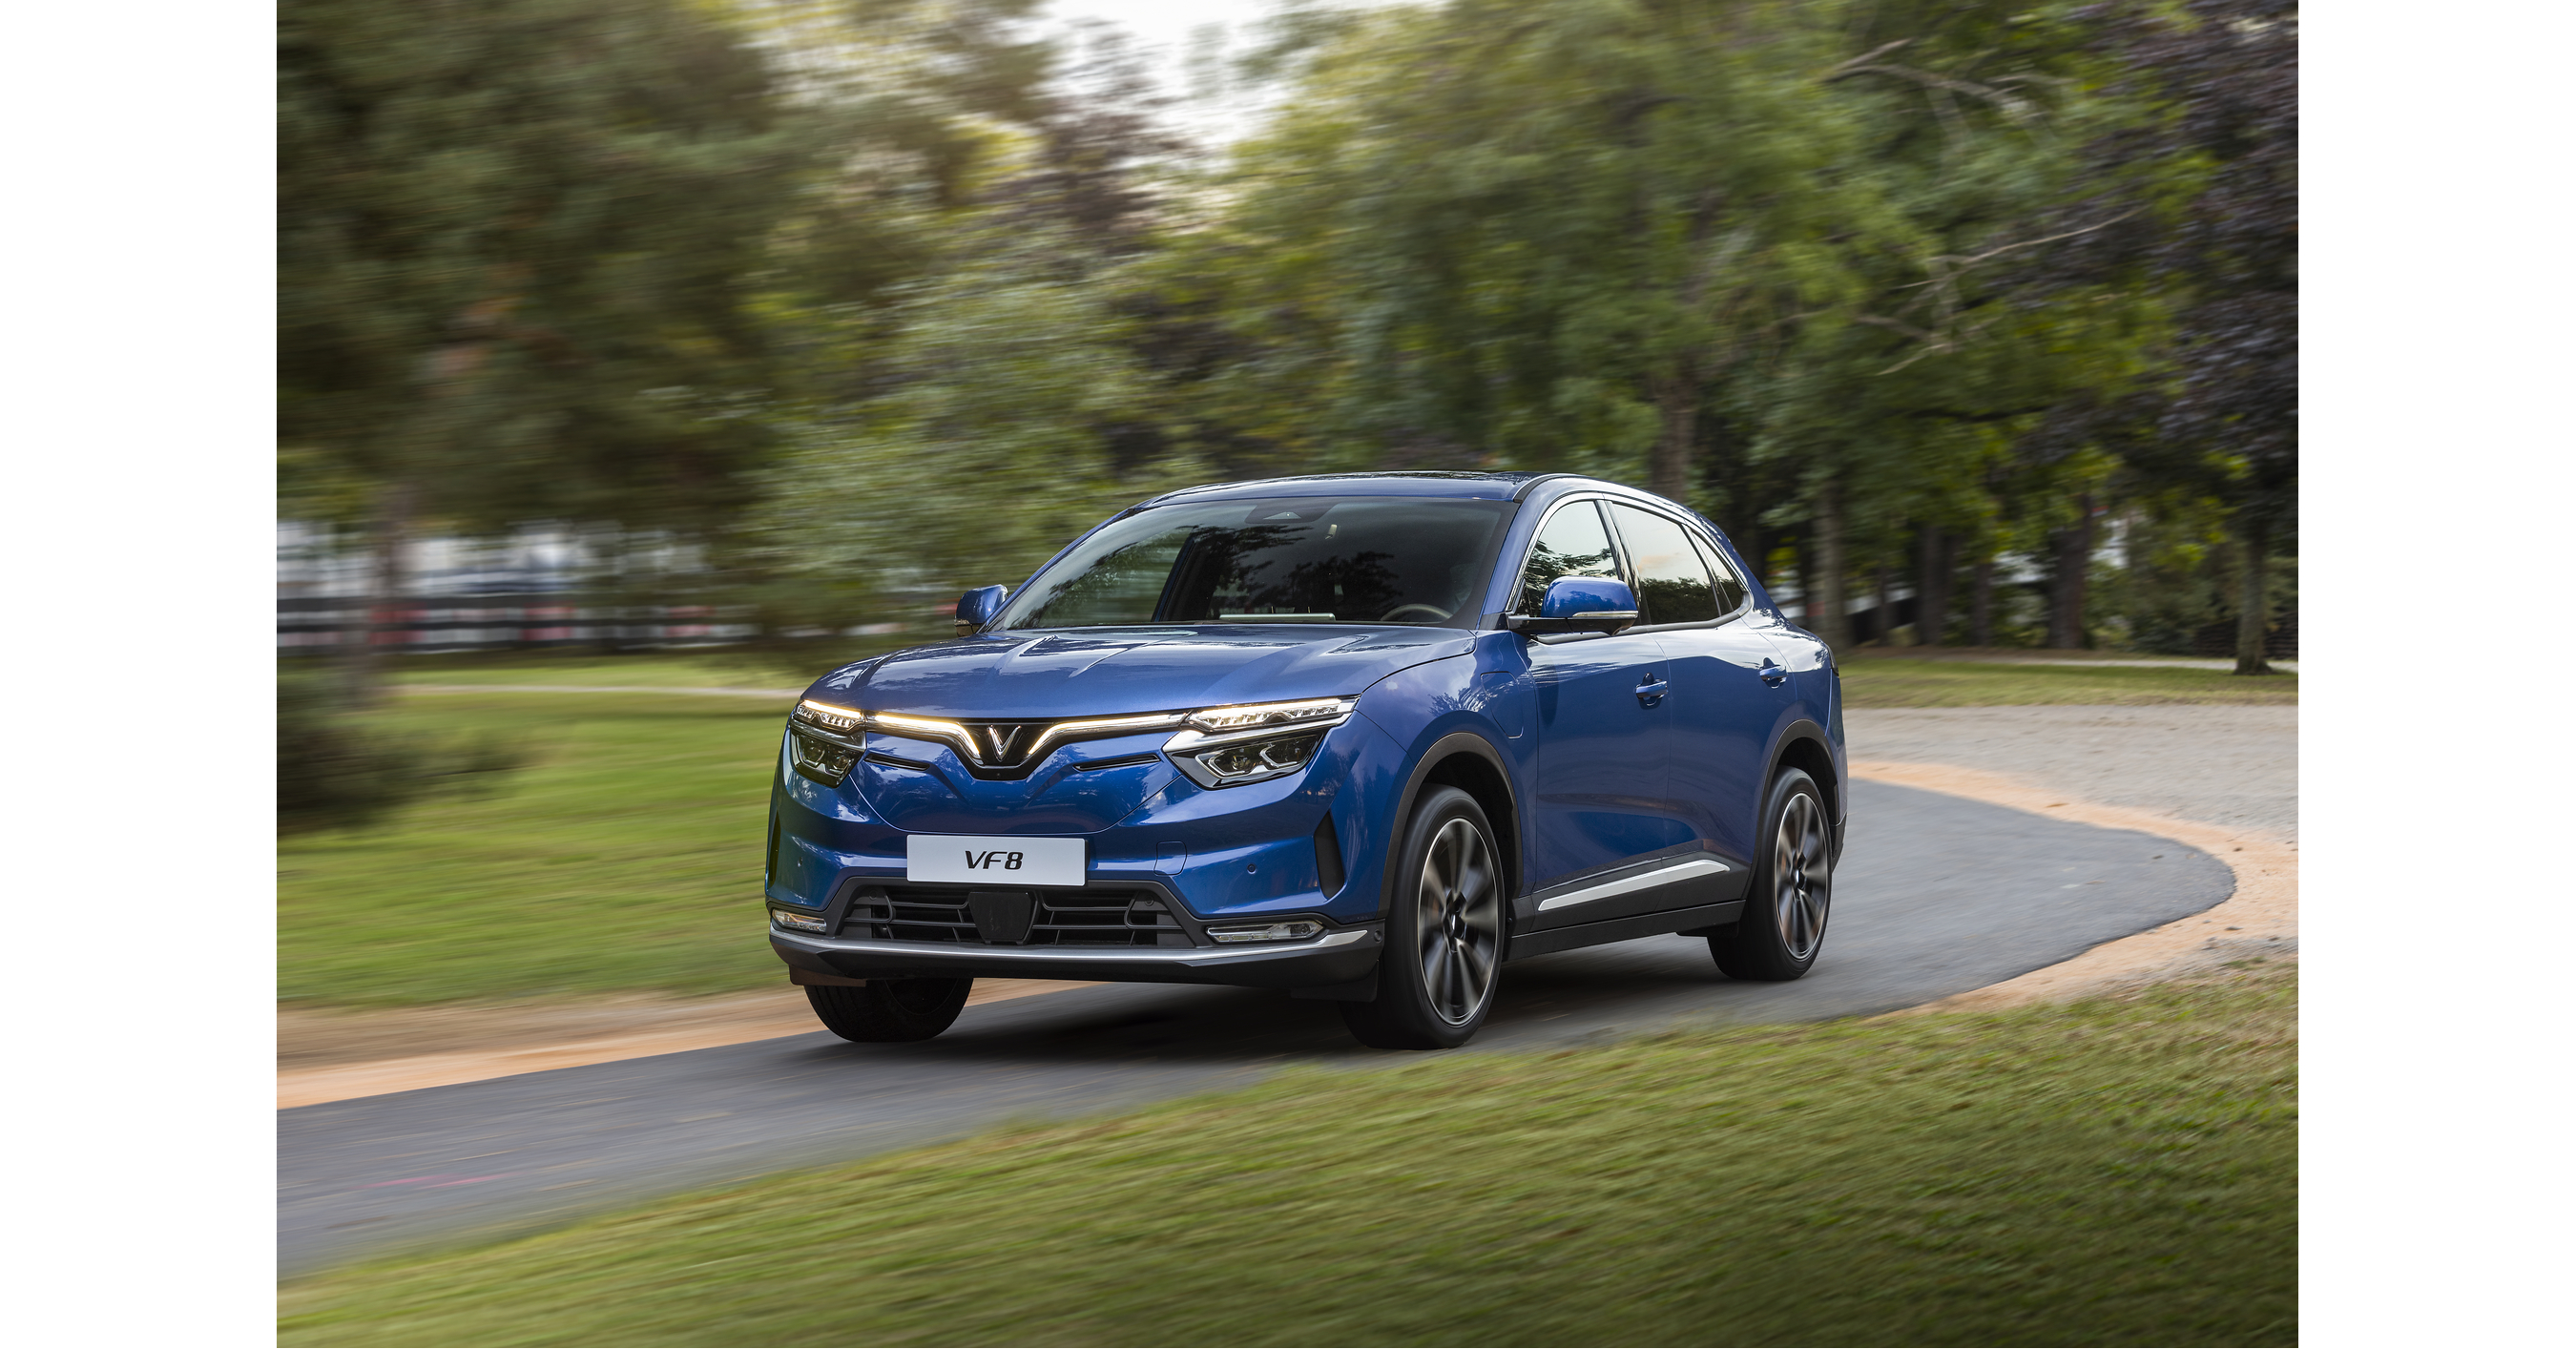
VinFast launched a U.S. certified pre-owned EV program with financing starting at 2.99% APR for terms up to 72 months, versus average Q1 2026 U.S. used-car loan rates of 11.43% and new-car rates of 6.39%. The company positions the offer, up to 10-year warranty coverage, and an expanding dealer network as measures to improve EV affordability, residual values, and customer confidence. VinFast estimates a VF 8 Eco driven 2,000 miles monthly could reduce five-year energy costs by about 58%, to $7,811 from $18,528 for a comparable gasoline SUV.
Analysis
The relevant economic variable is not the advertised APR but the subsidy required to fund it. If VinFast or a financing partner is absorbing several hundred basis points versus market funding costs, each incremental CPO unit can improve fleet turnover and reduce residual-value anxiety while diluting gross profit and potentially creating recourse exposure to weaker-credit borrowers. Management needs to disclose CPO inventory, approval rates, credit-loss reserves and subsidy cost before this can be treated as a demand or margin catalyst.
A credible CPO channel can improve new-vehicle lease economics over 6-18 months: stronger expected residual values reduce lease payments, lowering the required new-car incentive. That mechanism is strategically valuable for VFS versus newer EV brands without mature used-car infrastructure, but it only works if dealer/service coverage, parts availability and warranty claims support resale pricing; otherwise the program merely warehouses depreciation risk on VinFast's balance sheet.
Near term, this is unlikely to move sector fundamentals or affect TREE and EXPN materially. The contrarian read is that aggressive subsidized CPO financing may signal a need to clear returned, demo or slow-moving inventory rather than organic used-EV demand; used-EV pricing remains highly sensitive to further new-EV price cuts, which can immediately impair CPO residuals. A positive thesis is falsified if CPO-related incentives rise without sequential improvement in deliveries, vehicle gross margin, or inventory days over the next two reporting periods.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Ticker Sentiment
Key Decisions for Investors
- No standalone VFS long on the announcement. Place a 1-3 month monitoring trigger for disclosed CPO unit volume, finance penetration, average incentive per vehicle and used-vehicle gross margin; consider a tactical long only if CPO penetration exceeds 10% of U.S. deliveries without a sequential deterioration in consolidated vehicle margin.
- Treat VFS as a high-volatility event watch rather than a core position: any long should be small and paired with an EV-sector hedge such as short DRIV or short TSLA only after confirming that VinFast-funded APR subsidies are capped. Exit on evidence of rising inventory, warranty reserve growth, or expanded financing recourse.
- Avoid extrapolating this into TREE or EXPN. The program does not create enough incremental loan-origination or credit-data volume to alter their earnings outlook; revisit only if multiple OEMs adopt broad captive-finance subsidies, which would be a more meaningful signal of auto-credit competition and lender-margin pressure.
- Watch Manheim used-EV pricing and VinFast new-vehicle incentives over the next 90 days. A renewed new-EV price cut would likely overwhelm any CPO residual-value benefit and shifts the setup negative for VFS's future lease and used-vehicle economics.
More News
- Financial AI startup Casap raises $56 million to help banks stop an explosion of customer fraud
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Fortinet’s stock is taking a dive after earnings. Here’s why.
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- Microsoft's Big Bets on AI Start to Pay Off