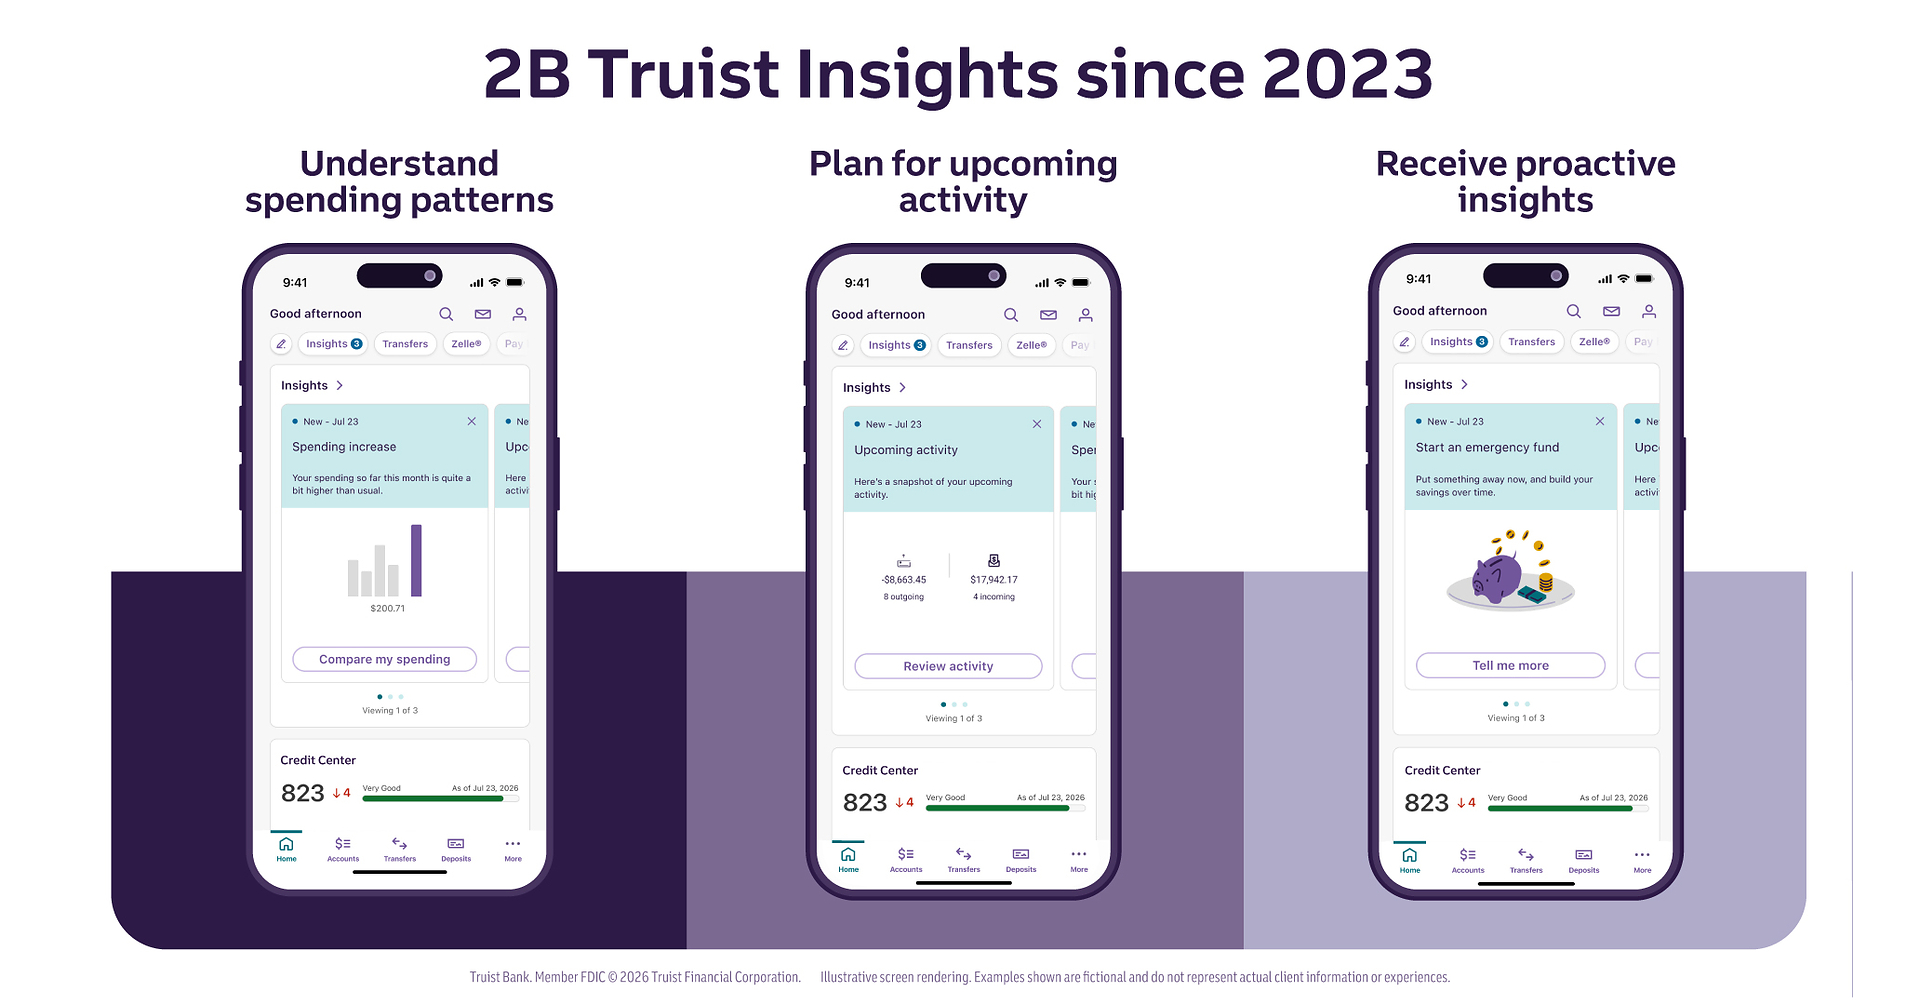
Truist Financial (TFC) said clients have received 2+ billion proactive “Truist Insights” financial guidance interactions since 2023, and the program is being embedded more deeply into digital banking (account details, planning dashboards, Truist Assist, and push notifications). Truist reports a 4.5 client satisfaction rating and “industry-leading engagement,” with personalization using AI/data analytics to surface items like low-balance activity, subscription changes, and potential duplicate transactions. The update is a positive product/engagement milestone but is unlikely to be broadly market-moving in the near term.
The only economically meaningful read-through is that digital personalization can become a low-capex lever for deposit stickiness and cross-sell, which matters more in banking than the raw count of “insights.” If TFC can convert engagement into higher primary checking penetration, better card attachment, or lower attrition, the upside is incremental margin and a modest deposit beta advantage versus regional-bank peers. That creates a second-order pressure on peers with weaker digital funnels to either spend on similar tooling or accept slower fee-income growth.
Near term, this is mostly a sentiment and execution story, not a hard financial inflection. The market should wait for evidence in quarterly disclosures: conversion rates from insight to action, digital active user growth, average deposits per relationship, and any change in servicing expense. If those metrics don’t move, the initiative is a branding exercise; if they do, TFC deserves a small-quality premium versus KRE constituents over the next 6-18 months.
The main risk is that “AI personalization” is highly replicable and can backfire if customers perceive push alerts as sales pressure, raising opt-outs and privacy scrutiny without improving economics. The contrarian view is that consensus may be overvaluing the moat while underestimating how quickly JPM, BAC, and Wells can copy the feature set. The thesis is falsified if TFC’s next 2-3 quarters show no improvement in digital engagement translating into loan/card growth or deposit retention, or if client complaints/opt-out rates rise.
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialOverall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
