
Bitmine Immersion Technologies (BMNR) maakt bekend dat zijn ETH-bezit 6,03 miljoen tokens bedraagt en dat de totale waarde van zijn cryptobezittingen, liquide middelen en verhandelbare effecten 16,2 miljard dollar bedraagt
Source: PR Newswire
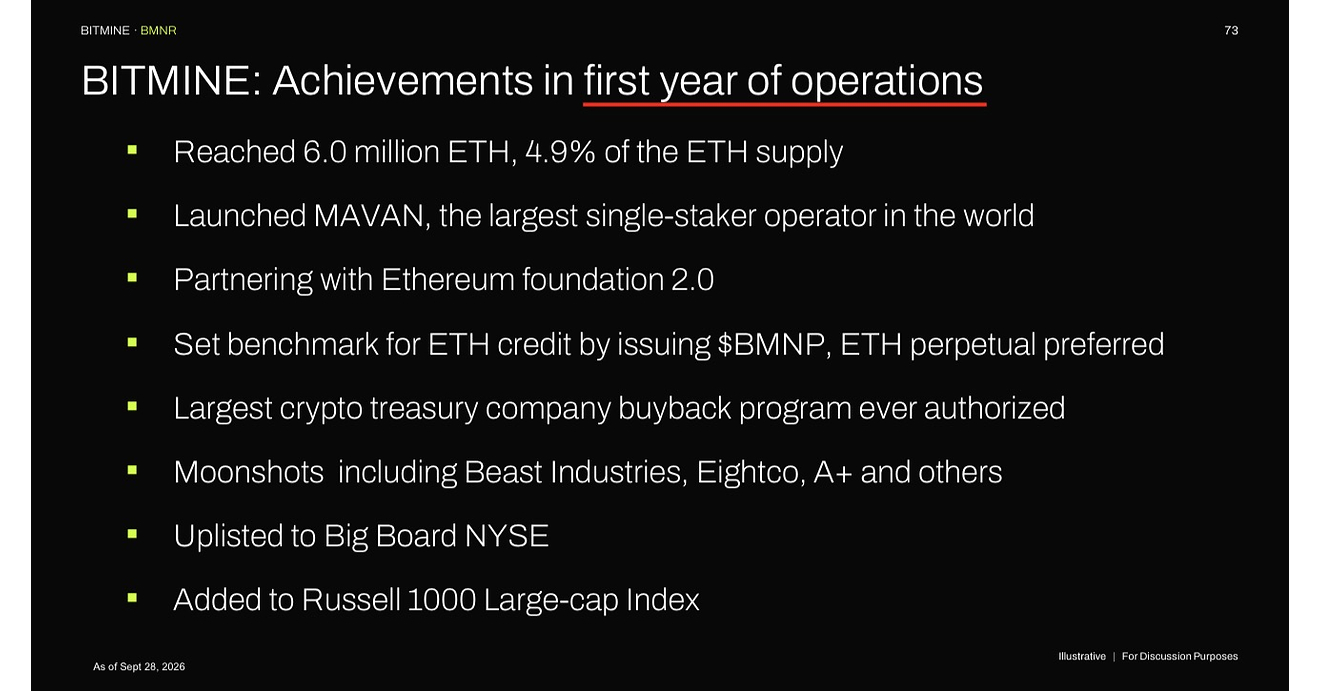
Bitmine reported holdings of 6,028,946 ETH, valued at $2,544 per token, and total crypto assets, cash, marketable securities and “moonshot” investments of $16.2 billion as of October 11, 2026; its ETH represents 4.9% of the 122.1 million-token supply. It said 5,067,309 ETH is staked, worth $12.9 billion, and estimated annualized staking rewards of $336 million at the recent seven-day yield of 2.61%, potentially rising to $400 million at full scale. Chairman Thomas Lee expects a major crypto bull market; these are management views, and the release notes that actual prices and staking returns may differ materially.
Analysis
The key exposure is not simply ETH upside: BMNR is turning a concentrated, mostly staked treasury into an operating and financing structure. That can amplify ETH gains, but also makes the equity vulnerable to a widening discount to net asset value if investors question custody, liquidity, dilution, or the sustainability of staking economics. Staking rewards are paid in ETH; dollar income is therefore price-sensitive, and a recent annualized yield is not a fixed earnings run rate. With most holdings staked, a sharp selloff could also expose a mismatch between liquid liabilities or funding needs and the time required to access ETH.
The claimed approach to 5% supply is a potential structural catalyst for ETH, but the marginal impact depends on whether purchases are genuinely incremental rather than funded by share issuance, and whether other treasury holders sell. Concentrated staking also raises a second-order protocol and regulatory risk: greater dependence on a small number of operators can invite scrutiny and make outages or slashing more consequential. MAVAN’s external institutional business could diversify income over time, but the release provides no independently verifiable customer, fee, or utilization data.
Near term, the announcement is promotional rather than a new earnings disclosure; avoid extrapolating management’s bull-market thesis or short-period yield claims. Over 1–3 months, track BMNR’s premium/discount to ETH-adjusted NAV, share issuance, staking yield and unlock liquidity. Over 6–18 months, execution on third-party MAVAN revenue and capital discipline matter more than the 5% milestone. ORBS may receive sympathy attention from the disclosed investment, but the holding alone does not establish a material earnings benefit. The thesis weakens if ETH falls, BMNR’s NAV premium expands without improved per-share backing, or staking yields/net inflows decline.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- No event-driven long in BMNR on this release alone. Verify the latest share count, market capitalization, preferred obligations, ETH custody/staking terms, and fully diluted ETH per share before underwriting the equity’s NAV premium or discount.
- Set a relative-value alert: if BMNR trades at a substantial premium to independently calculated ETH-adjusted NAV, consider long ETH / short BMNR rather than outright shorting ETH-sensitive exposure. Exit or reassess if the premium compresses, per-share ETH backing rises without material dilution, or verifiable MAVAN fee revenue emerges.
- Track weekly ETH purchases against equity and preferred issuance, plus staking rewards net of operating costs and any unstaking queue. A slowdown in net ETH-per-share accumulation or a material change in staking yield would falsify the accumulation-and-carry case.
- Treat BMNP’s quoted yield and price performance as market pricing, not proof of credit stability. Monitor dividend coverage, funding sources, and trading relative to par; deterioration would be an early warning for BMNR’s financing flexibility.
- Do not infer a fundamental ORBS re-rating from BMNR’s investment disclosure. Revisit only if Eightco reports independently verifiable commercial or financial developments tied to the investment.
More News
- Why is Strategy stock sliding today?
- Why is Samsung Electronics stock plunging today?
- SK Hynix plunges 8% amid Asia tech rout as Fed rate hike fears, AI funding worries mount
- Elon Musk says Trump is 'ultimately' responsible for any curbs on Ukraine's Starshield systems
- SK Hynix seeks U.S. chip equipment exports to China tied to new factory
- Dell stock plunges 11%, leading data center sell-off on concerns about 'enterprise AI timing'