
Angel Aligner actualiza Torque Ridges a "Pressure Points" en Europa
Source: PR Newswire
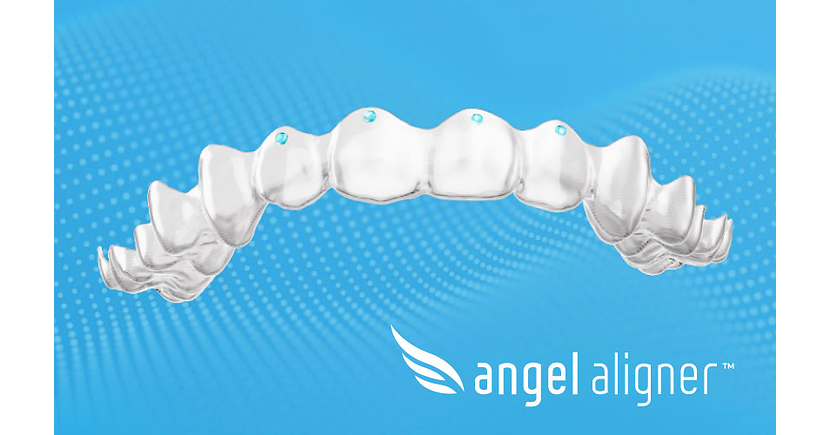
Angelalign launched its upgraded "Pressure Points" feature for orthodontists in Europe, replacing Torque Ridges to improve clear-aligner torque control. The single-pressure-point configuration increases tooth-surface contact by 25% and is intended to provide more predictable force application and greater digital scalability. The company plans a global rollout and future applications for tooth rotation and intrusion, but the announcement provides no revenue, sales, or financial guidance.
Analysis
The near-term earnings relevance is likely immaterial: a software/design-feature rollout does not change case volume, average selling price, or manufacturing utilization unless it demonstrably reduces refinements and chair time. The relevant KPI is not adoption announcements but European doctor-level case starts, refinement rates, and realized revenue per case over the next two reporting periods. If the feature lowers mid-course corrections, Angelalign could gain margin through fewer remake shipments and improve clinician retention without discounting—more valuable than a modest headline-driven increase in new accounts.
Competitive read-through is modestly negative for Align Technology (ALGN) and Straumann (STMN.SW) only at the margin. Clear-aligner purchasing decisions are strongly influenced by treatment-planning workflow and clinical predictability; a credible improvement in difficult tooth-movement outcomes can reduce the premium incumbents receive for established digital ecosystems. However, this is a company press release with no controlled clinical data, pricing change, or quantified rollout economics, so the market should not capitalize it as a structural share-gain event before independent evidence emerges.
Consensus risk is that investors may overvalue feature parity as differentiation. The higher-probability outcome over 1-3 months is limited trading impact, while the 6-18 month upside case requires measurable European penetration, expansion beyond the initial use case, and evidence that digital planning improvements translate into lower refinement expense. A reversal would be signaled by no acceleration in overseas revenue growth, unchanged gross margin, or clinician feedback indicating the feature adds planning complexity rather than reducing it.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Key Decisions for Investors
- No immediate directional trade in 6699.HK: treat the release as an operational watch item, not an earnings catalyst. Reassess after two quarterly reports if overseas case starts accelerate and gross margin expands concurrently; either metric alone is insufficient.
- Set a relative-performance monitor for 6699.HK versus ALGN and STMN.SW over the next 3-6 months. Consider a small long 6699.HK / short ALGN pair only if Angel reports independently measurable European share gains or refinement-rate improvement while ALGN's clear-aligner volumes decelerate; without those data, execution and liquidity risk outweighs expected alpha.
- For existing 6699.HK exposure, require evidence that revenue per case and operating margin improve within 6-12 months before assigning a valuation premium for clinical innovation. Failure of either metric to improve should falsify the margin-expansion thesis and argue against adding on product-launch enthusiasm.
More News
- FAA says Boeing 737 Max software glitch not a flight-safety issue
- Your health insurance premiums may take a big jump in 2027 — here's why
- Anthropic to invest $100 million to train AI engineer talent
- Big Pharma turns to China for new drugs as patent cliff drives multibillion-dollar deals
- Why Lilly and Novo are betting on amylin to power a new wave of obesity drugs after GLP-1s
- Why AMD Stock Jumped 30% in September
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Research Workflows, Report Format Selection, and Interactive Synthesis
- Can ChatGPT Analyze a 10-K? A Verification Workflow